Top 7 Lenders for Subprime Personal Loans in 2026

Subprime personal loans

Top 7 Lenders for Subprime Personal Loans in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Trying to fix your credit can feel like wandering through a thick fog. When your score isn’t where it needs to be, finding a way out often feels impossible. Many people find themselves stuck in a loop, searching for a way to bridge the gap between their current bank balance and their long-term goals.

Finding a lender that looks past your credit score to the person underneath is a vital first step. You shouldn’t just grab the first interest rate you see in a headline. You have to weigh how fast you get the cash against what the loan will actually cost you in the end.

Speed matters when a car breaks down or a medical bill arrives unexpectedly. However, long-term affordability is what keeps your head above water when those monthly payments finally start rolling in. Because everyone’s financial life is different, a one-size-fits-all approach rarely works.

  1. JetzLoan
  2. Avant
  3. OneMain Financial
  4. OppLoans
  5. LightStream
  6. Hearth
  7. USPS Federal Credit Union

How These Lenders Were Evaluated

We focused on how easy it is for people with less-than-perfect credit to get a seat at the table. A huge part of this was looking for lenders that allow you to get a quote without a hard credit pull. This keeps your score from taking a hit while you are just window shopping.

We also poked and prodded how transparent these companies are about their fees. We looked at how quickly the money actually lands in your bank account and how much they are willing to lend. Nobody wants to find out about a hidden fee after the money is already spent.

Application simplicity was a major factor in our decision. If you are facing an emergency, waiting a week for funds is not an option. We checked to see if the application was a digital marathon or a quick sprint through a few simple questions to get you moving.

Lender Name Loan Amounts Funding Speed Credit Impact (Check) Starting APR / Terms
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull See site
Avant $2,000 – $35,000 Fast decision See site See site
OneMain Financial $1,500 – $30,000 As soon as 1 hour No credit score impact 11.99% APR / 24-60 months
OppLoans See site Same-day funding available Does not affect FICO score See site
LightStream See site Next day See site Low fixed rates (Excellent credit req.)
Hearth See site See site See site See site
USPS Federal Credit Union See site See site See site As low as 4.75% APR

1. JetzLoan

JetzLoan – jetzloan.com

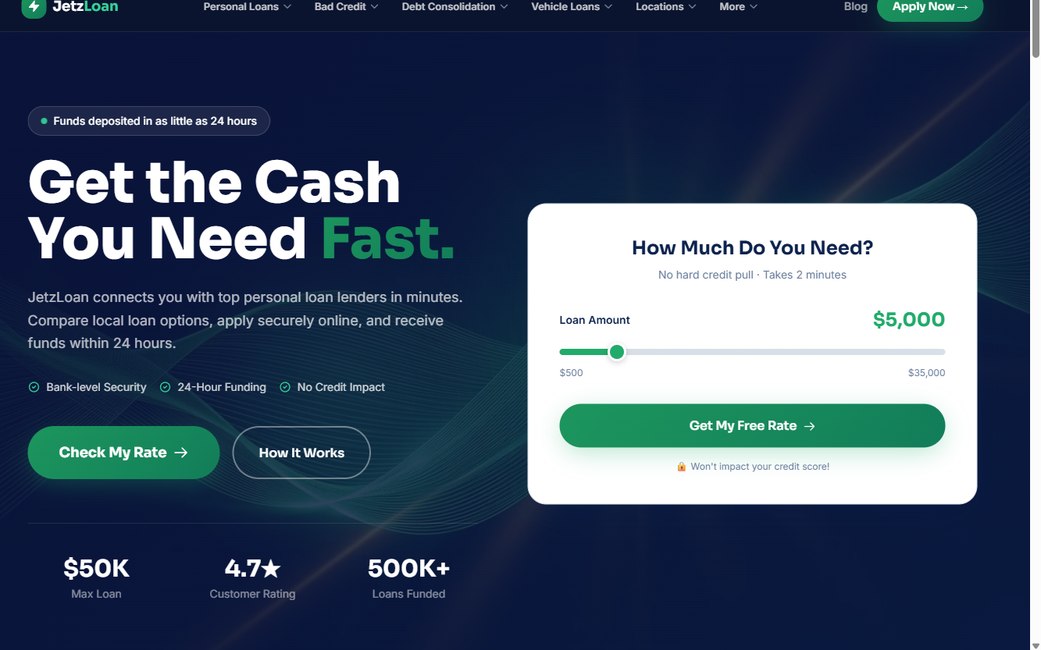
JetzLoan works by connecting borrowers with various top personal loan lenders in just a few minutes. This platform is built for speed. They aim to get funds deposited into accounts in as little as 24 hours, which is a lifesaver when things go wrong suddenly. It is useful for debt consolidation or vehicle loans without a long, drawn-out ordeal. (jetzloan.com)

The process is incredibly lightweight. You only need to fill out a simple form that takes less than two minutes. Since they offer a no-hard-credit-pull check, you can explore your options without worrying about damaging your score. It is a low-risk way to see what is actually possible for you.

Pros:

  • No hard credit pull during the initial check.
  • Fast 24-hour funding capability.
  • High customer rating of 4.7 stars.

Cons:

  • It is a connection service rather than a direct lender.

2. Avant
Avant – avant.com

Avant targets people who need a clear path forward. They offer various tools designed to help users move financially, including personal loans and credit cards. This makes them a versatile choice for different milestones. They focus on providing options for people whose financial lives are in a state of transition.

The application for their personal loans is straightforward. You only need to go through three simple steps to reach a decision. Whether you need an emergency loan or cash for home improvements, Avant uses digital-first solutions to make the journey a bit easier.

Pros:

  • Simple 3-step application process.
  • Covers a wide range of needs like debt consolidation.
  • Flexible product options including credit cards.

Cons:

  • Specific loan amounts are restricted to a specific range.

3. OneMain Financial
OneMain Financial – onemainfinancial.com

OneMain Financial is a great pick for those who prefer a mix of digital ease and talking to a real person. They have over 1,300 branches, so you can walk in and talk to someone if things get complicated. They offer personal loans from $1,500 up to $30,000, which covers most mid-sized expenses.

Speed is a big part of their appeal. Some users see money in their accounts as soon as one hour after signing. The terms are predictable, with fixed monthly payments and lengths between 24 and 60 months. This predictability helps anyone trying to stick to a strict monthly budget.

Pros:

  • Extensive branch network for in-person support.
  • Very fast funding possible within one hour.
  • Fixed monthly payments for predictable budgeting.

Cons:

  • Requires a formal signing process to unlock funds.

4. OppLoans
OppLoans – opploans.com

OppLoans specializes in helping people who might have been turned down by traditional banks. Their platform works with bank partners to look at more than just a single credit score. This makes them a strong candidate for anyone needing same-day funding to handle an urgent crisis.

The application is built around the user. They aim for decisions that arrive in just a few minutes. They also emphasize transparency by stating there are no hidden fees, which is a breath of fresh air in the subprime lending market. It is a streamlined option for quick, direct assistance.

Pros:

  • Same-day funding is available for approved users.
  • Decisions are often made within minutes.
  • No hidden fees to worry about.

Cons:

  • Approval is subject to bank partner criteria.

5. LightStream
LightStream – lightstream.com

LightStream is a specialized choice. People often favor them when they want to finance high-value items like boats or major home renovations. They run on a “Lending Uncomplicated” philosophy, focusing on a smooth digital experience. Many customers find they have the funds by the very next day.

While they are great for specific purposes, they aren’t a catch-all for everyone. They typically require excellent credit to get those low rates. However, if you have a solid history and need a large-scale loan, the efficiency is hard to beat.

Pros:

  • Very fast funding, often by the next day.
  • Excellent for specific purpose loans like boats.
  • Highly rated customer experience for smooth processes.

Cons:

  • Requires excellent credit for the best rates.

6. Hearth
Hearth – hearth.com

Hearth operates more as a knowledge hub than a standard lender. Since 1995, they have been a staple for information on energy-saving equipment, like wood or pellet stoves. They focus heavily on promoting efficient and responsible uses of various fuels.

They might not be the first place you go for a quick cash loan for an emergency, but their forums are incredibly useful. If your financial needs involve home energy efficiency or specific equipment, the community advice found here is gold.

Pros:

  • Decades of expertise in energy-related financing topics.
  • Extensive community forums for peer advice.
  • Focuses on responsible and safe fuel use.

Cons:

  • Not a direct personal loan provider for general cash.

7. USPS Federal Credit Union
USPS Federal Credit Union – uspsfcu.org

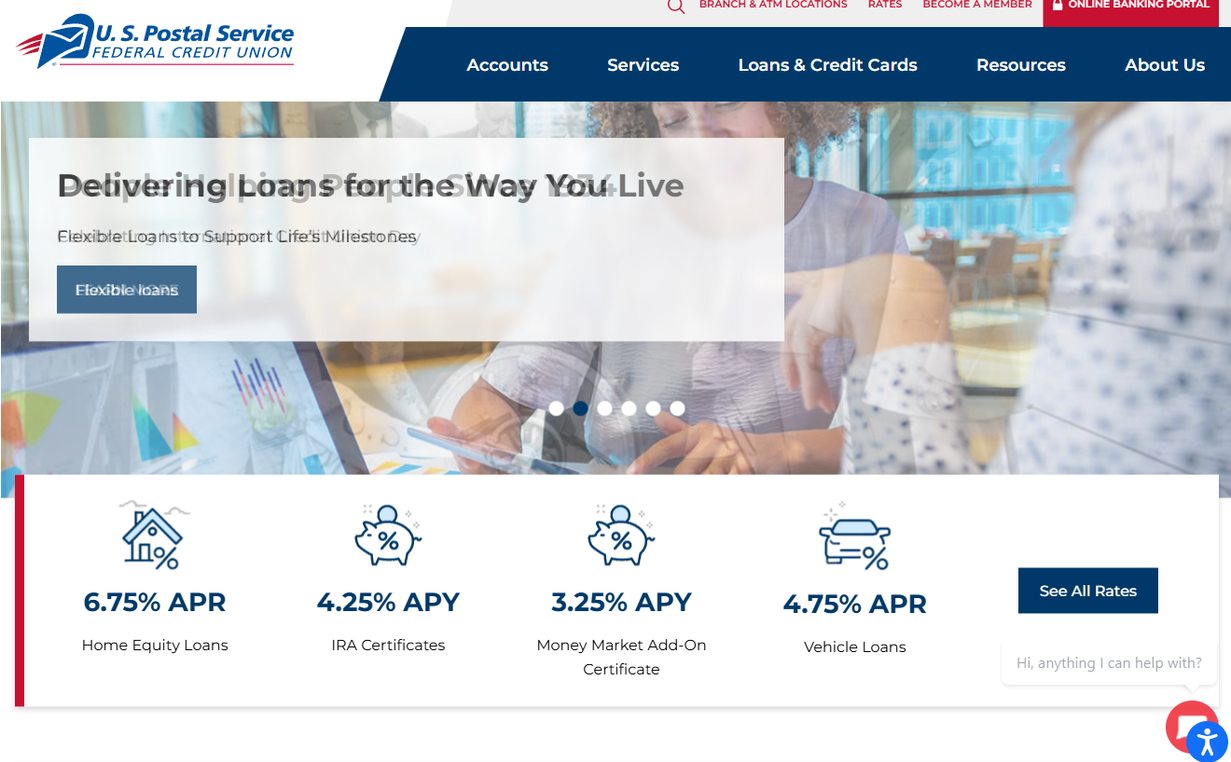
The USPS Federal Credit Union is a dedicated institution for postal employees. They offer a sense of community and specialized service that you just don’t find at big banks. Their loans support life’s milestones, from auto loans to flexible personal options.

They offer competitive rates, with some starting as low as 4.75% APR for certain products. For members, the value lies in their “People Helping People” philosophy. It creates a sense of security and shared purpose in every transaction you make.

Pros:

  • Very competitive rates for members.
  • Strong community focus on serving employees.
  • Diverse range of products like HELOCs and credit cards.

Cons:

  • Membership is restricted to specific employee groups.

Avoiding Common Pitfalls

Read the fine print on the total cost of your loan before you sign anything. A low monthly payment sounds great, but if it stretches over several years, you could end up paying double what you originally borrowed. Always calculate the total interest you will pay over the life of the loan.

Don’t rush into the first offer that lands in your mailbox. Even if you need the cash quickly, it is vital to compare rates and terms. Use the “no impact” checks offered by many lenders to shop around without fear. Taking a moment to compare can save you thousands of dollars.
Top 5 Lenders for Bad Credit Loans in Ohio: 2026 Rankings

Bad credit loans ohio

Top 5 Lenders for Bad Credit Loans in Ohio: 2026 Rankings

Last updated: 2026-10-17

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Trying to manage money in the Buckeye State can feel like driving through a Cleveland snowstorm without winter tires. One minute you are fine, and the next, a sudden transmission failure or an urgent dental bill in Columbus leaves you scrambling. Unexpected property tax adjustments can also throw a wrench in your monthly budget.

Many Ohioans find themselves hunting for quick cash solutions that don’t demand a perfect credit score. It is a stressful spot to be in, especially when the bills arrive all at once. You need a solution that works as well as your bank account does.

Finding a lender involves more than just hunting for the lowest interest rate. You have to look at how fast they move and whether an inquiry will tank your credit score. A lender in Dayton might have much different processing times than one operating out of Akron or Youngstown. Understanding these differences is the difference between solving a crisis and creating a brand new one.

  1. JetzLoan
  2. MaxCash
  3. Buckeye State Credit Union
  4. OppLoans
  5. Bridge Credit Union

Evaluating Ohio’s Short-Term Lending Options

Speed and accessibility drove our selection process for this list. When people look for these loans, they are usually facing an emergency. Being able to receive funds within 24 hours, or even the same day, is a non-negotiable metric. If you are facing an eviction notice or a utility shut-off, waiting three days is effectively the same as a denial.

We prioritized lenders that use modern digital verification to keep things moving fast. We also looked closely at how much a lender affects your credit score. Many borrowers worry that checking their eligibility will cause their FICO score to drop further. This is a legitimate fear since hard inquiries can temporarily dip your score by several points.

Lenders offering a soft credit pull or “no credit impact” checks earned higher priority. We wanted to find options that allow you to “window shop” for rates without risking your ability to get a mortgage or car loan later. Protecting your long-term financial health is just as important as getting cash today.

Lender Name Loan Amounts Funding Speed Credit Impact Check
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
MaxCash $250 – $10,000+ In minutes See site
Buckeye State Credit Union See site See site See site
OppLoans $500 – $5,000 Same-day funding available Does not affect FICO score
Bridge Credit Union See site Quicker with online signing See site

Understanding Different Loan Types in Ohio

You should know exactly what kind of debt you are signing up for before you commit to a lender. Not all “quick cash” is created equal, and the fine print can get confusing when you are under high stress. We have broken down the most common structures you will likely encounter.

Personal Installment Loans

These are typically the most stable option for short-term needs. You get a lump sum of cash upfront and pay it back in fixed monthly installments over a set period, like 12, 24, or 36 months. Because the payments are predictable, they are easy to fit into a budget.

If you use an installment loan to consolidate high-interest credit card debt, a lower fixed APR can save you a significant amount of money. It turns a chaotic pile of debts into a single, manageable monthly payment. This is a smart way to clean up your finances over time.

Title Loans

You will see these often in urban areas like Cleveland or Cincinnati. Title loans use your vehicle as collateral, which makes it much easier to get funds even with poor credit. However, the risk is extreme. If you cannot meet the repayment terms, the lender has the legal right to repossess your car.

This should be a last resort. Only consider a title loan if you have absolutely no other options and a rock-solid plan for repayment. Losing your transportation can often cost you more in the long run than the loan was worth.

Payday or Short-Term Advance Loans

These are meant for very small amounts that you plan to pay back by your next payday. While they offer immediate relief for a small grocery bill or a utility payment, they often carry much higher APRs. They work best for minor cash flow gaps rather than deep financial problems.

Using a payday loan to pay off a larger debt is a recipe for a debt cycle that is incredibly difficult to escape. It is a temporary fix that can lead to a much larger, permanent problem if you aren’t careful.

The Best Lenders for Ohio Residents

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan works as a high-speed connector between borrowers and top personal loan lenders. It is built for people who need a quick answer without the dread of a hard credit inquiry. The platform focuses on efficiency, letting you compare various local loan options in just a few minutes.

Instead of filling out ten different applications, you fill out one. The technology then matches you with the most suitable providers. This is a great choice if you need a significant amount, such as for debt consolidation or a vehicle loan, with limits up to $35,000.

This service caters to substantial financial needs rather than just small emergency cash advances. It is a powerful tool for anyone looking to consolidate several high-interest debts into a single, manageable monthly payment. (jetzloan.com)

Pros:

  • Fast funding within 24 hours.
  • No hard credit pull during the initial rate check.
  • High loan ceiling up to $35,000.

Cons:

  • The platform acts as a connector rather than a direct lender.

2. MaxCash

MaxCash – maxcash.com

MaxCash acts as a versatile one-stop shop for different financial products. Whether you need a small installment loan or a larger personal loan, the platform offers handpicked services to match your specific situation. It is designed to provide relief during stressful moments like unexpected medical bills.

The flexibility here is notable, with loan tiers ranging from a modest $250 to over $10,000. This makes it a strong contender if you need a specific, predetermined amount to cover a single bill or a series of small expenses. The interface guides you through the selection process to reduce stress.

Pros:

  • Wide range of loan amounts from $250 to $10,000+.
  • Covers various needs like title loans and installment loans.
  • Quick inquiry process.

Cons:

  • The wide variety of products can be overwhelming for some users.

3. Buckeye State Credit Union

Buckeye State Credit Union – buckeyecu.org

Buckeye State Credit Union offers a more traditional banking experience. It is ideal for those who prefer a “member-first” approach where banking feels personal. Unlike large national banks that treat you like an account number, a credit union is a member-owned cooperative. This often leads to better service.

While they offer low-rate personal loans, they are a great fit for long-term financial health. They provide various tools, including HELOCs and specialized savings accounts, to help members grow their wealth. It is a stable choice for those looking to build a relationship with a financial institution.

Pros:

  • Personalized banking services and member-focused approach.
  • Offers diverse financial products like HELOCs and investment services.
  • Focus on responsible borrowing with better rates.

Cons:

  • Requires membership and may have more stringent requirements than quick-cash lenders.

4. OppLoans

OppLoans – opploans.com

OppLoans is specifically designed for people who might have been turned down by traditional banks. Because they look beyond just a single FICO score, they can evaluate a broader range of financial data. This makes them a vital resource for Ohioans who have faced previous rejections.

The speed of this service is impressive, with same-day funding available in many cases. The application is straightforward and requires minimal documentation. Decisions often arrive within minutes of submitting the online form, which is critical when you are facing an immediate deadline.

Pros:

  • Same-day funding available for many applicants.
  • Decision-making considers more than just the credit score.
  • Applying does not affect your FICO score.

Cons:

  • Loan amounts are capped at a lower $5,000 limit.

5. Bridge Credit Union

Bridge Credit Union – bridgecu.org

Bridge Credit Union serves Central Ohio with a focus on community connection. They offer unique products like “Back-to-High” holiday loans and “Skip-A-Pay” options. These can be lifesavers during the expensive holiday seasons or when a paycheck is delayed.

They also provide share-secured loans, which can help you access funds even if your credit isn’t perfect. By using your own savings as collateral, you reduce the lender’s risk, which can lower your interest rate. Their ability to sign loans online makes things very convenient for busy people.

Pros:

  • Specialized products like Skip-A-Pay and holiday loans.
  • Share-secured loan options for those with imperfect credit.
  • Convenient online signing process.

Cons:

  • Geographically focused on Central Ohio.

Navigating the Loan Process Safely

Before you sign anything, read the fine print. Even when you are in a rush, taking five minutes to understand the total cost of borrowing can save you hundreds of dollars. A lender might advertise a “low monthly payment,” but if that payment is spread over a long period, you could end up paying double or triple what you borrowed.

Avoid the trap of taking out multiple high-interest loans to pay off previous ones. This “debt spiral” is a common mistake that leads to a permanent struggle. For example, taking a high-interest payday loan to pay a credit card bill often results in interest that is even higher than the old debt. Use these tools as a bridge, not a permanent lifestyle.

Lastly, verify the legitimacy of any lender that contacts you out of the blue. Scammers often prey on people in urgent need of cash. They might use high-pressure tactics or claim you have been “pre-approved” for a loan you never asked for. Stick to well-known platforms and never pay an upfront fee to “secure” a loan. If a lender asks for payment via gift cards or wire transfers upfront, walk away immediately.

The 5 Best Pool Financing Options for 2026: An Honest Ranking

Pool financing

The 5 Best Pool Financing Options for 2026: An Honest Ranking

Last updated: 2026-10-17

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Turning a backyard into a private oasis is a massive undertaking. It often requires much more cash than most people have sitting in a savings account. Whether you are eyeing an inground pool, a luxury saltwater system, or a high-end swim spa, securing the right capital is the first step toward that summer splash.

The financial commitment extends far beyond the initial purchase price of the unit. You have to account for excavation, plumbing, electrical work, and the surrounding hardscaping required to make the area functional and beautiful. It is a long list of expenses that can add up quickly.

Selecting a lender is not a one-size-fits-all endeavor. What works for a homeowner with a pristine credit score might be a non-starter for someone recovering from a recent financial hiccup. A borrower with a 780 FICO score might find success with a traditional bank.

A borrower with a 620 score might need to look toward specialized lenders who prioritize stability and income over a perfect credit history. This ranking focuses on finding the most reliable paths to funding your aquatic dreams. We want to ensure you don’t settle for high-interest debt that hampers your long-term financial health.

  1. Avant
  2. FastLendGo
  3. HFS Financial
  4. Acorn Finance
  5. LightStream by Truist

How These Lenders Were Evaluated for Your Backyard Project

The selection process focused on accessibility and the specific needs of pool owners. A lender that specializes in general debt consolidation might not understand the nuances of a construction-heavy project. For instance, a pool installation is often a staged process.

You might pay a deposit to the contractor, a midpoint payment after excavation, and a final payment upon completion. Lenders that provide lump-sum loans are excellent, but those that can accommodate the workflow of a contractor are even better.

We looked at credit flexibility, the ease of the application process, and the specific loan products available. A lender that offers a quick decision is worth their weight in gold when a contractor is waiting to break ground. You don’t want to lose your spot on their schedule because of a slow bank.

We also analyzed the “soft pull” capability. This is the ability for you to check your potential rate without a hard inquiry that would lower your credit score. Every option was weighed against real-world usability, looking at how these companies handle everything from the initial inquiry to the final disbursement of funds.

Comparison of Leading Pool Financing Providers

Lender Name Loan Amounts Interest Rates Credit Requirements Funding Speed
Avant See site See site See site See site
FastLendGo $500 – $5,000+ See site Bad to Great Credit See site
HFS Financial $1,000 – $450,000 From 7.80% Bad Credit Options See site
Acorn Finance Up to $100,000 From 6.99% Good & Bad Credit See site
LightStream by Truist See site See site See site See site

Ranking the Top 5 Lenders for Pool Financing

1. Avant

Avant – avant.com

Avant positions itself as a versatile player in the personal loan market. They aim to help people move forward financially by offering flexible choices that fit into a variety of life stages. Their interface is designed for those who want to keep things simple and straightforward.

This makes it ideal for the tech-savvy homeowner who wants to manage their loan from a smartphone while standing in their newly renovated backyard. It is a modern approach for a modern renovation.

This lender is particularly useful for those needing to bridge the gap between a standard credit card and a massive mortgage. If you have a small pool project, such as a high-end hot tub or a sophisticated filtration system upgrade, Avant offers a way to get the funds without the lengthy paperwork required for a home equity line of credit (HELOC).

They offer solutions that can assist with home improvement or unexpected expenses. This makes them a solid choice for various backyard upgrades ranging from small fire pits to large stone walkways.

Pros:
  • Flexible loan solutions for different financial journeys.
  • User-friendly online application process.
  • Options for debt consolidation alongside home improvement.
Cons:
  • May not offer the specialized construction-focused terms found in niche lenders.

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo acts as a bridge for those who might feel sidelined by traditional banks. They specialize in a wide spectrum of credit profiles, ranging from those with bad credit to those with great credit. It is an excellent option for quick access to cash when you need to secure a seasonal discount from a pool professional or a supplier. (fastlendgo.com)

Whether you need a small $500 emergency loan for a broken pump part or a larger sum for a motorcycle or auto repair that you’d rather not pay for with a high-interest credit card, they cover the bases. They understand that life happens.

Their ability to compare local options makes them a highly efficient partner for those in a hurry to start a project. By looking at a wide array of lenders, they can often find a match for borrowers who might have been rejected by a local credit union.

Pros:
  • Extremely wide range of loan amounts.
  • Caters specifically to bad and fair credit.
  • Fast way to compare local financing options.
Cons:
  • Interest rates for bad credit may be significantly higher.

3. HFS Financial

HFS Financial – hfsfinancial.net

HFS Financial is a heavy hitter when it comes to specialized home improvement. They focus heavily on the actual assets being installed, such as swimming pools, hot tubs, or even solar panels. Unlike general personal loan lenders, HFS understands that a $50,000 pool is an investment in your property value.

Their limits are impressive, reaching up to $450,000 for major renovations. This could include a pool, a detached pool house, and extensive landscaping. It is a serious option for a serious project.

This is the go-to option for the homeowner who isn’t just buying a pool, but is undergoing a total backyard transformation. They understand the complexity of inground pools and luxury swim spas, offering rates that start at a competitive 7.80%.

They are well-versed in the “contractor-direct” model. In this setup, the lender often works closely with the professional performing the installation to ensure funds are released upon completion of specific project milestones.

Pros:
  • Massive loan amounts for large-scale projects.
  • Specialized focus on pool and hardscape financing.
  • Inquiring about rates does not impact credit scores.
Cons:
  • The high upper limits may require stringent documentation.

4. Acorn Finance

Acorn Finance – acornfinance.com

Acorn Finance operates with a unique model that connects borrowers with contractors. This is a 100% free service for both parties, which is a breath of fresh air in the lending world. They aim to provide clarity without the typical dealer fees that often get tacked onto the end of a contractor’s quote.

By using their marketplace, you aren’t just looking for money; you are looking for the right financial fit for your specific project scope. It is about finding the right tool for the job.

They offer a high level of convenience, allowing users to check personalized rates with no credit score impact. This is ideal for someone who is still in the “dreaming and planning” phase and wants to see what is possible before committing to a specific contractor or design.

You can run the numbers for a $20,000 concrete pool shell versus a $60,000 fiberglass shell to see how the monthly payments differ without any risk to your credit profile. It is a great way to test the waters.

Pros:
  • No dealer fees for the borrower.
  • Personalized rates with no credit score impact.
  • High user satisfaction based on extensive reviews.
Cons:
  • The marketplace model means you are dealing with multiple potential lenders.

5. LightStream by Truist

LightStream by Truist – lightstream.com

LightStream by Truist is a premier option for those who want to finance their pool without tapping into their home equity. It is a streamlined, digital-first approach designed to keep the focus on the improvement rather than the debt structure. It is a clean way to handle the math.

Because these are unsecured personal loans, you don’t have to worry about your home being collateral if the project runs over budget or if you face unexpected financial hardship. Your roof stays safe while you build your oasis.

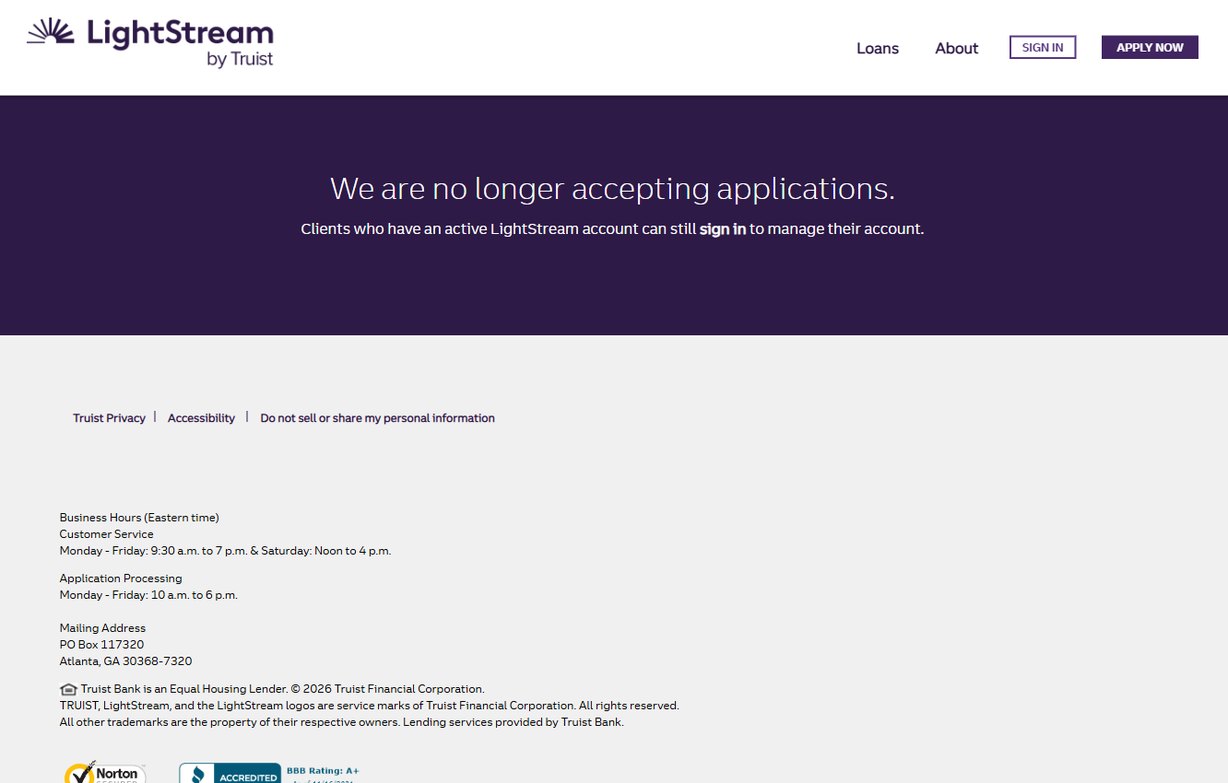
While they are currently not accepting new applications in some contexts, they remain a benchmark for how high-quality, fast-decision lending should look. For those with the right profile—typically high credit scores and steady, documented income—it is a seamless way to upgrade a home.

The speed of their approval process is often measured in hours rather than days. This makes it one of the fastest ways to move from “concept” to “construction.” You could be swimming by next month.

Pros:
  • Avoids the complexities of home equity loans.
  • Fast and easy online application process.
  • Backed by the stability of Truist.
Cons:
  • Availability of applications can be subject to change.

Understanding the True Cost of Pool Financing

Many homeowners make the mistake of focusing solely on the monthly payment. While a $150 monthly payment sounds much more manageable than a $600 payment, you must calculate the total interest paid over the life of the loan. It is a common trap.

For example, a $40,000 loan at 8% interest over 5 years results in significantly less total cost than the same loan over 10 years. If you can afford a higher monthly payment, you will save thousands of dollars in interest and build equity in your backyard much faster.

Consider these three common financial pitfalls in pool financing:

  • The “Scope Creep” Trap: A project estimated at $30,000 often ends up costing $40,000 due to unexpected rock excavation, soil issues, or upgrades to the filtration system. Always borrow slightly more than the base quote to avoid needing a second, smaller, and more expensive loan later.
  • The Interest Rate Trap: Don’t just look at the teaser rate. Check the APR (Annual Percentage Rate), which includes the interest plus any origination fees. A “low” interest rate with a 5% origination fee can actually be more expensive than a slightly higher interest rate with no fees.
  • The Fixed vs. Variable Trap: Ensure you know if your rate is fixed for the life of the loan. Variable rates might start lower but can increase if market conditions shift, potentially making your “oasis” a financial burden during an economic downturn.

Preparing Your Documentation for a Fast Approval

To ensure your pool project moves from the planning stage to the construction stage without delay, you should gather your financial documentation before you even begin the application process. Lenders want to see a clear picture of your ability to repay the debt. Having these documents ready can shave days or even weeks off the approval process.

Prepare a digital folder containing the following:

  • Proof of Income: Your two most recent pay stubs and your last two years of W-2 forms. If you are self-employed, have your most recent two years of tax returns ready, as lenders will look closely at your net income rather than gross revenue.
  • Project Estimates: At least two detailed, written quotes from reputable pool contractors. Lenders like HFS Financial or Acorn Finance may require these to verify the intended use of the funds and the legitimacy of the project.
  • Asset Statements: Recent statements for your checking and savings accounts. This demonstrates that you have the “cushion” necessary to handle the initial deposits and the ongoing maintenance costs of a pool.
  • Identification and Residency: A valid driver’s license and recent utility bills to verify your address.

By approaching pool financing with the same level of organization as you would a mortgage, you position yourself as a low-risk borrower. This not only speeds up the funding process but often results in more favorable interest rates, ultimately saving you money on your backyard transformation.

Navigating Your Path to a Backyard Oasis

Before you sign on the dotted line, it is vital to look beyond just the interest rate. You must consider the total cost of borrowing. A low monthly payment might look enticing on paper, but a longer term can mean you pay thousands more in interest over the life of the loan. This is especially critical with large-scale projects like inground pools where the principal amount is substantial.

One common mistake is failing to account for the “hidden” costs of pool ownership. Installation is just the beginning; maintenance, chemicals, electricity for pumps, and potentially a specialized insurance rider are ongoing expenses. Ensure your loan amount covers the complete project, including the liner, the deck, the landscaping, and even the initial chemical startup kit.

Failing to budget for these can lead to a beautiful pool that remains empty because you cannot afford to run the pump. It is a heartbreaking sight for any homeowner.

Always check the fine print regarding prepayment penalties. If you come into a windfall—perhaps through a work bonus or the sale of an asset—and want to pay off your pool early, you don’t want to be hit with a fee for being responsible. Comparing these details between Avant, HFS Financial, and others will save you a massive headache down the road. A smart borrower looks for flexibility: the ability to pay extra toward the principal whenever possible without being penalized for it.

The 4 Best Lenders for Uber Drivers with Bad Credit in 2026

Loans for uber drivers with bad credit

The 4 Best Lenders for Uber Drivers with Bad Credit in 2026

Last updated: 2026-10-17

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Life in the gig economy feels like a constant balancing act. One week, surge pricing is high and the money flows, then the next, a sudden transmission failure wipes out your entire profit margin. For many rideshare drivers, a dip in a credit score shouldn’t mean being locked out of the cash needed to stay on the road.

The reality of this work is unpredictable. Platform algorithms shift without warning, gas prices fluctuate daily, and high-mileage vehicles eventually demand expensive repairs. This makes your financial situation look very different from someone with a standard 9-to-5 job. You aren’t just managing a car; you’re managing a volatile, mobile business.

When you need quick financial support, you aren’t looking for perfection. You need speed. You need a lender that understands your income comes from driving miles rather than a steady bi-weekly paycheck. Traditional banks often get tripped up by this, demanding two years of tax returns and a single, verifiable employer. To a legacy bank, making $2,000 one week and $800 the next looks unstable. To a specialized gig lender, that same driver is just a high-frequency earner with a non-traditional revenue stream. This list focuses on accessibility, speed, and how well these options fit your lifestyle.

  1. JetzLoan
  2. Giggle Finance
  3. Ualett
  4. Credit Ninja

How These Rideshare Lenders Were Evaluated

We focused heavily on how fast you can get your hands on the cash. For a driver, a broken car isn’t just a nuisance; it is a total halt to your income. If your vehicle sits in a mechanic’s bay for five days while you wait for loan approval, you lose the repair cost and the seven days of earnings you would have made. We looked for services that bridge that gap between an emergency and your next platform payout.

We also prioritized lenders that don’t punish you for checking your rates. In the world of bad credit, “window shopping” for loans can actually hurt your score. Every time a lender performs a “hard pull” on your credit report, your score can drop. For someone living on the edge of a credit threshold, that small dip might be the difference between qualifying for a low-interest loan or getting rejected entirely. We sought out companies that offer transparency through soft credit pulls so you can shop around safely.

The application process itself mattered too. Drivers don’t have hours to sit at a desk filling out paperwork. We looked for lenders that offer mobile-friendly interfaces and digital document uploads. You should be able to manage your finances from the driver’s seat while waiting for your next fare.

Lender Name Max Loan Amount Funding Speed Credit Impact of Check
JetzLoan $50,000 Within 24 hours No hard credit pull
Giggle Finance $15,000 In minutes See site
Ualett See site Fast funding See site
Credit Ninja See site Same day decision No impact on score

The Top 4 Lenders for Gig Workers

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan works like a high-speed bridge when you need substantial capital fast. It is a lifesaver for drivers facing major engine work, a complete vehicle overhaul, or even a sudden need to upgrade to a newer model to meet platform standards. Because they connect you with various top lenders, they offer more variety than a single boutique lender. Instead of you applying to ten different places, JetzLoan acts as a conduit to find the best match for your specific profile.

This is a great option if you need to consolidate high-interest debt, like a credit card used for a previous repair, or if you need a significant vehicle loan. Seeing rates without a hard credit pull is a massive advantage when you are trying to rebuild your financial health. You can see potential terms upfront and decide if the monthly payment fits your weekly earnings before you ever commit to a formal application.

Pros:

  • High maximum loan amounts up to $50,000.
  • Extremely fast funding, often within 24 hours.
  • No hard credit pull means no damage to your score while checking.

Cons:

  • The matching process depends on the specific lenders in their network, meaning rates can vary significantly between matches.

2. Giggle Finance

Giggle Finance – gigglefinance.com

Giggle Finance was built specifically for the 1099 worker. They don’t just stare at a credit score; they look at the reality of a side hustle. They understand that “income” for a gig worker is a collection of deposits from Uber, Lyft, DoorDash, or Instacart rather than a single W-2 line item. This makes them a top choice for Uber drivers in a tight spot who need money almost instantly to keep working.

The speed here is hard to beat, with funding potentially arriving in just a few minutes. It is a specialized tool designed to handle the irregular income patterns that traditional banks often find too risky. If you need a new set of tires or a battery replacement right now, Giggle Finance is built to provide that liquidity before your next shift begins.

Pros:

  • Very fast funding, sometimes within minutes.
  • Tailored specifically for 1099 and self-employed workers.
  • Repeat customers can access higher limits up to $20,000.

Cons:

  • Loan amounts are lower than some major personal loan providers, making it less suitable for massive capital expenditures.

3. Ualett

Ualett – ualett.com

Ualett functions more like a cash advance than a traditional long-term loan. This is a game-changer for drivers dealing with the “ups and downs” of variable weekly earnings. It provides a cushion that aligns with how gig workers actually earn money. If you have a high-earning week but need that cash immediately to cover an insurance premium or a utility bill, Ualett helps bridge that gap.

Instead of dealing with rigid repayment schedules that are hard to meet if you take a week off for illness, Ualett offers flexibility. It is a digital-first solution for managing cash flow, making it a great companion app for those who live week-to-week. It essentially turns your future earnings into present-day liquidity.

Pros:

  • Designed specifically for the variable income of the gig economy.
  • Focuses on cash advances rather than heavy debt structures.
  • Integrated app-based experience for ease of use.

Cons:

  • May not provide the large lump sums needed for major capital investments like buying a second vehicle.

4. Credit Ninja

Credit Ninja – creditninja.com

Credit Ninja is a solid choice if you want a straightforward, online personal loan experience. If traditional banks have turned you away because of your credit history or your employment status, this service focuses on finding solutions that actually work. They act as a smart filter, running your data through various lender criteria to find the most likely “yes.”

The application is quick, often providing a decision as early as the same day. This is a practical option for covering unexpected life expenses, like a medical bill or a household repair, without a complex, multi-day approval process. It is less about the “gig” specifics and more about providing an alternative path to credit when the mainstream system fails you.

Pros:

  • Quick decision-making process, sometimes on the same day.
  • Simple and easy online application.
  • Helps drivers who cannot get approved by traditional lenders.

Cons:

  • Approval is not guaranteed and depends on specific qualifying criteria.

Strategic Financial Management for Drivers

Securing a loan is only the first step; managing that debt determines your long-term health. For gig workers, the key is to treat your vehicle and your personal finances as a single, integrated business. Here is a way to manage your liquidity:

  1. The Emergency Buffer: Try to set aside a small percentage of every “surge” payout into a separate high-yield savings account. This isn’t for daily coffee; it’s specifically for your “transmission fund.”
  2. Document Your Income: Even if you use apps, keep a secondary log of your weekly net earnings. If you ever apply for a large loan for a new vehicle, having an organized spreadsheet showing consistent monthly income can significantly improve your odds.
  3. Understand the “Total Cost of Credit”: When using cash advances, calculate the fee relative to the amount borrowed. If a $50 advance costs $5 in fees, that is a 10% cost for a very short period. Ensure the speed is worth that specific cost.
  4. Debt Snowball vs. Avalanche: If you use a loan to consolidate debt, decide if you will pay off the smallest balance first (Snowball) for momentum, or the one with the highest interest rate first (Avalanche) to save the most money.

Avoiding Common Financial Pitfalls

When you are staring at an empty bank account and a car that won’t start, it is easy to make a desperate move. Many drivers fall into the trap of predatory lending, where the speed of the money is matched by an astronomical interest rate. These lenders often target people in high-stress situations. Always check the total repayment amount before signing anything. If the total is significantly higher than what you are receiving, proceed with extreme caution.

Another mistake is failing to read the fine print on repayment. A fixed monthly payment might be easy during a busy month, but it can become a crushing weight during a slow month or if you get sick. Always look for lenders that offer some level of flexibility, such as the ability to skip a payment or adjust your schedule if your income changes.

Finally, remember that your income is your greatest asset. Even with bad credit, your ability to earn is what matters most to many modern lenders. They see the potential in your ability to drive another 20,000 miles. Keep your earnings records organized, as having proof of consistent gig work can often be the key to unlocking better rates and higher limits that traditional banks simply cannot see.

The 7 Best Lenders for Bad Credit Loans in New Jersey for 2026

Bad credit loans new jersey

The 7 Best Lenders for Bad Credit Loans in New Jersey for 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

When a sudden car repair or a medical bill hits, hitting a financial brick wall feels all too real. Many New Jersey residents find themselves in this exact spot, staring at a mounting debt they didn’t see coming. You need a lender that looks past a single credit score to see if you actually have the means to pay them back.

Whether you are stuck with a broken transmission in Newark or facing a surprise dental bill in Jersey City, the stress of a crisis often makes it hard to do your homework. You might feel rushed to sign anything just to solve the immediate problem, but that impulse can lead to much bigger headaches down the road.

Sorting through the sea of lenders requires a sharp eye and a realistic mindset. Some companies offer cash in a heartbeat but charge a premium for the speed, while traditional banks offer more stability but move much slower. This list focuses on finding a middle ground for those with poor credit who want to stay financially healthy.

There is a massive difference between a high-interest installment loan and a structured medical payment plan. Choosing the wrong one can turn a temporary setback into a lifelong cycle of debt. Use this guide to weigh your options carefully before you sign any paperwork.

  1. Max Cash
  2. FastLendGo
  3. XCEL Federal Credit Union
  4. Fulton Bank
  5. Loanz
  6. Cherry
  7. CareCredit

Evaluating Financial Options Across New Jersey

Deciding which lender actually works for your specific situation requires looking at several different metrics. Most people in an emergency care about speed above all else. If your car is your only way to get to work in a commuter state like New Jersey, waiting three days for a loan might be impossible.

However, the total cost of the money you borrow is what keeps you afloat in the long run. You have to account for interest rates and those sneaky hidden fees. A quick loan is useless if the interest rates swallow your entire paycheck every month.

We also looked at how much flexibility these lenders offer when your credit history isn’t perfect. Some provide title loans if you have no collateral, while others specialize in medical financing. This covers everything from a tiny $250 cash advance to a massive $60,000 signature loan.

We focused on whether a lender cares more about your income or your credit score. Generally, your ability to pay—your actual income and employment—is a much better predictor of whether you will stay on track than a single number on a credit report.

Lender Name Loan Amounts Funding Speed Credit Requirements
Max Cash $250 – $10,000+ Minutes Bad Credit Options
FastLendGo Small Loans Available Quick Access Bad Credit/No Credit
XCEL Federal Credit Union $500 – $60,000 See Site Secured/Unsecured
Fulton Bank See Site See Site See Site
Loanz $100 – $10,000 Quick/Convenient See Site
Cherry See Site Instant Approval High Approval Rate
CareCredit See Site Instant Decisions Subject to Credit

1. Max Cash

Max Cash – maxcash.com

Max Cash acts like a one-stop shop for various financial needs. Their products range from small $250 advances to larger loans that go over $10,000. This makes them a solid choice if you need immediate relief from an unexpected expense. A $500 loan might fix a broken appliance, while the larger options help with car or home repairs.

The platform is built for speed. They target people who need installment or title loans in just a few minutes. Because they work with people who have bad credit, they offer a lifeline that big-box banks often won’t. Just keep in mind that being fast often means you will pay a higher interest rate.

Pros:

  • Extremely fast processing for urgent needs.
  • Wide variety of loan types including title loans.
  • Accessible for those with bad credit.

Cons:

  • Title loans require collateral, risking your vehicle.

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is a flexible option for personal financing. They work with all kinds of credit tiers, whether you have good, fair, or bad credit. It is a simple way to compare local options without driving from branch to branch. (fastlendgo.com)

This lender is great for specific life events like dental work or fixing your car. If you are searching for personal loans nearby, their online model simplifies that hunt. They aggregate different profiles to help match your credit score with a provider that actually wants your application.

Pros:

  • Covers various life expenses like roof and dental repairs.
  • Options for those with no credit history.
  • Easy online comparison tool.

Cons:

  • Focus is primarily on online comparisons rather than direct banking.

3. XCEL Federal Credit Union

XCEL Federal Credit Union – xcelfcu.org

If you want more traditional stability, XCEL Federal Credit Union offers secured and signature loans. Their loan amounts can reach up to $60,000, which provides a significant cushion for big life changes. You could use these funds for debt consolidation, home upgrades, or unexpected medical bills.

As a credit union, they feel a bit more community-focused than predatory lenders. Credit unions are owned by members rather than shareholders, which often leads to more personalized service. You can choose between secured and unsecured loans to find what fits your situation. Using a savings account as collateral can often unlock much lower rates.

Pros:

  • High maximum loan amounts up to $60,000.
  • Offers secured loan options for better rates.
  • Member-focused service model.

Cons:

  • Likely requires membership or specific eligibility.

4. Fulton Bank

Fulton Bank – fultonbank.com

Fulton Bank is a major name for New Jersey residents. They have the strength of a large institution but still maintain a local feel. This makes them a solid choice for long-term banking and managing more complex financial needs over several years.

They offer everything from personal to commercial banking. They might not be the fastest choice for a $200 emergency, but they are excellent for managing significant wealth or business investments. Their stability is a big plus if you want a lender that will still be around decades from now.

Pros:

  • Highly secure and FDIC-insured.
  • Wide range of banking services from personal to commercial.
  • Strong presence in the New Jersey market.

Cons:

  • May have stricter requirements than specialized bad credit lenders.

5. Loanz

Loanz – loanz.com

Loanz focuses on helping you manage your future through specific loan solutions. With amounts between $100 and $10,000, they are great for smaller debt consolidation or upcoming costs like moving or weddings. This allows you to handle small problems before they turn into massive debts.

The main goal here is getting your life back under control. Their debt consolidation products help you manage multiple bills at once. Instead of tracking five different due dates, you can combine them into one monthly payment to simplify your budget and lower your interest stress.

Pros:

  • Low entry point for small loans starting at $100.
  • Specific products for debt consolidation.
  • Convenient digital transactions.

Cons:

  • Loan amounts are capped at a relatively modest $10,000.

6. Cherry

Cherry – withcherry.com

Cherry is a specialist in the healthcare and retail finance world. They have an impressive 90% approval rate and are used by thousands of providers. Their main goal is to let you get necessary services now and pay for them later, removing the immediate cost barrier.

The application process is incredibly fast, often taking only 35 seconds. This is a top choice for people who need dental work or home repairs immediately but want to spread out the costs. Cherry works directly through your service provider to make the process easy.

Pros:

  • Extremely fast application process.
  • High approval rate for consumers.
  • Direct integration with many healthcare providers.

Cons:

  • Limited to specific merchants and providers.

7. CareCredit

CareCredit – carecredit.com

CareCredit is a credit card built specifically for health and wellness. It is accepted at over 285,000 locations, which makes it one of the most versatile tools for medical costs. You can use it for vision, dental, or even veterinary expenses.

You can check if you prequalify without hurting your credit score. This is vital if you are worried about your standing while you shop for medical options. Many plans offer “no interest if paid in full” deals, but be careful—missing a deadline can result in retroactive interest charges.

Pros:

  • No impact on credit score during prequalification.
  • Massive network of accepted locations.
  • Flexible financing for health and wellness.

Cons:

  • Subject to credit approval and specific terms.

Understanding the Differences Between Secured and Unsecured Loans

Before you apply for anything, you need to know if a loan is secured or unsecured. This choice changes your risk level completely. A secured loan is backed by an asset, like your car, your home, or a savings account. Because the lender can take that asset if you stop paying, they are usually more willing to work with lower credit scores.

Secured loans often come with lower interest rates, but the risk to you is much higher. If you miss payments on a title loan, you could lose your vehicle. It is a trade-off between a lower rate and the risk of losing your property.

An unsecured loan isn’t backed by any physical asset. Most personal loans and credit cards fall into this category. Since the lender can’t immediately take your car if you default, they charge higher interest rates and demand better credit scores. If you fail to pay, they can’t take your house instantly, but they can sue you or garnish your wages.

How to Prepare for a Loan Application

You can increase your chances of getting approved and getting a better rate by having a plan. Following these steps helps you avoid unnecessary hits to your credit score:

  • Verify Your Documentation: Gather your recent pay stubs, bank statements, and ID before you start. If you are using an asset as collateral, have proof that you actually own it.
  • Audit Your Debt-to-Income (DTI) Ratio: Lenders look at how much of your income goes to existing debt. If that number is too high, you might get denied. Try paying down small balances before you apply.
  • Check for Errors in Your Credit Report: One wrong late payment can ruin your score. Use a free service to find and dispute mistakes before you go looking for money.
  • Compare APRs, Not Just Interest Rates: The Annual Percentage Rate (APR) includes interest and mandatory fees. This is the real cost. A 10% rate with a $500 fee might be more expensive than a 12% rate with no fees.
  • Use Prequalification Tools: Look for lenders that offer “soft pulls.” This lets you see your estimated rates without leaving a permanent mark on your credit report.

Avoiding Common Financial Pitfalls

Choosing a lender isn’t just about finding the first person to give you cash. You have to read the fine print. Many people take a high-interest loan just because they are in a rush. This can trap you in a cycle where the total interest you pay is actually higher than the money you originally borrowed.

Always look at the total cost of the loan, not just the monthly payment. A small monthly payment might hide a very long term that costs you thousands more in interest. A $5,000 loan with a $100 payment sounds great until you realize you’ll be paying it for seven years.

One mistake to avoid is applying for too many loans at once. Every application can trigger a “hard inquiry,” which lowers your score. If you apply for five loans in one week, banks will think you are desperate for cash. Use prequalification tools first to narrow your list before you make any official moves.