Best Personal Loans in Lewisville, TX: 2026 Top 5 Rankings

Personal loans in lewisville tx

Best Personal Loans in Lewisville, TX: 2026 Top 5 Rankings

Last updated: 2026-10-17

Managing money in North Texas can feel like driving through a sudden thunderstorm on I-35. One moment you are cruising along, and the next, you are scrambling to cover an unexpected car repair or a medical bill. Finding the right lender in Lewisville requires more than just a quick Google search. You have to understand how different models work, from traditional installment loans to modern peer-to-peer marketplaces.

Local residents often face a crossroads between high-interest quick cash and traditional bank loans. Choosing a lender is a deeply personal decision. It depends on your credit standing and how fast you need the funds. For instance, a borrower with a 740 FICO score has an entirely different set of doors open to them than someone working their way up from a 580.

This list focuses on accessibility, speed, and the specific needs of Texas borrowers. We have categorized options so you can match your specific situation to the right financial instrument. Whether you need a small bridge to get through the month or a large sum for a major project, there is a specific path for your needs.

  1. Texan Credit
  2. Prosper
  3. JetzLoan
  4. Giggle Finance
  5. NetCredit

Evaluating Lewisville Lending Options

The selection process for this ranking involves looking at several key performance indicators. Speed of funding is a massive factor for those facing emergencies. If a lender takes a week to process an application, they might as well be sending a carrier pigeon in this digital age. We prioritize those who offer rapid decisions and quick deposits.

In a high-speed economy, “speed” isn’t just about the approval. It is about the actual transfer of liquidity into your checking account. Loan amounts and eligibility criteria also play a huge role in determining which lender fits your life. A student looking for a small bump in cash to cover textbooks has very different needs than a general contractor needing to fund new machinery.

We analyzed how these lenders handle different credit profiles, ranging from “fair” to “excellent.” We also looked at the specific maximum amounts they provide to the public. To help you compare, we have broken down the core metrics of the top providers below. Note that “Credit Impact” refers to whether the initial inquiry used to provide you with a quote will affect your FICO score.

Lender Name Max Loan Amount Funding Speed Credit Impact
Texan Credit $1,840 30-minute response See site
Prosper $50,000 See site No impact to credit
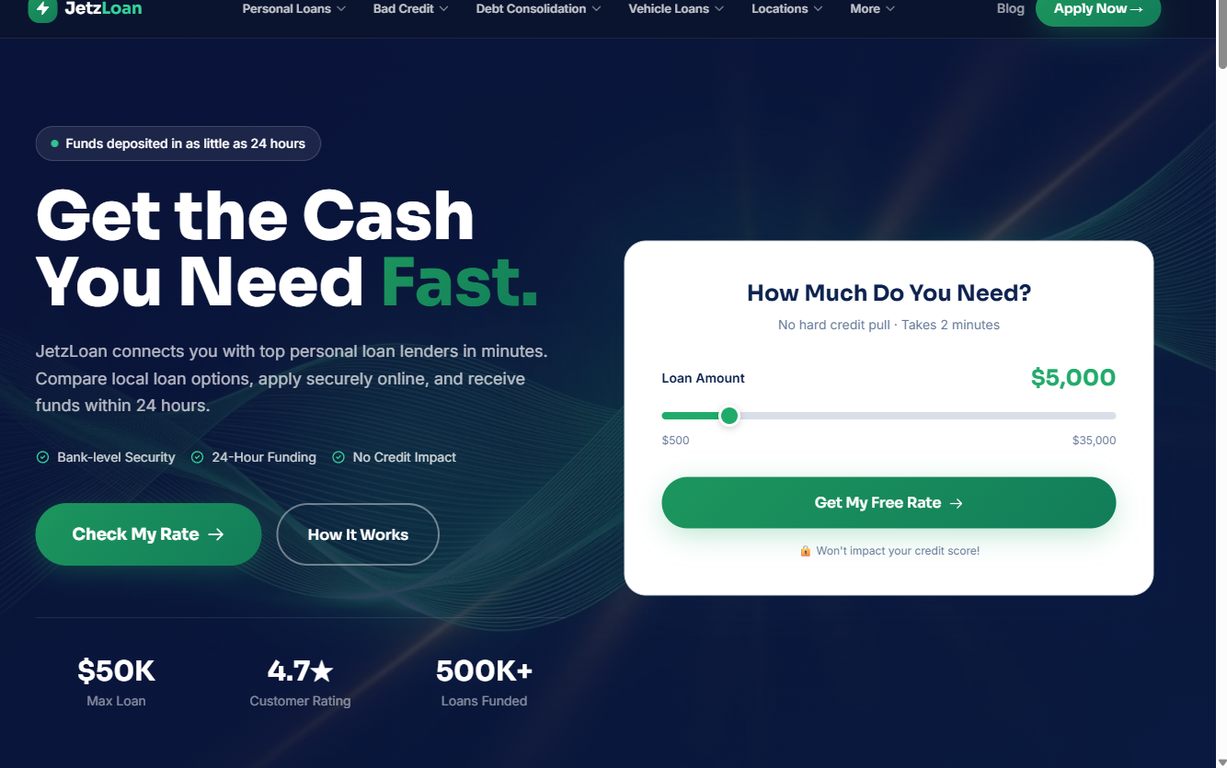
JetzLoan $50,000 As little as 24 hours No hard credit pull
Giggle Finance $15,000 Minutes See site
NetCredit $10,000 Same-day available No impact to FICO

Top Rated Lenders for Lewisville Residents

1. Texan Credit
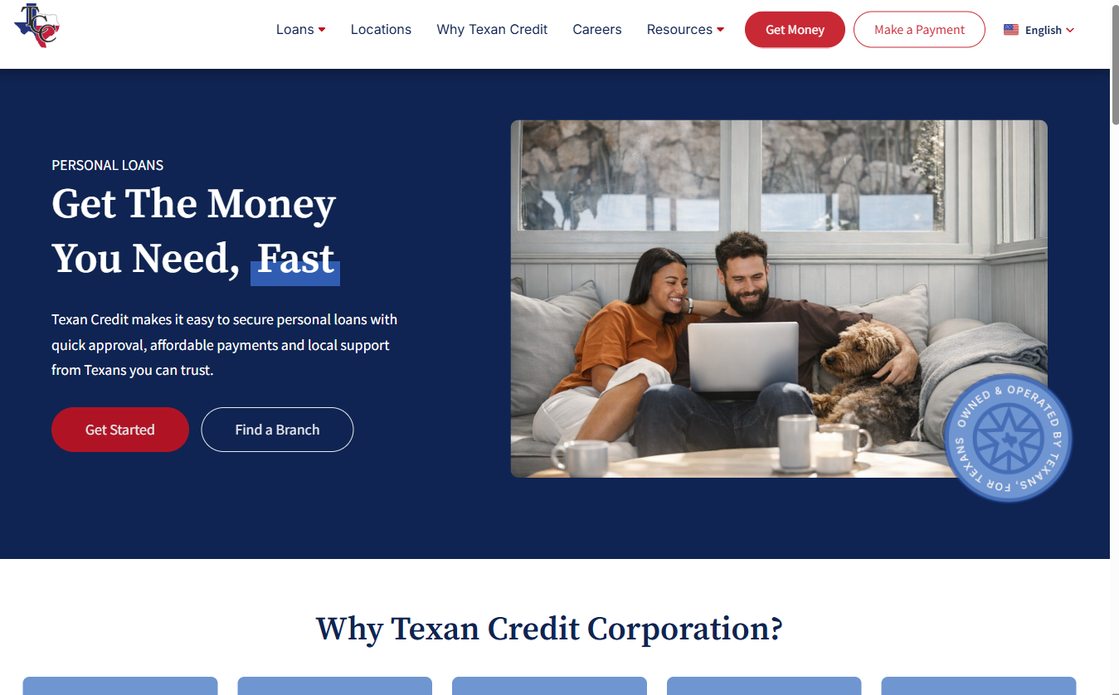
Texan Credit – texancredit.com

There is something comforting about knowing your lender is actually from the Lone Star State. Texan Credit operates with a local mindset. They offer a sense of community that many national banks lack. They specialize in smaller, manageable amounts that help bridge the gap during those tight monthly cycles.

While a massive bank might see a $1,500 request as a rounding error, Texan Credit treats it as a vital service for their neighbors. These loans are ideal for someone who needs a quick fix rather than a massive capital injection. With responses coming in as little as 30 minutes, they are built for speed and efficiency.

It is a solid choice for those who prefer working with people who understand the Texas landscape and the economic pressures facing North Texas families today. They focus on the immediate needs of the community rather than complex corporate structures.

Pros:

  • Quick 30-minute response time for online applications.
  • Local support from Texans who understand your specific needs.
  • Options for signature loans and auto-secured title loans.

Cons:

  • Maximum loan amount is capped at a relatively low $1,840.

2. Prosper
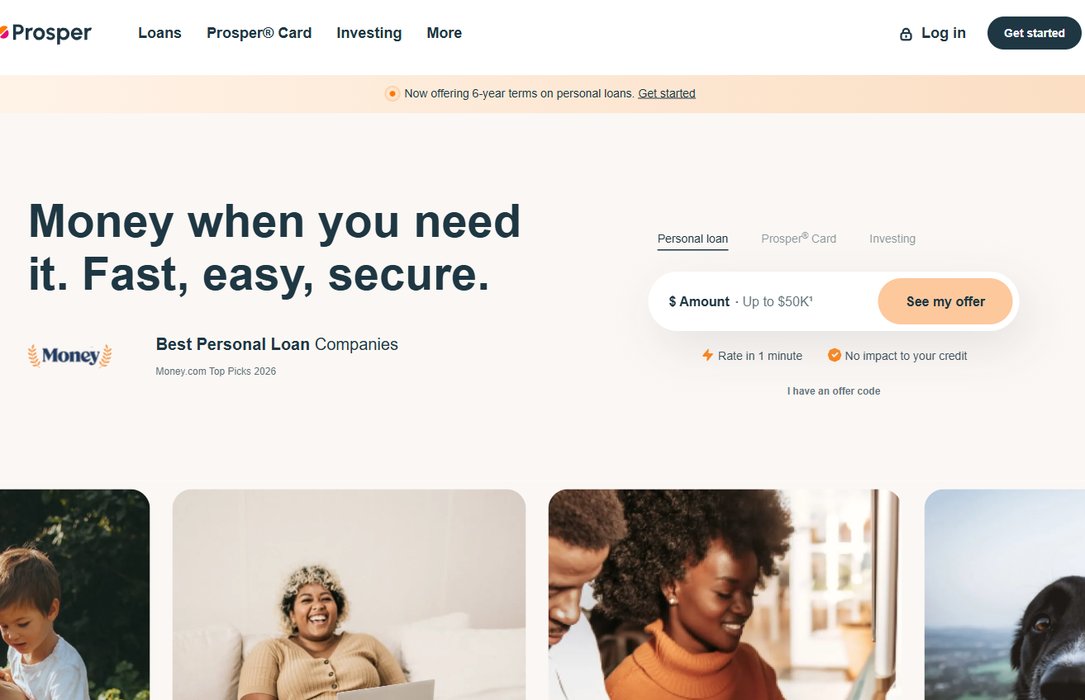
Prosper – prosper.com

Prosper operates a bit differently than your standard neighborhood bank. By using an alternate finance model, they provide a platform that connects borrowers with investors. This is known as peer-to-peer (P2P) lending. Because the money comes from individual investors rather than a central bank vault, the criteria can sometimes be more flexible.

This is particularly helpful for those looking for longer-term solutions up to 6 years. This model bypasses the heavy overhead of brick-and-mortar branches. That can translate to better terms for the borrower. If you find yourself needing a significant sum, Prosper is a heavyweight in the space.

Whether you need $2,000 or $50,000 for home renovations or debt consolidation, they can help. They offer a streamlined process that allows you to see your rate in just one minute without hurting your credit score. It is a high-tech solution for serious financial goals.

Pros:

  • High maximum loan amounts up to $50,000.
  • Check your rate in one minute with no credit impact.
  • Longer-term repayment options available for up to 6 years.

Cons:

  • Minimum loan amount starts at $2,000.

3. JetzLoan
JetzLoan – jetzloan.com

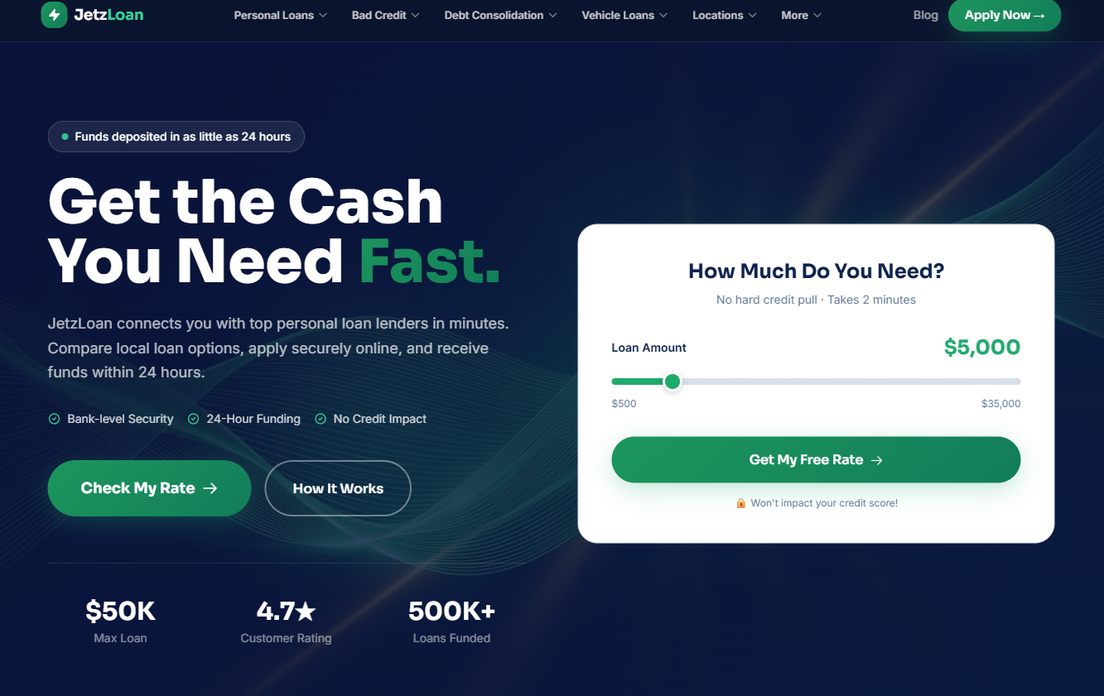
JetzLoan is designed for the person who needs cash in their pocket yesterday. Life moves fast, and sometimes your bank needs to move just as quickly. They act as a connector, linking you to top lenders in a matter of minutes through a very simple digital interface.

Instead of you spending hours calling different banks, JetzLoan does the heavy lifting of scanning the marketplace for you. The platform is particularly friendly to those who are worried about their credit score. They offer a “no hard credit pull” option, which means you can shop around for a rate without a dip in your score.

This is a critical feature for anyone currently in the process of applying for a mortgage or an auto loan. It protects your ability to qualify for those larger loans by keeping your inquiries “soft.” It is a low-risk way to explore your options without any guesswork.

Pros:

  • Funds can be deposited in as little as 24 hours.
  • No hard credit pull, so your score stays safe during inquiries.
  • High maximum limit of $50,000 for those needing significant funds.

Cons:

  • The marketplace model means you are being connected to other lenders.

4. Giggle Finance
Giggle Finance – gigglefinance.com

Small business owners and freelancers often fall through the cracks of traditional banking. Traditional lenders often want to see a steady, unchanging W-2 income. That doesn’t account for the reality of the modern workforce. Giggle Finance seems to have built their entire house around these “side hustlers” and 1099 workers.

They understand that your income might not look like a standard 9-to-5 paycheck. It might fluctuate month-to-month based on your contract load. For repeat customers, they even increase their limits. This shows a commitment to long-term relationships rather than just one-off transactions.

If you are a contractor, a rideshare driver, or a small business owner in Lewisville looking for quick capital to purchase supplies, this specialized focus can be a massive advantage. It fills a gap that many larger, more rigid institutions simply ignore.

Pros:

  • Tailored specifically for 1099 workers and small businesses.
  • Fast funding, with up to $15,000 available in just minutes.
  • Increased limits up to $20,000 for repeat customers.

Cons:

  • May not be the best fit for traditional salaried employees seeking low-interest long-term debt.

5. NetCredit
NetCredit – netcredit.com

NetCredit takes a more holistic approach to lending by looking beyond just a single number. While many lenders use a “pass/fail” system based strictly on your FICO score, NetCredit uses advanced algorithms. They want to ensure that you are treated as a human being rather than just a data point.

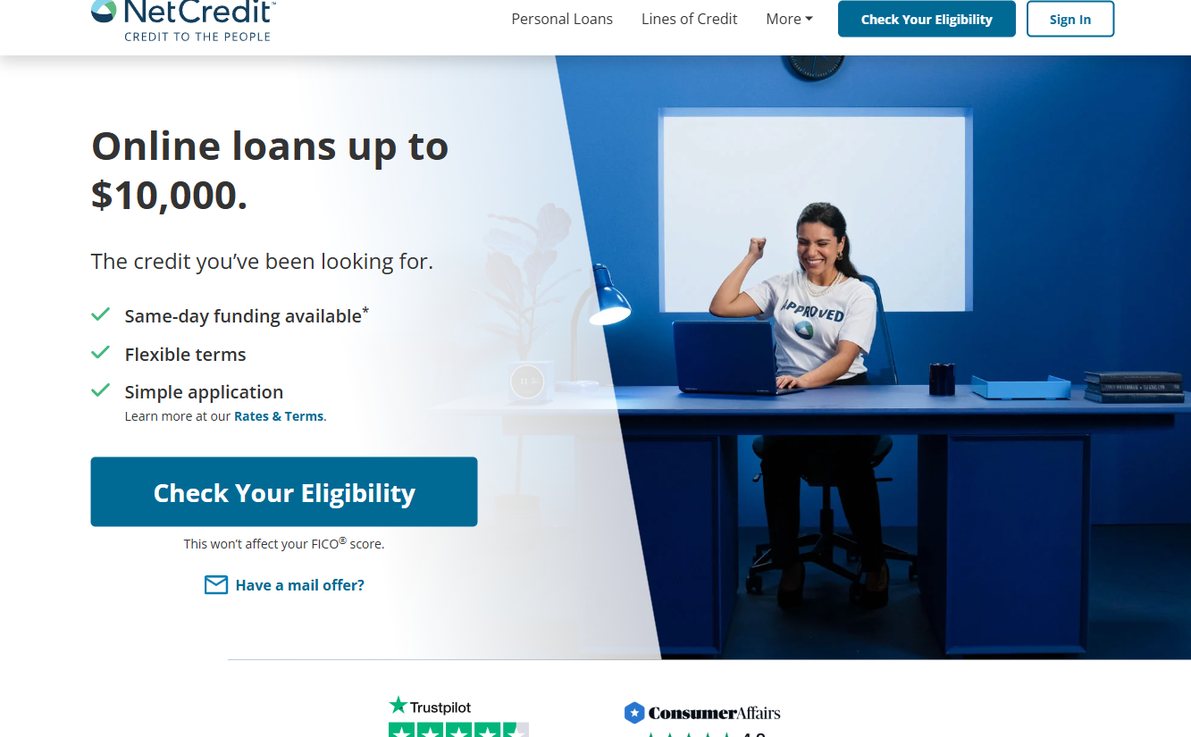
This can open doors for people with complex financial histories, such as those recovering from a past bankruptcy or a period of medical debt. They offer a variety of products, including lines of credit and personal loans up to $10,000. The ability to access same-day funding is a major plus for those in a pinch.

It provides a professional, polished experience for anyone needing a flexible financial tool. You can use it for various purposes, from emergency repairs to consolidating high-interest credit card debt. It is a versatile option for a variety of life scenarios.

Pros:

  • Same-day funding is available for many applicants.
  • Uses advanced algorithms to look beyond just the FICO score.
  • Offers both personal loans and lines of credit for flexibility.

Cons:

  • Maximum loan amount is limited to $10,000.

How to Choose the Right Loan Type

Not all loans are created equal. Selecting the wrong type can lead to unnecessary stress. When you are sitting at your computer in Lewisville, you should first determine your “Primary Objective.” This will dictate which category of lender you should approach.

If your primary objective is Emergency Liquidity—meaning you need money to fix a leaking roof—you should prioritize speed and small amounts. In this case, providers like Texan Credit or Giggle Finance are your best bet. Their approval cycles are measured in minutes or hours rather than days.

If your primary objective is Debt Consolidation or Large Purchases, you should look toward installment loans with longer terms. This is where Prosper or JetzLoan become essential. These lenders allow you to take a larger chunk of capital and spread the payments over several years. This makes the monthly impact on your budget much more manageable.

However, remember that the longer the term, the more interest you will pay over the life of the loan. Always run the numbers on the total interest paid before committing. Finally, consider the Security Requirement. Some lenders offer unsecured personal loans, meaning you don’t have to put up any collateral.

Others might require a “secured” option, such as your vehicle title. Unsecured loans are safer because they don’t put your property at risk if you default. Secured loans often offer lower rates but carry the risk of asset repossession. Knowing which one you are applying for is the first step in responsible borrowing.

Navigating Your Loan Search

Before you sign on the dotted line, take a moment to breathe and look at the fine print. One of the most common mistakes people make is ignoring the total cost of the loan. A low monthly payment might look great on paper, but if the term is too long, you could end up paying back double what you borrowed.

A $5,000 loan with a $200 monthly payment sounds affordable. But if that term lasts for 5 years at a high interest rate, you are essentially paying for the car you bought twice over. Always check the interest rates and any potential fees for early repayment. Some lenders might charge you a penalty if you try to pay them back ahead of schedule.

This is known as a “prepayment penalty.” While it seems counterintuitive, lenders use these fees to protect their projected interest earnings. Knowledge is your best defense against high-interest debt traps. Finally, remember that your credit score is a living thing. Every time you apply for a loan, be mindful of how many inquiries you have in a short period.
Top 5 Lenders for Personal Loans in Connecticut: 2026 Rankings

Personal loans in connecticut

Top 5 Lenders for Personal Loans in Connecticut: 2026 Rankings

Last updated: 2026-10-16

Finding a financial partner in the Nutmeg State often feels like walking through a dense forest without a compass. You might be staring down an unexpected car repair in Hartford or a sudden medical bill in New Haven. Perhaps Bridgeport’s rising utility costs are squeezing your monthly budget.

The lending market is massive and frequently confusing. This list cuts through that noise for Connecticut residents looking for quick capital. We have laid out a roadmap through the different tiers of credit products available right here in our state.

No single lender is a magic fix for every problem. What helps a student in Storrs buy textbooks might be useless to a Greenwich homeowner needing a new roof. You have to weigh interest rates against your specific credit profile carefully.

A low APR often requires a high FICO score to unlock. On the flip side, lenders that accept lower scores usually charge much higher interest to cover their risk. Knowing where you sit in that spectrum is the first step to making a smart move.

  1. Max Cash
  2. FastLendGo
  3. American Eagle Financial Credit Union
  4. Upgrade
  5. Best Egg

How Connecticut Lenders Were Evaluated

We weighed several factors to ensure these rankings actually help local borrowers. Speed is a massive priority because most people seeking personal loans are dealing with emergencies. A lender that drags their feet for weeks is useless when a medical bill is due tomorrow.

If your car is sitting in a repair shop waiting for parts, you need answers quickly. We also looked at credit flexibility. This means checking how providers treat everyone from people with pristine scores to those struggling with bad credit.

The goal was to find companies offering transparent terms and significant loan amounts. We looked specifically at how these lenders respect Connecticut consumer protection laws. We want to make sure they operate within ethical boundaries for their customers.

Finally, we looked at the actual application experience. This involves how easy the digital interface is and whether the disclosures are clear. A lender that hides fees in a massive PDF is much harder to trust than one that shows the total cost upfront.

Lender Name Loan Amounts Credit Requirements Key Features
Max Cash $250 – $10,000+ Bad Credit Friendly Fast inquiries and title options
FastLendGo See site Bad Credit to Great Credit Specialized loans (Auto, Dental, Roof)
American Eagle Financial Credit Union See site Secured Loan options Credit building focus
Upgrade Up to $50,000 See site Fast funding and fixed rates
Best Egg Up to $50,000 See site BBB A+ rated; debt consolidation

Ranking of Top Lenders for Connecticut Residents

1. Max Cash

Max Cash – maxcash.com

Max Cash works well for anyone needing financial relief on a very tight timeline. They offer a wide variety of products, including installment loans and title loans. This makes them a strong option for people with diverse financial needs.

If you need a quick bridge between paychecks, this is a solid choice. They are particularly helpful when traditional bank hours or strict credit rules get in the way. They serve those who might struggle to find support in the standard Connecticut banking market.

Since they offer amounts from $250 up to over $10,000, they can scale to your crisis. You might need $500 for a leaking pipe or $3,000 to pay off a high-interest payday loan. Max Cash lets you target that specific amount instead of forcing a massive loan on you.

Pros:
  • Wide range of loan amounts from $250 to $10,000+
  • Options for title loans and installment loans
  • Fast, personalized loan inquiries
Cons:
  • High-interest options may be present in certain products

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo focuses on making personal financing accessible to almost everyone. They cater to the whole market, from people with great credit to those needing emergency funds despite bad credit. Their workflow is digital-first to keep wait times low.

Their specialized loan categories are what really stand out. You can find financing specifically for auto repairs, dental work, or roofing. This niche approach is great if you want funds intended for a specific, pressing purpose rather than a generic loan.

Imagine you live in West Hartford and have a dental emergency. Using FastLendGo‘s specialized structure ensures the loan purpose matches the funds’ intended use. This can sometimes make the approval process feel much more streamlined.

Pros:
  • Covers a vast range of credit scores
  • Specialized financing for specific needs like dental or auto
  • Quick comparison of local options
Cons:
  • The variety of products can be overwhelming for some users

3. American Eagle Financial Credit Union

American Eagle Financial Credit Union – aeau.org

If you want to play the long game, American Eagle Financial Credit Union offers a different path. They focus on secured loans, which are excellent for rebuilding your credit score. These loans use an asset like a car or savings account as collateral.

Using collateral reduces the lender’s risk. Because of that, you can often get much better terms. This is a smart move for anyone who has a clear plan to improve their financial standing over time.

You are essentially building a foundation for much larger loans later. As you make consistent, on-time payments, your credit report improves. This makes qualifying for a mortgage much easier down the road. It is a steady climb toward better financial health.

Pros:
  • Excellent for credit score improvement
  • Secured loan options available
  • Professional credit union structure
Cons:
  • Requires collateral for secured loan products

4. Upgrade

Upgrade – upgrade.com

Upgrade is a heavy hitter for those needing larger sums for major life changes. With limits reaching up to $50,000, they are a top choice for debt consolidation or home improvements. Their platform is sleek and very user-friendly.

You can see rates without hurting your credit score because they use soft credit pulls. This lets you shop around digitally without seeing a sudden drop in your FICO score. It takes the fear out of comparing different offers.

They also provide tools like rewards checking and savings accounts. This makes them a broader financial partner. If you want to turn three high-interest credit card balances into one single monthly payment, Upgrade is a strong contender.

Pros:
  • High loan limits up to $50,000
  • No impact to credit score when checking rates
  • Fast funding and fixed interest rates
Cons:
  • May require higher credit tiers for the best rates

5. Best Egg

Best Egg – bestegg.com

Best Egg has built a reputation for being a reliable option for debt consolidation. They hold an A+ rating from the Better Business Bureau, which brings a level of trust to the digital lending space. They focus on predictable products.

This lender is a great fit if you want to simplify multiple monthly payments into one manageable chunk. Their process is designed to be hassle-free. They use your info to find the best options from their network quickly.

If you are currently juggling various debts from different creditors, Best Egg’s model can provide clarity. It helps you regain control of your budget without the stress of managing multiple different due dates every month.

Pros:
  • Highly rated by customers and BBB
  • Up to $50,000 in hassle-free funds
  • Strong focus on debt consolidation
Cons:
  • Application process requires significant personal information

How to Choose the Right Loan: A Step-by-Step Guide

Applying for a loan can feel daunting if you don’t have a plan. Follow these steps to make an informed decision that helps your long-term financial health:

  1. Identify your exact need: Determine if you need a small amount for an emergency, like a $500 car repair, or a large amount for restructuring, like $15,000 for credit cards. This tells you whether to look at Max Cash or Upgrade.
  2. Check your credit score: You don’t need a perfect score, but knowing your number helps you target the right lenders. If your score is under 580, look for “bad credit friendly” lenders or secured loans from credit unions.
  3. Compare APRs, not just monthly payments: The Annual Percentage Rate (APR) includes interest and mandatory fees. A $100 monthly payment might look cheaper than $120, but a higher APR could cost you thousands more over the life of the loan.
  4. Read the repayment terms: Make sure the monthly payment fits your budget comfortably. A payment that is too tight leaves no room for error, leading to late fees and credit damage.

Avoiding Common Pitfalls in Connecticut

Always look closely at the fine print regarding the total cost of borrowing before you sign anything. A low monthly payment sounds tempting, but a long term could mean you pay back double what you borrowed. Always do the math.

Multiply your monthly payment by the number of months in the term, then subtract the principal. This tells you the total interest. Never let a shiny marketing offer hide the actual cost of the debt you are taking on.

Rushing into a high-interest loan just because it is fast is another common mistake. A quick cash advance might solve a midnight emergency, but it can start a cycle of debt that is incredibly hard to break. This is especially risky with payday-style products.

Always try to compare at least two different offers before committing your financial future. Finally, watch your credit score. While checking rates via a soft inquiry is safe, a formal application triggers a hard inquiry. This causes a temporary dip, so be sure you are certain before you hit that final button.

The 7 Best Lenders for Bad Credit Loans in Iowa for 2026

Bad credit loans iowa

The 7 Best Lenders for Bad Credit Loans in Iowa for 2026

Last updated: 2026-10-17

Trying to manage money in Iowa can feel like driving through a cornfield in a thunderstorm when your credit score is stuck in the mud. Life happens. An unexpected car repair can leave you stranded, or a sudden hospital bill can demand cash you simply don’t have. When your credit report looks less than perfect, traditional banks often feel like they have shut their doors right when you need them most.

Finding a lender that looks at more than just a single number is the best way to escape the cycle of high-interest debt. A credit score is just a snapshot of your past. It doesn’t tell the whole story of your current income or your commitment to paying someone back. You need a lender that offers a way forward, not just a temporary fix that leaves you in a worse spot later.

  1. GICU
  2. JetzLoan
  3. FSB
  4. MaxCash
  5. Financial Plus Credit Union
  6. Bank Iowa
  7. LPI Loans

Evaluating Iowa Lenders for Imperfect Credit

We looked closely at how these institutions treat people with non-traditional credit histories. It isn’t just about who says yes to the application. It is about how they structure the repayment plans. You don’t want a lender that gives you a big lump sum but then hits you with a massive balloon payment at the end. That kind of setup usually leads to a second financial crisis when that final bill arrives.

We prioritized lenders that use predictable, amortized repayment schedules. We also looked for speed and the chance to rebuild your score. Getting cash fast is great for an emergency, but a lender that helps you improve your credit is worth much more in the long run. We checked if they report your on-time payments to Equifax, Experian, and TransUnion. That is the most effective way to turn a loan into a tool for better credit.

The following table breaks down how these lenders compare on the basics like loan amounts and speed.

Lender Name Max Loan Amount Funding Speed Credit Building Focus
GICU see site see site see site
JetzLoan $35,000 24 hours see site
FSB see site see site see site
MaxCash $10,000+ Minutes see site
Financial Plus Credit Union see site see site see site
Bank Iowa see site see site see site
LPI Loans see site see site see site

1. GICU

GICU – gicu.org

Greater Iowa Credit Union is a great fit if you want a community-focused approach. They offer personal loans for people with low credit, giving you a way to get funds while working toward better financial health. Big national banks often rely on rigid algorithms, but credit unions are member-owned. This means they might actually look at your history and your character rather than just a number on a screen.

This is a good choice if you want a local feel. They even offer member benefits like discounts at local theme parks. It is a more human way to bank, treating you like a neighbor instead of just an account number. If you are trying to fix your credit, their counseling resources can help you move toward better loan terms in the future.

Pros:

  • Offers personal loans specifically for low credit situations.
  • Member benefits include discounts at Adventureland.
  • Provides various resources for saving and borrowing.

Cons:

  • Member eligibility is required to access specific perks.

2. JetzLoan

JetzLoan – jetzloan.com

If the clock is ticking, JetzLoan works like a fast-moving relief valve. They focus on speed, connecting you with lenders in just a few minutes through a simple online application. It is a lifesaver if you don’t have time to drive to a bank branch or wait days for someone to manually review your paperwork.

The platform is excellent if you are worried about your credit score dropping. They offer a “no credit impact” check, so you can see your rates without worrying about a rejection hurting your standing. This pre-qualification stage lets you shop around and compare offers without the risk of multiple hard inquiries. It is a smart way to shop when you’re on a tight budget.

Pros:

  • Funding can arrive in as little as 24 hours.
  • No hard credit pull to check rates.
  • High maximum loan amount of up to $35,000.

Cons:

  • The service acts as a connector rather than a direct lender.

3. FSB

FSB – myfsbonline.com

Farmers State Bank uses a more nuanced approach to lending in Eastern Iowa. They know a credit score is only one piece of the puzzle. They look at the person behind the paperwork. If your score is low because of a medical bill or a temporary job loss that is already fixed, FSB might care more about your steady income than a single bad month.

This makes them a strong option for people who have had setbacks but have a stable job. They offer a traditional banking experience where you can actually talk to someone. Working with a local institution like FSB is helpful if you need to explain a specific situation to a loan officer who won’t just look at an automated rejection.

Pros:

  • Considers factors beyond just the credit score.
  • Strong presence in the Eastern Iowa region.
  • Provides secure online banking and services.

Cons:

  • May have stricter requirements than specialized online lenders.

4. MaxCash

MaxCash – maxcash.com

MaxCash is the right call if you need cash almost instantly. They handle several products, including title loans and installment loans. This variety is useful because different emergencies need different tools. A car title loan might be the fastest way to fix a vehicle, while an installment loan might be better for paying off old credit card debt.

Their system is built for speed. They aim to get you connected to funds through a secure online process. It is designed for those who need a quick injection of cash for an emergency. Since it is all digital, you can finish the application on your smartphone while you’re on the go.

Pros:

  • Extremely fast processing for emergency loans.
  • Wide variety of loan types available.
  • Secure, encrypted online application process.

Cons:

  • High variety of products can lead to complex terms.

5. Financial Plus Credit Union

Financial Plus Credit Union – financialpluscu.com

Financial Plus Credit Union is a major player. Forbes even named them a Best-in-State Credit Union for 2026. They offer unsecured personal signature loans with no prepayment penalties. That is a big deal. If you pay your loan off early, you won’t be charged a fee, which saves you a lot of money on interest.

Their loans can help with emergencies and offer flexible terms up to 48 months. This flexibility lets you manage your debt without worrying about being penalized for paying it off early. If you expect your finances to get better soon, this is a great way to accelerate your repayment without extra costs.

Pros:

  • Award-winning service and stability.
  • No prepayment penalties on signature loans.
  • Flexible terms up to 48 months.

Cons:

  • Credit union membership requirements may apply.

6. Bank Iowa

Bank Iowa – bankiowa.bank

Bank Iowa mixes high-tech banking with a hometown feel. They offer personal loans with simple terms and fast access to cash. This makes them a reliable choice if you want a straightforward experience. Their digital platform is easy to use, which helps when you are already stressed about money.

They focus on the community and long-term wellness. They help kids start savings accounts and provide flexible consumer loans. It is a solid choice for a stable, long-term banking partner. Choosing a lender that cares about your overall financial health helps you build wealth instead of just managing debt.

Pros:

  • Simple terms and fast access to funds.
  • Strong focus on community and local service.
  • Diverse range of banking products.

Cons:

  • May require traditional banking documentation.

7. LPI Loans

LPI Loans – lpiloans.com

LPI Loans focuses heavily on credit building. They specialize in installment loans for people with imperfect credit who want to fix their reputation. These loans help you demonstrate that you can manage credit responsibly. Eventually, that can lead to getting much lower interest rates from traditional banks.

They aren’t like predatory payday lenders. Instead of astronomical interest rates that make it impossible to pay back, LPI offers manageable installments. They take on the smaller loans that big banks often turn away. This makes them a vital stepping stone for people currently stuck in a “credit desert.”

Pros:

  • Specifically designed for credit rebuilding.
  • Predictable installment payments.
  • Serves those who are often rejected by large banks.

Cons:

  • Focuses on smaller, specific loan niches.

Key Differences: Credit Unions vs. Online Lenders

When deciding where to apply, you should understand the difference between a Credit Union (like GICU or Financial Plus) and an online lender (like JetzLoan or MaxCash). This choice changes how much flexibility you have during the application process.

Feature Credit Unions Online/Specialized Lenders
Approval Criteria Holistic (income, character, local ties) Primarily score and automated data
Interest Rates Generally lower due to non-profit status Varies widely; can be higher for speed
Speed Can take several days for manual review Often instant or within 24 hours
Membership Often requires being a resident or member Generally open to anyone meeting criteria

If you want long-term health and the lowest interest rates, go with a credit union. However, if you have a real emergency and every hour counts, a specialized online lender might be your only option to bridge the gap.

Navigating the Borrowing Process

Don’t choose a lender on a whim. You must read the fine print about interest rates and the Annual Percentage Rate (APR). The APR is more accurate because it includes both the interest and any mandatory fees. A loan that looks easy today can become a mountain of debt if the interest compounds aggressively.

Before you sign anything, ask these questions:

  • Is there a prepayment penalty if I pay this off early?
  • Does this lender report my payments to the credit bureaus?
  • What is the exact APR, including all fees?
  • What happens if I miss a payment—is there a grace period?

Try to avoid taking out multiple loans at once. This can create a debt spiral where you borrow from one place just to pay another. That only makes your total debt grow. If you are consolidating debt, make sure the new interest rate is much lower than the old one. Otherwise, you are just moving the problem around.

Always check if a lender is legitimate. Scams are common in this space. Never give sensitive info to someone who promises “guaranteed approval” without a real review. Real lenders want to make sure you can actually pay them back. If a lender asks for a “down payment” or “insurance fee” via gift cards or wire transfers, walk away immediately. That is a scam.

The 5 Best Lenders for Bad Credit Loans in Maryland for 2026

Bad credit loans maryland

The 5 Best Lenders for Bad Credit Loans in Maryland for 2026

Last updated: 2026-10-17

Navigating the financial landscape in Maryland can feel like trying to walk through a thick fog without a flashlight. When a sudden car repair, an unexpected medical bill, or a home maintenance emergency lands on your doorstep, the pressure mounts instantly. Many residents find themselves searching for a lifeline when their credit score doesn’t reflect their true reliability or character—perhaps due to a past period of unemployment, a medical crisis, or simply the rising costs of living in the Baltimore-Washington corridor.

Finding the right lender requires more than just a quick search on a mobile device. It involves weighing speed against cost, understanding the difference between secured and unsecured debt, and identifying which institutions prioritize your actual situation over a mere three-digit number. Whether you are navigating the suburbs of Montgomery County or the urban centers like Baltimore, understanding the nuances of the lending market is essential to maintaining financial stability.

This list highlights options specifically suited for those facing hurdles in the Old Line State, providing a starting point for anyone needing to bridge a temporary gap in their budget.

  1. FastLendGo
  2. MaxCash
  3. LendingPoint
  4. OppLoans
  5. SECU

How Maryland Lenders Were Evaluated

Selecting these providers involved a deep dive into their specific offerings for Maryland residents. The focus remained on accessibility for those with subprime or poor credit scores, ensuring that the lenders listed were not just available, but actually useful to those in a high-stress financial position. It is not just about getting cash; it is about finding a path that does not lead to a deeper debt trap through predatory interest rates or hidden fees.

Each entry was scrutinized based on several critical metrics:

  • Stated Loan Amounts: We looked for a range that accommodates both small, immediate needs (like a $300 utility bill) and larger structural needs (like $15,000 for debt consolidation).
  • Speed of Funding: In an emergency, time is of the essence. We evaluated whether a lender provides instant decisions, same-day funding, or a multi-day waiting period.
  • Transparency and Requirements: We looked for clarity in their processes to ensure that what you see on the screen matches the reality of the loan agreement when it comes time to sign.
  • Credit Impact: We prioritized lenders that offer “soft pull” inquiries for initial quotes, allowing you to shop around without further damaging your FICO score.
Lender Name Loan Amounts Funding Speed Credit Requirements
FastLendGo $500 – $5,000+ Fast access Bad/Fair/Good Credit
MaxCash $250 – $10,000+ Minutes Bad Credit Loans
LendingPoint $1,000 – $36,500 Fast decision See site
OppLoans See site Same-day funding available Does not affect FICO score
SECU $300 – $30,000 See site Unsecured Signature Loans

Understanding Loan Types: Secured vs. Unsecured

Before choosing a lender from the list below, it is vital to understand the mechanism of the loan you are requesting. In Maryland, lenders typically offer two primary structures: secured and unsecured loans. This distinction can be the difference between a manageable debt and a significant loss of assets.

Unsecured Loans

SECU – secumd.org

An unsecured loan is not backed by any collateral. When you take out an unsecured personal loan—such as many of the options offered by LendingPoint or SECU—the lender is relying solely on your promise to pay them back. Because there is no asset for the lender to seize if you default, these loans often require a more thorough review of your income and banking history. If you have a steady paycheck but a low credit score, an unsecured loan is often the safest way to borrow without risking your property.

Secured Loans

A secured loan is backed by an asset, often referred to as collateral. For example, if you use a title loan (a product mentioned in the MaxCash section), your vehicle serves as the guarantee for the debt. If you are unable to repay the loan, the lender has the legal right to seize the vehicle to recoup their losses. While secured loans are often easier to obtain for those with very poor credit because the lender’s risk is lower, they carry a much higher personal risk if your financial circumstances do not improve.

Top Maryland Lenders for Challenging Credit

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo acts as a bridge for those who need a quick way to compare various local personal loan options. It is designed for people who need to move fast, whether that means covering an emergency auto repair or handling a sudden dental expense that cannot wait for the next pay cycle. The platform focuses on speed and simplicity for the borrower, reducing the bureaucratic friction often found in large national banks. (fastlendgo.com)

This provider is particularly useful for those who need specific amounts, ranging from small $500 injections to larger $5,000 personal loans. They cater to a wide spectrum of credit profiles, making them a versatile choice for Marylanders in a pinch. Because they act as a conduit to various options, they can often find a match that a traditional bank might overlook.

Pros:

  • Offers various loan purposes including auto and dental.
  • Covers a wide range of credit levels from bad to great.
  • Quick access to compare local options.

Cons:

  • Does not specify exact interest rates in the overview.

2. MaxCash

MaxCash – maxcash.com

MaxCash positions itself as more than just a lender; it aims to be a source of relief. For residents in Maryland dealing with urgent needs, such as a utility shut-off notice or an immediate repair, this service provides a way to access installment or title loans in a matter of minutes. It is built for speed and immediate financial relief, making it a high-velocity option for urgent cash flow gaps.

The flexibility in loan amounts is a standout feature, starting as low as $250 and scaling up to over $10,000. This makes it a “one-stop shop” for various financial products. If you need a quick cash advance to bridge the gap until payday, this is a primary contender for those who need liquidity instantly rather than waiting for a multi-day bank transfer.

Pros:

  • Extremely fast processing, sometimes in minutes.
  • High maximum loan amounts for title loans.
  • Multiple loan types available.

Cons:

  • Title loans involve using your vehicle as collateral.

3. LendingPoint

LendingPoint – lendingpoint.com

LendingPoint focuses on unlocking possibilities for people who need more significant capital. With loan amounts reaching up to $36,500, this is a robust option for those looking at debt consolidation or major home improvements. If you have several high-interest credit card balances that are draining your monthly income, a single larger loan from a provider like this can be a strategic tool for long-term financial restructuring.

The process is designed to be easy, allowing users to check their rates without impacting their credit score. This “soft pull” approach is a lifesaver for those trying to shop around without making their credit situation look even worse. It is ideal for those with specific, larger financial goals who need a professional, streamlined digital experience.

Pros:

  • High loan ceiling for significant expenses.
  • Checking rates does not affect credit score.
  • Wide variety of loan purposes.

Cons:

  • May require a higher credit tier than specialized bad credit lenders.

4. OppLoans

OppLoans – opploans.com

OppLoans is built around the idea that your credit score doesn’t tell the whole story. By working with bank partners, they offer personal loans designed to fit unique needs, even if you have been turned down elsewhere due to a recent dip in your score. It is a supportive option for those who feel overlooked by traditional banks that rely heavily on automated, rigid scoring models.

One of the most significant advantages here is the potential for same-day funding. If you are facing an immediate crisis—such as a broken furnace in the middle of a Maryland winter—the ability to get money in your account the same business day is a game-changer. The application process is streamlined to be quick and easy, requiring minimal documentation to get started.

Pros:

  • Same-day funding available for approved applicants.
  • Does not affect FICO score during application.
  • No hidden fees in the advertised process.

Cons:

  • Approval is based on more than just credit, which can be unpredictable.

5. SECU

SECU stands as Maryland’s largest state-chartered credit union, offering a more traditional, community-focused banking experience. Their unsecured signature loans are a solid choice for those who want to build a long-term relationship with a financial institution. As a member-owned entity, SECU often provides a level of service and community alignment that national banks simply cannot match.

They offer loans ranging from $300 up to $30,000 with no application or prepayment penalties. This flexibility is vital; if you receive a tax refund or a work bonus, you can pay off your SECU loan early without being punished with extra interest—a common tactic used by other lenders. It is a refreshing change for those used to the predatory terms and “early repayment penalties” of some high-interest lenders.

Pros:

  • No application or prepayment penalties.
  • High maximum loan amounts for an unsecured product.
  • Strong community presence in Maryland.

Cons:

  • Credit union membership requirements may apply.

Navigating Your Borrowing Choices

Choosing a lender is not a decision to be made in a vacuum. Before signing any paperwork, you must look closely at the fine print. It is easy to get caught up in the excitement of a quick approval, but the cost of that speed can be steep if you do not perform the necessary due diligence.

Avoid the mistake of only looking at the monthly payment. A low monthly payment often means a much longer term, which results in you paying significantly more interest over the life of the loan. For example, a $2,000 loan with a $100 monthly payment over 36 months is far more expensive than a $2,000 loan with a $200 monthly payment over 12 months. Always calculate the total cost of the loan—the sum of all your payments—before you commit your signature.

Another common pitfall is failing to compare the lender’s reputation with your specific needs. If you need money today to prevent an eviction, a credit union might be too slow, even if they have better rates. Conversely, if you need $20,000 to consolidate your debts and lower your interest burden, a small cash advance lender won’t be able to help you reach that goal and may actually make your situation worse.

Lastly, remember that “guaranteed approval” is a myth in the lending world. Legitimate lenders must assess your ability to repay to comply with consumer protection laws. Anyone claiming they cannot say no is likely a red flag for a scam or a predatory lender. Stick to reputable providers that clearly outline their criteria and respect your financial well-being as you navigate through difficult times.

Top 5 Lenders for RV Loans for Bad Credit in 2026

Rv loans for bad credit

Top 5 Lenders for RV Loans for Bad Credit in 2026

Last updated: 2026-10-17

Getting the keys to a new motorhome shouldn’t feel like climbing a mountain of paperwork. For many travelers, a bruised credit score acts as a heavy anchor, preventing them from chasing the sunset in a comfortable fifth wheel or a cozy camper van. Whether you are looking to upgrade from a small pop-up to a full-sized Class A motorhome or you are simply trying to secure your first teardrop trailer, the financial hurdle can seem insurmountable without a clear roadmap.

The goal is to find a lender that looks past a single number and sees a real person. Choosing the right financing requires balancing interest rates against the speed of approval to ensure your camping season isn’t lost to bureaucracy. A delay in funding doesn’t just mean more time in the bank; it means missing out on that specific, well-maintained used RV that someone else is currently driving away with.

  1. My Financing USA
  2. FastLendGo
  3. Alliant Credit Union
  4. U.S. Bank
  5. Solarity Credit Union

Evaluating the Top Financing Options

The comparison process focused on several critical pillars of lending. Since many travelers need to move quickly, the speed of the approval process was a primary metric. Waiting weeks for a decision can mean losing a used RV to another buyer. In a competitive market, the “first to show proof of funds” often wins the deal, making lenders with rapid decision-making capabilities essential for successful shopping.

Accessibility for non-traditional credit profiles was also essential. This ranking prioritizes lenders that offer pathways for those with scores in the lower ranges, ensuring that the “bad credit” category is addressed with genuine, actionable options. We looked at how these lenders handle documentation, how they treat unconventional income like seasonal work or freelance earnings, and whether they specialize in recreational vehicle titles or general personal loans.

Lender Name Loan Amounts Credit Requirements Key Feature
My Financing USA $10,000+ 550 Minimum Score Nationwide search
FastLendGo See site Bad Credit Options Personal loan focus
Alliant Credit Union See site Credit Union Rates Same-day approval
U.S. Bank See site Pre-approval available Digital pre-approval
Solarity Credit Union See site See site NCUA Insured

1. My Financing USA

My Financing USA – myfinancingusa.com

Navigating the waters of financing can be tricky when your credit history isn’t pristine. My Financing USA searches nationwide to find programs specifically designed for those with less-than-perfect scores. It is a specialized approach for the road ahead, moving away from the “one-size-fits-all” model used by large national banks.

This lender caters to a wide variety of enthusiasts, from those looking for a simple travel trailer to owners seeking a massive yacht or a fifth wheel. They understand that the lifestyle isn’t one-size-fits-all, providing diverse options for different types of adventure. For instance, if you are looking for a vintage Airstream that might have unconventional value to a collector, a specialized lender is much more likely to understand the asset’s worth than a generic car loan provider.

If you are staring at a $10,000 budget or looking at something much larger, they provide a starting point. Their ability to handle everything from camper vans to horse trailers makes them a versatile choice for the nomadic soul. They specialize in finding lenders that view your down payment and your stable income as more important than a recent dip in your FICO score caused by a medical bill or a past credit mishap.

Pros:

  • Nationwide search for best programs
  • Minimum score of 550 for bad credit
  • Covers various vehicle types

Cons:

  • Interest rates can be higher for bad credit

2. FastLendGo

FastLendGo – fastlendgo.com

Sometimes, the need for cash is urgent, like a sudden repair or a last-minute deal on a camper. FastLendGo focuses on the speed of personal financing, offering a way to compare local options without the headache of traditional bank queues. This is particularly useful if you are looking to buy a private-party RV where the seller wants cash on the spot rather than waiting for a title loan to process.

They cater to a spectrum of credit needs, from “great credit” to “bad credit.” This flexibility means that whether you are looking for a small $500 boost for new camping gear or a larger personal loan to cover a significant down payment, there is a potential path forward for your specific situation. By matching you with various lenders, they increase the likelihood that you find a term that fits your monthly cash flow.

The platform is built for those who want to avoid the “where can I find a loan near me” scavenger hunt. By streamlining the digital comparison process, they aim to get you moving toward your next destination much faster. The interface is designed to minimize the time spent entering the same data multiple times, which is a common frustration with traditional lending portals.

Pros:

  • Quick access to cash via comparison
  • Covers various loan sizes
  • Options for diverse credit scores

Cons:

  • Focuses more on personal loans than specialized RV titles

3. Alliant Credit Union

Alliant Credit Union – alliantcreditunion.org

Alliant Credit Union stands out for those who prefer the community feel of a credit union. They offer rates that aim to beat the standard industry averages, making them a formidable opponent for traditional big-box banks. Because credit unions are member-owned non-profits, they often return their “profits” to members in the form of lower interest rates and fewer fees.

Speed is a major player here, as most members can receive a same-day approval. This is a lifesaver when you find that perfect used RV at a dealership and need to prove you are a serious buyer immediately. In the world of RV shopping, where a clean title and a low mileage engine can make a unit sell in hours, having that pre-approval in your pocket is a massive competitive advantage.

Their approach is built on rewarding members, offering a different experience than the cold, distant feeling of a massive national bank. It is about finding a financial partner that grows with your travel ambitions. As you move from a small camper van to a full-sized motorhome, a credit union is more likely to recognize your history as a loyal member and offer preferential terms for your next upgrade.

Pros:

  • Competitive credit union rates
  • Fast same-day approval in most cases
  • Member-focused approach

Cons:

  • Membership requirements may apply

4. U.S. Bank

U.S. Bank – usbank.com

For those who prefer the stability of a massive, established institution, U.S. Bank provides a digital-first approach to vehicle financing. Their system is designed to integrate into a modern, mobile lifestyle. If you are someone who manages your finances entirely through a smartphone and expects 24/7 digital access to your loan documents, this is a strong contender.

One of their strongest tools is the online pre-approval process. Knowing exactly how much you can borrow before you step foot on a dealership lot prevents the awkwardness of being turned away at the finish line. It allows you to walk into a dealership with the confidence of a cash buyer, knowing that your budget is firm and your financing is ready to go.

They offer a comprehensive suite of services, from checking accounts to wealth management. This makes them a one-stop shop for anyone looking to consolidate their entire financial life under one roof. For high-net-worth individuals or those looking to bundle their mortgage, savings, and RV loan, the convenience of a single institution can provide significant administrative relief.

Pros:

  • Convenient online pre-approval
  • Established, large-scale institution
  • Comprehensive banking ecosystem

Cons:

  • Stricter requirements compared to specialized lenders

5. Solarity Credit Union

Solarity Credit Union – solaritycu.org

Solarity Credit Union focuses on “brighter banking,” offering a more personalized touch to the lending process. They understand that a loan is more than just a transaction; it is a step toward a goal. When you speak with their representatives, you aren’t just a number in a database; you are a person with a specific vision for your retirement or your next season of travel.

Their RV and motor sport loans are designed to be simple and convenient. They aim to make the banking experience feel supportive rather than obstructive, which is vital when you are dealing with high-ticket items like motorized homes. They understand the nuances of recreational vehicle depreciation and how that affects your loan-to-value ratio, which can be a sticking point with traditional auto lenders.

As an NCUA-insured institution, they provide a layer of security that offers peace of mind. You can focus on planning your route through the national parks rather than worrying about the safety of your funds. This security is paramount, especially when you are making large transfers or managing significant down payments for a new lifestyle.

Pros:

  • NCUA insured security
  • Expert guidance from knowledgeable employees
  • Modern digital tools

Cons:

  • May have stricter eligibility than niche lenders

The Hidden Costs of RV Financing

Many buyers focus solely on the monthly payment, but a comprehensive view of your budget must include several “hidden” costs that can derail your travel plans if not accounted for upfront. When negotiating your loan, keep these factors in mind to ensure your lifestyle remains sustainable.

First, consider the impact of sales tax and registration fees. Depending on your state of residence, these can add thousands of dollars to the initial cost. Some lenders will roll these into the loan, but this increases your total interest paid over the life of the loan. It is often smarter to pay these upfront if your budget allows. Second, consider the cost of comprehensive and collision insurance. Most lenders require full coverage for any financed RV, and for a large motorhome, these premiums can be significantly higher than standard automobile insurance.

Finally, never forget the “lifestyle overhead.” An RV is more than just the vehicle; it is a home. You must account for campground fees, fuel, propane, and regular maintenance. A common mistake is to commit 100% of your disposable income to the vehicle loan, leaving no room for the actual adventure. A healthy budget should leave a buffer for unexpected repairs, such as a failed water pump or a worn-out tire, which can occur at any time during a long trip.

Essential Checklist for Securing Your Loan

To maximize your chances of approval and secure the best possible terms, follow these step-by-step specifics before you head to the dealership.

  • Verify Your Documentation: Gather your last two years of W-2s, your most recent 30 days of pay stubs, and your most recent bank statements. Lenders love consistency. If you are self-employed, have your last two years of tax returns ready to go.
  • Know Your Credit Score: Don’t wait for a lender to tell you your score. Check it yourself first. If there is a mistake on your report, dispute it now. A 20-point difference in your score can mean hundreds of dollars in interest savings over the life of the loan.
  • Calculate Your “All-In” Budget: Don’t just look at the sticker price. Calculate the total cost: Sticker Price + Sales Tax + Registration + Documentation Fees + Insurance + Initial Maintenance. This is your true starting point.
  • Compare the APR, Not Just the Monthly Payment: A lender might offer a low monthly payment by extending the loan to 15 or 20 years. While this helps your monthly cash flow, the total interest you pay over that time could be astronomical. Always look at the Annual Percentage Rate (APR) to understand the true cost of the money.
  • Get a Pre-Approval First: As mentioned with U.S. Bank, having a pre-approval in hand gives you leverage. When a dealer knows you already have financing, they are less likely to try to “upsell” you on high-interest in-house financing options.

Navigating the Road Ahead

Before signing any paperwork, it is vital to look at the total cost of the loan. A low monthly payment might look enticing, but if it comes with a massive interest rate, you will end up paying for the RV twice. Always ask for the total amount to be repaid over the life of the loan. This number is the most honest representation of the deal’s value.

Avoid the trap of rushing into a deal just because the salesperson is leaning in. It is perfectly acceptable to take a breath, look at your budget, and ensure the monthly payment fits comfortably into your lifestyle. Your freedom on the road depends on your financial freedom at home. A debt-heavy RV is just a very expensive way to feel trapped in a small space; a well-financed RV is the key to true independence.