Top 5 Lenders for Car Repair Loans for Bad Credit in 2026

Car repair loans for bad credit

Top 5 Lenders for Car Repair Loans for Bad Credit in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Walking into a mechanic’s shop only to find out your transmission needs a complete overhaul is a gut punch. When the repair bill looks more like a mortgage payment, the stress can feel overwhelming. For many drivers, a sudden mechanical failure is a crisis that demands immediate cash to keep life moving.

A failed alternator might cost $400, but a transmission swap or an engine replacement can easily soar into the $3,000 to $5,000 range. This creates an immediate liquidity gap that most monthly budgets cannot absorb without planning. It is a sudden, sharp financial blow that catches most people off guard.

Finding a lender that accepts less-than-perfect credit scores is the primary goal for most people in this situation. When your credit score has been impacted by medical bills, student loans, or previous missed payments, traditional banking institutions often become inaccessible. You find yourself staring at a locked door when you need a way out.

This ranking focuses on speed, accessibility, and the reality of borrowing when your credit history isn’t your strongest asset. It is about getting back on the road without sinking further into a financial hole. We looked at how these lenders actually function when you are in a pinch.

  1. Manhattan Bank
  2. FastLendGo
  3. Addition Fi
  4. Minute Loan Center
  5. CreditNinja

How We Evaluated These Repair Financing Options

The selection process prioritized lenders that cater specifically to those facing unexpected automotive expenses. We looked for providers that offer quick turnaround times, which is critical when you need your vehicle for work or family obligations. Speed is often the difference between getting to a job and losing a paycheck.

If you are a delivery driver or a commuter with a long distance to travel, a three-day waiting period for funds might mean losing several shifts of income. This effectively increases the “true cost” of the loan. You aren’t just paying interest; you are paying for the time you spent without a car.

We also examined the breadth of loan products offered by each entity. A lender that provides various amounts, from small emergency sums to larger amounts, offers more flexibility for different repair scenarios. A simple brake pad replacement might only require a $300 quick loan.

Conversely, a blown head gasket might require $2,500. We looked for lenders that don’t force you into a massive loan if you only need a small fix, and those that can scale up for major structural repairs. The following comparison highlights the key features available for each provider based on their current service offerings.

Lender Name Loan Amounts Funding Speed Credit Requirements
Manhattan Bank See site See site See site
FastLendGo $500 – $5,000 See site Bad/Fair Credit
Addition Fi Up to $5,000 See site See site
Minute Loan Center See site Same-day Fair Credit
CreditNinja See site Same day* Bad Credit

The Best Lenders for Automotive Repairs

1. Manhattan Bank
Manhattan Bank – manhattanbank.com

Manhattan Bank operates as a traditional banking institution with the security of FDIC insurance. This provides a level of peace of mind that many specialized online lenders simply cannot match. For those who prefer working with a formal bank structure, this is a solid option for various personal loan needs.

Because they are a full-service bank, they offer a more structured approach to borrowing. While this might mean a slightly more thorough vetting process—often involving a review of your debt-to-income ratio and employment history—the stability of an FDIC-insured institution is a massive advantage for long-term financial health.

When applying with a traditional bank, you are typically looking for a “Personal Loan,” which is unsecured. This means you don’t have to put your vehicle up as collateral, which is a significant relief if you are already struggling with car-related expenses. You can keep your title in your hand.

However, because they prioritize stability, they may require a more established banking history or a steady stream of documented income via pay stubs or W-2s. They want to see that your income is as reliable as their vaults.

Pros:
  • FDIC-insured security
  • Established banking reputation
  • Offers personal loans for many occasions
Cons:
  • May have more rigorous application requirements than quick-cash lenders

2. FastLendGo
FastLendGo – fastlendgo.com

FastLendGo specializes in being a partner for those who might struggle with traditional bank requirements. They offer a wide range of specialized products, including specific options for auto repair loans and even motorcycle loans. This makes them a versatile choice for various mechanical emergencies.

Instead of trying to fit a square peg into a round hole with a general-purpose loan, FastLendGo‘s specialized products are tailored to the reality of automotive ownership. They understand that a car isn’t just a luxury; it is often a tool for survival.

With loan amounts ranging from $500 up to $5,000, they cater to both small fixes and larger, more significant engine repairs. This range is particularly useful for tiered repair needs. You can address the immediate crisis without over-borrowing.

For instance, if your mechanic says, “You need a new fuel pump now, but you can wait six months on the suspension,” FastLendGo allows you to borrow exactly what is needed for the immediate crisis. Their focus on high-speed access makes them a strong contender for anyone in a time-sensitive situation.

Pros:
  • Specific auto repair loan options
  • Flexible loan amounts from $500 to $5,000
  • Designed for bad and fair credit
Cons:
  • Limited to specific states

3. Addition Fi
Addition Fi – additionfi.com

Addition Financial Credit Union offers a membership-based approach to personal banking. For those looking to build a long-term relationship with a financial institution, this is a standout choice. Credit unions are member-owned cooperatives, which often means they operate with a different philosophy than for-profit banks.

Their primary goal is to serve their members, which can translate to more personalized service and competitive terms. It feels less like a cold transaction and more like a community resource. They aren’t just looking at numbers on a screen; they are looking at people.

They offer competitive rates and a variety of loan products. While they are a broader credit union, their ability to help members “borrow smarter” makes them a reliable option for those who want to manage their debt responsibly while fixing their vehicle.

Because credit unions often have slightly more flexible underwriting criteria than large national banks, they may be more willing to look at the “why” behind a low credit score—such as a past medical emergency—rather than just the score itself. They see the human story behind the data.

Pros:
  • Credit union membership benefits
  • Competitive rates for members
  • Diverse range of financial products
Cons:
  • Requires membership to access full benefits

4. Minute Loan Center
Minute Loan Center – minuteloancenter.com

When the car is stuck in the shop and the clock is ticking, Minute Loan Center offers a rapid response. They focus heavily on the speed of the application and the immediacy of the funds. Their model is built for people who need cash to be deposited as soon as the same business day.

This is a vital feature for those living paycheck to paycheck, where a three-day delay in funds could mean a late fee on rent or a missed utility payment. In these moments, every hour feels like a lifetime. They aim to cut that waiting time down to almost nothing.

The platform is designed to be straightforward, aiming to help users step into financial freedom through quick approvals. The digital-first approach means you can often complete the entire process from your smartphone while waiting in the mechanic’s lobby.

This is ideal for the driver who cannot afford to miss a day of work because their vehicle is sidelined and they need to authorize the repair immediately to get it back on the road. They prioritize getting you back to work, which keeps your income flowing.

Pros:
  • Same-day deposit potential
  • Fast approval process
  • User-friendly online application
Cons:
  • Approval is dependent on fair credit status

5. CreditNinja
CreditNinja – creditninja.com

CreditNinja acts as a bridge for those who find themselves unable to get approved by traditional lenders. Their system is designed to match users with loan options that fit their specific credit profile. It is a way to stop guessing and start knowing.

Rather than you spending hours applying to ten different lenders only to get ten rejections, CreditNinja uses a matching algorithm to point you toward the lenders most likely to approve your specific situation. It is a streamlined way to find a solution when other doors have closed.

The process is quick and simple, focusing on providing a fast decision. If you are in a pinch and need to know where you stand without a long, drawn-out waiting period, this is an efficient way to explore your options.

It acts as a powerful reconnaissance tool for anyone who is unsure of their eligibility in a high-pressure environment. It helps you narrow your search so you aren’t wasting energy on lenders that will simply say no.

Pros:
  • Same-day decision potential
  • Quick and simple online application
  • Targets those with bad credit
Cons:
  • Does not guarantee approval

Understanding the Total Cost of Borrowing

When you are in an emergency, it is easy to focus solely on the monthly payment, but this can be a dangerous trap. To truly understand your financial obligation, you must look at the Annual Percentage Rate (APR). This includes both the interest rate and any mandatory fees.

A loan with a “low” monthly payment might actually be more expensive over the long term if the interest rate is significantly higher than a standard bank loan. Don’t let a small number hide a large debt. Look at the grand total you will pay back by the end of the term.

Consider these three factors when reviewing a loan offer:

  • The Repayment Term: A 24-month loan will have much lower monthly payments than a 12-month loan, but you will pay significantly more in total interest over that extended period.
  • Origination Fees: Some lenders deduct a fee from the loan amount before you even receive it. If you need exactly $1,200 for a repair but the lender charges a $100 origination fee, you will only receive $1,100, leaving you short at the mechanic.
  • Prepayment Penalties: If you receive a bonus at work or a tax refund and want to pay off the car loan early to save on interest, some lenders charge a fee for doing so. Always check if “prepayment is without penalty.”

Smart Steps to Prepare for Your Loan Application

Securing a loan under pressure is difficult, but being prepared can increase your chances of approval and better terms. Even if you are applying for a high-speed loan, having your documentation ready can prevent delays that could leave you stranded without transport.

Follow these steps to streamline the process:

  1. Gather Documents: Have your most recent pay stubs, a government-issued ID, and your bank account details (for direct deposit) ready. If you are self-employed, have your last two years of tax returns on hand.
  2. Get a Written Estimate: Do not guess the amount you need. Ask your mechanic for a detailed, written estimate that includes parts and labor. Borrowing too little leads to more debt later; borrowing too much leads to unnecessary interest.
  3. Check Your Own Credit: While you may have bad credit, knowing your score helps you understand which lenders (like CreditNinja or FastLendGo) are your most viable targets.
  4. Verify Your Income: Lenders want to see that you have the ability to repay. Even if your credit is poor, a stable, documented income is your strongest asset during the underwriting process.

Navigating your borrowing options requires a balance of urgency and caution. Before signing any paperwork, it is vital to look at the total cost of the loan. Interest rates can vary wildly between a traditional bank and a specialized lender. Always ask for the total amount you will be paying back over the life of the loan, not just the monthly payment.

Another common pitfall is rushing into a high-interest loan just to solve an immediate problem. While speed is important, an expensive loan today can become a heavy burden tomorrow. Compare your options carefully and ensure the repayment schedule fits comfortably within your monthly budget.

If a monthly payment would mean you can’t afford groceries or gas, the loan is too large or the term is too long. You shouldn’t have to choose between fixing your car and feeding your family. Take a breath and look at the math one more time.

Finally, read the fine print regarding any fees. Some lenders charge origination fees or prepayment penalties that can catch you off guard. Taking ten minutes to read the terms can save you hundreds of dollars in the long run, ensuring your car repair doesn’t lead to a financial disaster. Your goal is to get back on the road, not to remain stuck in a cycle of high-interest debt.
Top 5 Lenders for Same Day Personal Loans in 2026

Same day personal loans

Top 5 Lenders for Same Day Personal Loans in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Life rarely waits for a convenient time to throw a curveball. Whether it is an unexpected car repair that leaves you stranded, an urgent medical bill, or a leaking roof that needs immediate attention, finding quick cash can feel like chasing a ghost in a crowded room. In these high-stress moments, the mental bandwidth required to handle complex financial systems often vanishes first.

This is why many people turn to same-day personal loans to bridge the gap between a sudden crisis and their next paycheck. Choosing a lender is about more than just who moves the fastest. If you prioritize speed above all else, you might find yourself trapped in a high-interest cycle that takes years to escape.

It is about finding a balance between speed, cost, and the long-term impact on your financial reputation. This ranking looks at the most reliable options currently available to help you handle these high-pressure moments without making a mess of your future. We have analyzed the top players in the market for 2026.

  1. JetzLoan
  2. Avant
  3. SoFi
  4. Discover
  5. CreditNinja

How the Top Lenders Were Evaluated

The selection process focused heavily on how fast money hits your account and how easy the application feels. Nobody wants to spend hours filling out paperwork or waiting on hold with a representative only to wait a week for a decision. We looked for lenders that offer digital-first experiences and rapid deposit timelines using modern banking technology.

Beyond speed, we looked at accessibility and transparency. We prioritized lenders that provide clear information regarding credit impacts and loan amounts. It is vital to know if a hard credit pull is required before you start clicking buttons, as this can affect your ability to secure a mortgage or an auto loan later.

A “soft pull” allows you to shop around for the best interest rate without a penalty. This is a critical distinction for anyone trying to maintain a healthy credit profile while seeking emergency funds. We also evaluated the friction within the application journey, such as whether a lender uses automated systems like Plaid to verify income instantly or requires manual pay stubs.

The goal was to identify lenders that respect your time as much as your money. We wanted to see who makes the process painless and who leaves you scrambling for documentation. The following table summarizes our findings across the top five candidates.

Lender Loan Amount Range Funding Speed Credit Impact Check
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
Avant $2,000 – $35,000 Fast decision See site
SoFi See site See site See site
Discover $2,500 – $40,000 As early as next business day No impact to credit score for pre-approval
CreditNinja See site As soon as the same day See site

Ranking of Best Lenders

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan connects borrowers with various top lenders in a matter of minutes. Rather than being a single bank, it functions as a marketplace. This is a significant advantage because it saves you the time of visiting ten different websites to see who will give you the best rate. Instead, you enter your data once, and the platform does the heavy lifting.

The process is remarkably streamlined, requiring less than two minutes to complete the initial form. This makes it a standout for anyone who needs to move quickly without a heavy administrative burden. For example, if you are at a mechanic’s shop and need to pay for a repair immediately to get your car back, the speed of JetzLoan is designed for that exact scenario.

The platform is built for those who might be nervous about their credit standing. Because they offer a way to check rates without a hard credit pull, you can explore your options without any fear of damaging your score. It is a low-pressure way to find significant funding without the “sticker shock” of seeing a credit score drop before you even know if you qualify.

Pros:

  • Funds can be deposited in as little as 24 hours.
  • No hard credit pull required for the initial rate check.
  • High customer rating of 4.7 stars.

Cons:

  • Acts as a marketplace rather than a direct lender.

2. Avant

Avant – avant.com

Avant focuses on providing flexible tools for people who are navigating complex financial journeys. They understand that “one size fits all” rarely works in lending. They offer solutions for various needs, including debt consolidation, emergency expenses, and home improvements. This versatility is helpful for someone trying to solve two problems at once.

You might find yourself needing to pay off a high-interest medical bill and a predatory payday loan in a single lump sum. Their application process is simple, utilizing a three-step method to get you from start to finish. This is ideal for someone who needs a quick decision to handle an unexpected life event.

They aim to provide clarity when you might be facing difficult financial questions. They often provide clear terms upfront so there is no confusion about what your monthly payment will look like. This transparency helps prevent any nasty surprises when the first bill arrives in your inbox.

Pros:

  • Simple, three-step application process.
  • Options for debt consolidation and emergency loans.
  • Flexible solutions for different financial goals.

Cons:

  • Specific eligibility requirements are not always immediately transparent.

3. SoFi

SoFi – sofi.com

SoFi is a massive player in the financial ecosystem, offering everything from banking and checking to investing and mortgages. For those who want a one-stop shop for their entire financial life, this is a powerhouse. They cater to a wide range of needs through digital, automated processes that feel much more like a modern tech app than a traditional bank.

While they are known for more traditional long-term financial products, their digital-first approach allows for much faster movement than old-school banks. They are a great option for borrowers who value a high-tech, integrated experience across all their various money management needs. If you already have a high credit score, SoFi is often the gold standard.

They offer premium rates with zero paperwork for those who qualify. The experience is incredibly fluid, making it easy to manage your finances from your phone. It is a sophisticated option for users who want their lending to match their digital lifestyle.

Pros:

  • Comprehensive financial suite including investing and banking.
  • Highly digital and automated application process.
  • Reputable brand with extensive financial tools.

Cons:

  • May require higher credit standards for the best terms.

4. Discover

Discover – discover.com

Discover brings a sense of traditional stability to the online lending world. They offer a wide range of products, including credit cards and personal loans, with a focus on customer service and security. It is a solid choice for someone who wants a well-established name behind their loan.

You might want to know that if you have a question, there is a massive infrastructure of customer support ready to assist them. The platform is particularly useful for those who want to “check before they commit.” You can see if you are pre-approved for certain products with no impact to your credit score.

This allows for a cautious approach to borrowing in an uncertain economic climate. It is a “try before you buy” model that removes the anxiety of the unknown. If you prefer a lender that feels like a pillar of the industry, Discover is a reliable bet.

Pros:

  • Pre-approval checks do not impact credit scores.
  • Wide range of loan amounts available.
  • Highly rated customer service and security.

Cons:

  • Funding may take until the next business day rather than the same day.

5. CreditNinja

CreditNinja – creditninja.com

CreditNinja is a go-to option for those who might find traditional banks a bit too stingy. They specialize in helping people who may not qualify for standard loans, offering a path to finding solutions for unexpected life expenses. Their application is designed to be quick and simple, focusing on your specific profile.

The standout feature here is the potential for same-day money. If you are approved and sign for your loan, the funds may be deposited directly into your account as early as the same day. This is a lifesaver when a deadline is looming, such as an eviction notice or a utility shut-off warning.

It is designed for high-stakes situations where every hour counts. While you might pay more for this speed, the ability to resolve a crisis immediately is worth a lot to many people. It is a specialized tool for those in urgent need.

Pros:

  • Potential for same-day funding upon signing.
  • Designed for those who struggle with traditional loan approvals.
  • Quick and easy online application process.

Cons:

  • Interest rates can be higher for those with less ideal credit.

The Step-by-Step Process of Securing a Quick Loan

To ensure you get the best possible outcome, you should approach the application process with a specific workflow. Following these steps can prevent common delays that turn a “same-day” loan into a “three-day” headache.

Step 1: Gather Your Documentation in Advance. Even with automated systems, you will likely need to provide your Social Security Number, your monthly gross income, and your primary banking details. Having a digital copy of your most recent pay stub or a bank statement ready to upload can prevent the application from stalling in the “pending verification” stage.

Step 2: Use a Soft Credit Pull First. Always look for the “check your rate” option. This allows you to see the estimated APR and monthly payment without any risk to your credit score. If the rate is significantly higher than you can afford, you can walk away without any lasting financial damage.

Step 3: Compare the APR, Not Just the Monthly Payment. This is where many borrowers make a mistake. A lender might offer a very low monthly payment, but if that is because they have stretched the loan term out to five years, you will end up paying thousands more in interest. Always look at the total cost of the loan over its entire lifespan.

Step 4: Verify the Funding Method. If you need money today, ensure you have a checking account that supports “Real-Time Payments” or “Instant ACH.” Some lenders can send money instantly, but if your bank only processes transfers overnight, you won’t see that cash until the next business morning regardless of how fast the lender acts.

Avoiding Common Pitfalls When Borrowing

The first mistake many people make is rushing into the first offer they see without looking at the fine print. While speed is the primary goal, the cost of that speed can be high. Always check the total cost of the loan to ensure it is manageable. Specifically, look for “origination fees.”

If you borrow $1,000 but the lender takes a $50 origination fee, you only receive $950, but you still owe interest on the full $1,000. Another trap is forgetting to compare different types of credit. Sometimes, a credit card with a low interest rate might actually be cheaper than a quick personal loan for a small amount of money.

Take a moment to breathe and evaluate your total debt-to-income ratio before signing. If your monthly debt payments already consume a large portion of your income, adding another loan could lead to a cycle of borrowing just to pay off previous debts. Avoid the temptation to borrow more than you absolutely need.

Every dollar borrowed is a dollar that must be repaid with interest. Use these tools as a bridge to get you from one stable point to another, not as a permanent lifestyle adjustment. A loan should be a tool for resolution, not a source of new, ongoing stress.

Top 6 Lenders for Christmas Loans for Bad Credit in 2026

Christmas loans for bad credit

Top 6 Lenders for Christmas Loans for Bad Credit in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

The holiday season usually brings a bit of magic, but for many families, those festive lights feel a little dim when the mounting expenses start piling up. Between buying gifts for the kids and hosting those obligatory dinners, bank accounts often look pretty thin by mid-December. Trying to bridge that gap without falling into a debt trap is a delicate balancing act.

When you need a quick injection of cash, your biggest worry is usually how a lender will view a less-than-perfect credit history. It isn’t just about finding the money. It is about finding a partner that won’t penalize you for past financial hiccups. Speed, transparency, and the actual cost of borrowing are the three things that matter most for a smart holiday loan.

  1. Wells Fargo
  2. FastLendGo
  3. LendingPoint
  4. VivaLoan
  5. NetCredit
  6. Prosper

How These Holiday Lenders Were Evaluated

Our selection process focused heavily on how fast a borrower can move from an application to having cash in hand. In the middle of the Christmas rush, waiting two weeks for a decision is simply not an option. We looked at how lenders handle diverse credit profiles, including those with bruised scores or high incomes but very limited history.

We also looked at whether loan amounts were flexible and if the terms were clear. It is vital to know exactly how much you can borrow for a specific need, whether it is a $500 emergency or a $10,000 debt consolidation. Only lenders with clear, accessible information regarding their requirements and funding speeds made the final cut for this 2026 roundup.

Lender Name Loan Amounts Funding Speed Credit Requirements
Wells Fargo See site See site See site
FastLendGo $500 – $5,000+ Quick access Bad credit options
LendingPoint $1,000 – $36,500 See site Check rate (no impact)
VivaLoan $100 – $15,000 As soon as tomorrow All credit types
NetCredit Up to $10,000 Same-day funding available See site
Prosper $2,000 – $50,000 Fast access See site

The Definitive 2026 Holiday Loan Rankings

1. Wells Fargo

Wells Fargo – wellsfargo.com

Established financial institutions often provide a sense of stability that newer fintech companies lack. For those looking to manage their finances through traditional banking channels, this option offers a wide range of services, including checking and savings accounts. It is a massive ecosystem built to handle everything from simple daily transactions to complex wealth management needs.

This lender works well for individuals who prefer a traditional banking relationship. You might benefit from additional services like credit cards or home loans here. While it is a powerhouse in the financial sector, the complexity of their product line means you have to look through various offerings to find the specific personal loan that fits your current holiday budget.

Pros:
  • Extensive range of banking services
  • Established and trusted institution
  • Offers specialized accounts like Clear Access Banking
Cons:
  • Complex product ecosystem can be overwhelming

2. FastLendGo

FastLendGo – fastlendgo.com

When the holiday season hits a fever pitch, sometimes you just need a quick fix. This lender specializes in providing various personal financing solutions tailored to different life scenarios. Whether it is for auto repairs or a sudden dental bill, they offer a variety of loan sizes to match the specific emergency at hand. (fastlendgo.com)

They cater to a wide spectrum of borrowers, including those with bad credit or even those seeking first-time loans. It is a versatile option for those tired of the “one size fits all” approach used by big banks. If you are looking for something specific like a $500 or $1,000 loan, this could be a lifeline.

Pros:
  • Specialized loans for specific needs (Auto, Dental, Roof)
  • Covers a wide range of credit scores
  • Simple online application process
Cons:
  • Focuses on niche loan types rather than general banking

3. LendingPoint

LendingPoint – lendingpoint.com

For those who need a more substantial amount of capital to tackle larger holiday debts or home improvements, this lender steps up. They offer significant loan amounts that can help turn financial stress into a manageable plan. It is an excellent choice for anyone looking to consolidate debt or cover an unexpected large expense.

A standout feature here is the ability to check your rate without impacting your credit score. This allows for a “no-risk” exploration of your options before you commit to a formal application. It is a thoughtful approach for people who are cautious about their credit standing during a high-stress season.

Pros:
  • High loan limits up to $36,500
  • Check rates without credit score impact
  • Versatile loan purposes
Cons:
  • May require higher income to secure larger amounts

4. VivaLoan

VivaLoan – vivaloan.com

Speed is the name of the game when the holiday bills start piling up on the kitchen table. This lender is designed for the person who needs cash essentially yesterday. With the ability to get funds as soon as the next business day, they remove the long waiting periods that often plague traditional lending.

They are incredibly inclusive, welcoming all credit types into their application process. The ability to request small amounts, starting as low as $100, makes them highly accessible for minor holiday emergencies. It is a streamlined, five-minute request process that prioritizes your time and immediate needs.

Pros:
  • Extremely fast funding (as soon as tomorrow)
  • Low entry point starting at $100
  • Welcomes all credit types
Cons:
  • Rapid funding often comes with higher interest rates

5. NetCredit

NetCredit – netcredit.com

This lender operates on the philosophy that a person is much more than just a single number in a database. By using advanced algorithms, they look beyond the basic credit score to find a more holistic view of the borrower. This approach is refreshing for those who have been denied by more rigid institutions.

They offer a flexible range of products including personal loans and lines of credit with amounts up to $10,000. The availability of same-day funding is a massive advantage when you are facing a deadline. It is a modern, tech-forward solution for the contemporary borrower.

Pros:
  • Holistic underwriting approach
  • Same-day funding availability
  • Flexible lines of credit available
Cons:
  • Approval is subject to state-specific underwriting partners

6. Prosper

Prosper – prosper.com

Prosper offers a different flavor of lending through its connection to the peer-to-peer model. This can sometimes lead to more competitive options for those who qualify. They provide a variety of tools, including credit cards and investment options, making them a comprehensive platform for those looking to manage long-term financial health.

With loan terms reaching up to six years, it is a solid choice for those who want to spread out their repayments over a longer period. This can lower the monthly impact on your budget, which is vital when you are already juggling many holiday expenses. It is a strategic choice for the long-term planner.

Pros:
  • Longer repayment terms up to 6 years
  • Peer-to-peer model offers variety
  • Highly rated by financial experts
Cons:
  • Minimum loan amounts may be higher than micro-lenders

Avoiding the Holiday Debt Trap

Borrowing money during the holidays can feel like walking a tightrope. It is easy to get swept up in the excitement of the season and forget that every dollar borrowed today is a dollar that must be paid back with interest tomorrow. Before you sign any agreement, take a deep breath and look at the total cost of the loan.

One major mistake is ignoring the fine print regarding late fees and prepayment penalties. You want to be able to pay the loan off early if you find yourself with extra cash in January, but some lenders will penalize you for being responsible. Always ensure that the repayment schedule fits comfortably within your budget for the first three months of the new year.

Another pitfall is the “quick fix” mentality. While a small loan might solve a problem today, it doesn’t address the underlying habit that led to the shortage. Use this holiday cash as a bridge, not a permanent lifestyle adjustment. If you use these funds to create memories rather than just covering old debt, you might find the holiday spirit much more fulfilling.

Top 6 Lenders for Emergency Loans for Bad Credit in 2026

Emergency loans for bad credit

Top 6 Lenders for Emergency Loans for Bad Credit in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Life has a way of throwing a wrench into even the best-laid plans. A sudden transmission failure leaves you stranded on the highway, an urgent root canal brings an unexpected dental bill, or an HVAC breakdown strikes during a heatwave. In those moments, the need for immediate cash feels overwhelming. When your credit score isn’t exactly a glowing endorsement—maybe due to past medical debt or a period of unemployment—finding a lender feels like searching for a needle in a haystack.

This ranking focuses on speed, accessibility, and transparency for people facing urgent financial hurdles. Finding a lender that accepts less-than-perfect credit is only half the battle. The real challenge is ensuring the terms are manageable and the funds arrive before the crisis peaks. We analyzed several providers to see who stands out in this high-stakes market, looking at everything from digital application friction to the actual speed of capital deployment.

  1. Minute Loan Center
  2. FastLendGo
  3. Avant
  4. World Finance
  5. CreditNinja
  6. Reprise

How These Emergency Lenders Were Evaluated

Selecting the right lender requires looking past the flashy advertisements and marketing slogans. The evaluation process focused on how quickly funds could actually reach a borrower’s bank account after approval. In a true emergency, a three-day waiting period is often the difference between a solved problem and a mounting disaster. If you need to pay a mechanic to get to work on Monday morning, a lender that promises funds by Thursday is effectively useless. Speed is the primary metric of value here.

Beyond speed, the criteria included the ease of the application process and the variety of credit profiles accepted. A lender that requires a mountain of paperwork, physical visits to a branch, or multiple days of manual verification might be too slow for a midnight crisis. We also looked for providers that offer clear pathways for those with bad credit, ensuring no hidden surprises lurk in the fine print, such as predatory prepayment penalties or excessive origination fees that balloon the total cost of borrowing.

Lender Name Speed of Funding Max Loan Amount Credit Requirements
Minute Loan Center Same-Day See site Fair credit accepted
FastLendGo See site $5,000 Bad/Fair/Good
Avant See site See site Less than perfect credit
World Finance See site See site See site
CreditNinja Same-Day (with conditions) See site Bad credit okay
Reprise See site See site See site

Ranked Emergency Loan Providers

1. Minute Loan Center

Minute Loan Center – minuteloancenter.com

When the clock is ticking, Minute Loan Center steps into the ring with a focus on velocity. They specialize in same-day and instant online loans, aiming to get deposits into your account via direct deposit as soon as the business day begins. This makes them a heavy hitter for anyone staring down a deadline, such as a utility shut-off notice or a rent payment that is due by the end of the business day.

They cater specifically to those who might struggle with traditional bank requirements, offering approval even for those with fair credit. Because they have been around for over two decades, they have established a reputation for stability. In an era of fly-by-night fintech startups, having a provider that has weathered multiple economic cycles provides an extra layer of peace of mind. It is a solid choice for quick, digital-first relief when you cannot afford to wait for a manual underwriting process.

Pros:

  • Very fast same-day direct deposit.
  • No hidden fees or credit pulls mentioned.
  • Experienced provider with decades of service.

Cons:

  • Primarily focuses on a specific niche of rapid funding.

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo acts as a versatile partner for various personal financing needs, ranging from small $500 loans to larger $5,000 requests. They seem to understand that a car repair requires a different approach than a roof repair. For instance, if you need a small amount to cover a tire replacement, a large installment loan might be overkill. Conversely, if you are facing a major home repair, a tiny microloan won’t cut it.

Their platform is designed to help users compare local options quickly to find that middle ground. (fastlendgo.com) The service is built for those who need to skip the long lines and the endless wait times associated with brick-and-mortar lenders. Whether you have bad credit or are just starting your journey with no credit history, they offer a path forward. It is a flexible option for those who need specific amounts for specific crises, allowing for a tailored approach to borrowing that matches the scale of the emergency at hand.

Pros:

  • Wide range of loan amounts from $500 to $5,000.
  • Covers various needs like auto or dental financing.
  • User-friendly comparison interface.

Cons:

  • The comparison model may lead to multiple offers.

3. Avant

Avant – avant.com

Avant approaches personal finance with a focus on long-term movement rather than just quick fixes. While they handle emergency loans, they also offer tools for debt consolidation and credit cards. This makes them a useful option if your emergency is actually part of a larger financial puzzle. For example, if you are taking a loan to cover a medical bill, Avant might also help you restructure your existing high-interest credit card debt to make your monthly budget more sustainable in the long run.

They are particularly welcoming to those with less than perfect credit, providing a bridge to help you move financially forward. Instead of just handing over cash, they aim to provide solutions that fit into your specific life journey. It is a more holistic approach to borrowing that prioritizes the borrower’s future stability rather than just the immediate transaction. It is ideal for the borrower who wants to solve a current crisis while simultaneously improving their credit standing.

Pros:

  • Supports debt consolidation alongside emergency needs.
  • Tailored solutions for different financial stages.
  • Strong focus on moving a borrower forward.

Cons:

  • May have stricter qualifying criteria than specialized lenders.

4. World Finance

World Finance – worldfinance.com

World Finance is a massive entity in the financial landscape, offering a broad spectrum of banking and investment services. While their focus often leans toward more complex financial structures, they maintain a presence in the retail banking space. This provides a level of professional scale that smaller, online-only lenders lack. For many, there is a psychological comfort in dealing with a large-scale institution rather than an unproven app.

For a borrower in a pinch, they represent a more institutional approach to money management. They are a significant player in the global and retail markets, making them a stable entity in the financial ecosystem. It is a choice for those who want a more traditional, large-scale provider and who may prefer the ability to engage with a provider that has a significant, established footprint in the financial sector.

Pros:

  • Highly established and large-scale institution.
  • Broad range of financial services available.
  • Deep expertise in various banking sectors.

Cons:

  • May feel less specialized for a quick, small-dollar emergency.

5. CreditNinja

CreditNinja – creditninja.com

CreditNinja is built for the “life happens” moments when traditional banks turn you away. Their application process is designed to be quick and simple, requiring only basic information to see if you qualify. This “soft inquiry” style approach is designed to protect your credit score while you are just testing the waters. It is a streamlined approach for when you simply don’t have time to waste on lengthy applications that might lead to a rejection.

If you are approved, you can potentially see your money deposited the same day. However, there is a catch: you must apply and be approved by 10:30 a.m. on a business day to catch that same-day window. This requires a bit of proactive planning even in an emergency. If you wait until 4:00 p.m. to check your options, you might be looking at a delay that pushes your funds into the next business day, potentially missing your deadline.

Pros:

  • Extremely simple and fast online application.
  • Potentially very fast same-day funding.
  • Designed specifically for those denied by traditional banks.

Cons:

  • Strict morning deadline for same-day funding.

6. Reprise

Reprise – reprise.com

Reprise operates in a slightly different lane, functioning as an enterprise demo creation platform. While they offer sophisticated AI toolset and data injection for agents, they are not a traditional consumer lender for personal emergency cash. Their focus is on helping businesses build powerful product tours for their software or services.

They provide incredible capabilities for capturing screens and creating high-fidelity demos that look like real user sessions. If your “emergency” is actually a business need for high-end presentation tools to close a major sales deal, they are a powerhouse. However, for someone needing cash for a broken water heater or a car repair, they are not the right tool. It is important to ensure you are applying to a lender and not a business software provider.

Pros:

  • Advanced AI toolset for demo creation.
  • High-quality data injection for professional presentations.
  • Excellent for enterprise-level product tours.

Cons:

  • Not a consumer loan provider for personal emergencies.

Essential Steps for Securing an Emergency Loan

Navigating the world of rapid lending requires a strategic approach to ensure you don’t exacerbate your financial situation. Follow these steps to maximize your chances of success and minimize your long-term debt burden:

  1. Audit Your Need: Before applying, calculate the exact amount required. If a repair is estimated at $800, don’t borrow $1,200 just because the lender offers it. The interest on that extra $400 will compound quickly.
  2. Verify the “Total Cost of Credit”: Don’t just look at the monthly payment. Look at the total amount you will have paid back by the end of the term. A low monthly payment often means a much longer term and a significantly higher total cost.
  3. Check for Hidden Fees: Look specifically for “origination fees” (charged upfront), “processing fees,” and most importantly, “late payment fees.” In an emergency, your schedule might be chaotic; you need to know the penalty if a payment is a day late.
  4. Confirm the Funding Method: Not all “same-day” loans are created equal. Some require you to visit a physical location, while others use ACH transfers. For true speed, ensure the lender supports instant direct deposit to your existing checking account.

How to Navigate Emergency Borrowing

The most common mistake is rushing into the first offer you see without checking the details. Even in a panic, take a breath and look at the total cost of the loan. A quick fix can become a long-term headache if the interest rates are not clearly understood before you sign. Interest rates for high-speed, bad-credit loans are naturally higher than traditional personal loans, so the speed comes at a premium price.

Avoid the temptation to borrow more than you absolutely need to resolve the immediate crisis. It is easy to think, “If I’m borrowing, I might as well get extra,” but that extra cash comes with extra cost. Stay disciplined, compare the options, and choose the one that gets you through the storm without drowning you later. Use the emergency as a stepping stone to stability, not as a permanent fixture of your monthly budget.

The 7 Best Lenders for a Personal Loan with a Co-signer in 2026

Personal loan with co signer

The 7 Best Lenders for a Personal Loan with a Co-signer in 2026

Last updated: 2026-10-17

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Trying to find a lender when your credit score is lagging can feel like driving through a thick fog without headlights. Many people find themselves turning to a parent or a close friend to co-sign, hoping that someone else’s good credit can bridge the gap. This simple favor often makes the difference between a rejected application and getting the cash needed for an urgent car repair or a medical bill.

When you weigh your options, don’t just look at the monthly payment. You have to look at the big picture, including how fast you can get the cash and what the total cost will be over the years. A low monthly payment sounds great until you realize the loan term stretches to 72 months, making the interest payments skyrocket. Similarly, a lender that promises lightning-fast funding might hide massive origination fees that make the loan much more expensive than a traditional bank.

  1. FastLendGo
  2. OneMain Financial
  3. Upgrade
  4. Together Loans
  5. U.S. Bank
  6. MoneyLion
  7. MedLoan Finance

How the Top Lenders Were Evaluated

We spent a significant amount of time looking at current market offerings specifically for people using a co-signer. We wanted to see how lenders handle an application when two different people are involved. It was important to know if the requirements for the co-signer were clear or if the fine print was buried under layers of confusing language.

We investigated whether companies required a joint application or if they allowed a co-signer to simply act as a guarantor. This distinction matters because it changes how much of a risk the second person is taking on. We focused on lenders that made the process straightforward rather than those that added unnecessary paperwork to the pile.

Transparency was our main priority. We looked for companies that provided quick decisions, clear interest rates, and various loan amounts. We also checked the “friction” of the application process. This meant looking at how many documents you need to upload, how easy it is to sign things digitally, and how clearly they explain the Annual Percentage Rate (APR).

Lender Name Loan Amounts Key Terms/Rates Funding Speed Credit Focus
FastLendGo $500 – $5,000+ see site see site Bad to Great Credit
OneMain Financial $1,500 – $30,000 Rates from 11.99% APR As soon as 1 hour Bad Credit Friendly
Upgrade Up to $50,000 Fixed rates available Fast funding Credit Health focus
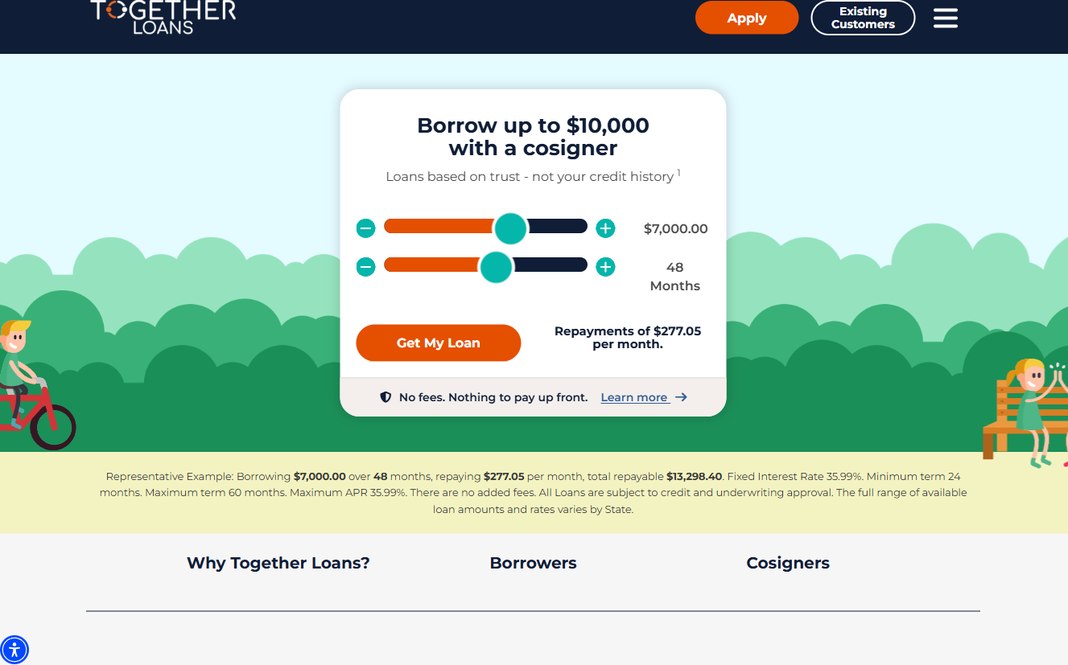
Together Loans Up to $10,000 24 – 60 months 24-hour approval Trust-based/Bad Credit
U.S. Bank see site see site see site Traditional Banking
MoneyLion Up to $100,000 see site Fast/Expedited available Credit Building focus
MedLoan Finance $500 – $100,000 12-18 Months Interest Free see site Medical Specific

Top-Rated Co-signer Loan Options for 2026

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo helps people who need cash quickly without jumping through a dozen hoops. They work with all sorts of people, from someone needing a $500 emergency fix to someone looking for a larger loan for a major life change. Their rules aren’t as stiff as a bank’s mortgage department, which makes them a good fit for gig workers or anyone with a fluctuating paycheck. (fastlendgo.com)

This lender is a lifesaver if you have a “thin” credit file. If you haven’t used much credit in the past, standard computer algorithms might struggle to understand your reliability. They offer specialized options for high earners and those with poor credit, ensuring almost anyone can find a way to borrow. It is a helpful way to use a co-signer to show the stability that your own history might not prove yet.

Pros:

  • Loan amounts start at $500, making them great for small emergencies.
  • They cover things like dental work or car repairs so you don’t need multiple loans.
  • Flexible options exist for many different credit levels.

Cons:

  • They focus on specific needs, so they might not be the best choice for general debt consolidation.

2. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is perfect for anyone who wants to talk to a real person instead of just an app. With over 1,300 physical branches, they have a presence that most online lenders simply can’t match. If you feel uncomfortable explaining your finances to a computer, sitting down with a loan officer in a real office can make you feel much more secure.

They are built for speed. In some cases, you can have your money just one hour after you sign the paperwork. Their joint loan options are also very easy to use, which helps couples or family members share the responsibility. It takes the guesswork out of having a co-signer on the line.

Pros:

  • You can get funding incredibly fast, sometimes within an hour.
  • A huge branch network means you can get in-person help whenever you need it.
  • Joint loans for $1,500 to $30,000 make the co-signer setup very simple.

Cons:

  • If your credit is low, the interest rates can get quite high, adding up over time.

3. Upgrade

Upgrade – upgrade.com

Upgrade takes a very modern approach, focusing on your financial health over the long haul. They offer everything from credit cards to savings accounts, which makes them a one-stop shop for your wallet. Their website is easy to use, and you can play around with different repayment numbers before you sign anything.

If you are trying to consolidate debt or pay for a big purchase, Upgrade makes the application very smooth. One of the best things they offer is a “soft pull” credit check. This means you can see your estimated monthly payment and APR without hurting your credit score, which is great for shopping around.

Pros:

  • Checking your rate won’t hurt your credit score.
  • You can use the money for almost anything, like home repairs or debt.
  • Some products even include cash back rewards.

Cons:

  • The variety of their products might feel like a bit much if you just want one simple loan.

4. Together Loans

Together Loans – togetherloans.com

Together Loans does things a little differently by looking at trust rather than just a digital score. This is a huge advantage for people who have a great co-signer but a messy credit history. Life happens, and sometimes a single medical bill or a period of unemployment can tank your score, but these lenders look at the human side of the story.

They specialize in loans up to $10,000 and are incredibly fast, often giving approvals within 24 hours. If you need to pay an unexpected bill right away, this is a solid option. Using a co-signer here can help you get much better terms than you would ever find on your own.

Pros:

  • They prioritize trust and personal circumstances over rigid algorithms.
  • The 24-hour approval is perfect for urgent situations.
  • There are no upfront fees, so you get the full amount you asked for.

Cons:

  • The interest rates can be on the higher side, so check the fine print.

5. U.S. Bank

U.S. Bank – usbank.com

If you prefer the feeling of a massive, established institution, U.S. Bank is a very steady choice. They are a great option if you already bank with them. Having an existing account can make the verification process move a lot faster since they already know your cash flow.

They might not be as fast as a new fintech startup, but they have a massive infrastructure behind them. They offer everything from basic checking to wealth management. If you are planning a major life event like a wedding, the stability of a big bank can give you a sense of security.

Pros:

  • They offer high levels of consumer protection and stability.
  • You can get almost every financial service you need in one place.
  • It is very easy to manage if you already use their banking services.

Cons:

  • Their requirements for personal loans can be stricter than smaller, niche lenders.

6. MoneyLion

MoneyLion – moneylion.com

MoneyLion is built for people who do everything on their smartphones. Their app is designed to help you manage daily spending while also working to build your credit. It feels more like a financial assistant than just a place to get a loan.

They offer large loans up to $100,000, which is enough for major changes like starting school. Because they focus so much on credit building, they are a great partner for anyone trying to move away from needing a co-signer. Eventually, the goal is to stand on your own two feet without help.

Pros:

  • They offer very high loan limits for large projects.
  • The app includes many tools to help you learn about credit.
  • The mobile interface is very easy to navigate.

Cons:

  • Some of the faster cash features might come with extra fees.

7. MedLoan Finance

MedLoan Finance – medloanfinance.com

MedLoan Finance is built for one specific thing: medical bills. If you are paying for dental work, LASIK, or a surgery, they provide funding that is designed for the healthcare world. General personal loans don’t always understand the timing of medical costs, but these lenders do.

They offer various loan amounts and even have some interest-free options for certain timeframes. If you have a surgery coming up, using a specialist like this can be much cheaper than taking out a high-interest personal loan from a general lender.

Pros:

  • They are specialists for dental and elective medical procedures.
  • Interest-free options for 12-18 months can save you a lot of money.
  • They handle large medical costs up to $100,000.

Cons:

  • You can’t use this money for anything other than medical expenses.

Understanding the Risks for Co-signers

Being a co-signer is a huge deal. When a friend or family member signs that paper, they aren’t just saying you are a good person. They are legally agreeing to pay the debt if you don’t. If you miss a payment, the lender can go after them for the full amount, including interest and late fees. This can lead to lawsuits or even wage garnishment, and it can absolutely wreck their credit score.

The debt also shows up on their credit report. Even if you pay everything on time, the sheer amount of that loan might make it harder for them to get a mortgage or a car loan later. Lenders see that debt as a potential obligation that might prevent them from paying their own bills. It’s a heavy burden to place on someone you care about.

How to Prepare for a Co-signer Application

If you want the best chance of getting approved, you need to be prepared. This means more than just having your ID ready; you need a rock-solid plan for how you will pay the money back. We suggest taking these steps before you even start the application:

  • Make a Payment Plan: Map out exactly when and how you will pay. Leave some extra room in your budget for months when things might get tight.
  • Check the Co-signer’s Credit: Most lenders want your co-signer to have a score between 670 and 700. If their score is low, you might be wasting your time.
  • Get Your Papers Ready: Lenders will want to see pay stubs, W-2s, and proof of where you live. Having these in a folder can save you days of waiting.
  • Read the Contract Together: Don’t just sign the papers. Sit down with your co-signer and read the part about what happens if you miss a payment.

Before you ask anyone to co-sign, you need to have a very honest conversation. They need to know that they are legally responsible for the money. If you have a falling out or if you lose your job, their credit score will take the hit just as much as yours. Money has a way of straining even the strongest family ties.

Don’t assume a co-signer is just a formality. Lenders treat them as a primary guarantor. If your co-signer’s credit isn’t much better than yours, the lender might still say no or give you a much higher interest rate. In that case, the co-signer isn’t actually helping you save money.

Finally, don’t borrow more than you actually need just because you can. Interest adds up fast, and the total cost can become a massive number over time. Use a co-signer to get a better deal, not just to borrow more money than you can handle.