Top 6 Lenders for Personal Loans for Credit Score Under 600 in 2026

Personal loans for credit score under 600

Top 6 Lenders for Personal Loans for Credit Score Under 600 in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Trying to manage your money when your credit score dips below 600 feels like walking through a thick fog. Most traditional banks tend to slam the door shut. This leaves anyone in need of quick capital searching for a lifeline. It is a stressful position to be in, especially when unexpected expenses arise, such as an urgent car repair, a medical bill, or a sudden gap in employment.

When you are in this position, the standard loan products offered by major institutions like Chase or Wells Fargo often feel out of reach. Their automated underwriting systems are programmed to prioritize high FICO scores and extensive credit histories. They aren’t really built to look at the person behind the number.

Finding the right lender requires more than just looking at interest rates. You must weigh speed, loan amounts, and how much a lender cares about your past mistakes versus your current income. For instance, a lender might be willing to overlook a previous bankruptcy or a late payment if they see a consistent, verifiable stream of income from a current employer.

This ranking aims to highlight the most viable options available for those working to rebuild their financial reputation. We have looked at several providers to see who actually helps when things get tough. Here are the top contenders for 2026.

  1. FastLendGo
  2. Avant
  3. Prosper
  4. Max Cash
  5. Upgrade
  6. LendingPoint

The Selection Process for Sub-600 Credit Lenders

The criteria used to evaluate these lenders focus heavily on accessibility for borrowers with fair or poor credit. We looked at the minimum loan amounts offered and the speed of funding. Immediate cash is often the primary driver for those seeking sub-600 loans. If you are facing an eviction notice or a utility shut-off, you don’t have time to wait ten business days for a decision.

You need a lender that operates with high-speed digital underwriting. We also examined the specific niches each lender serves. Some specialize in small, emergency cash advances, while others focus on larger debt consolidation efforts. Understanding whether a lender wants to see a high income or simply a steady history of employment helps determine which application is most likely to yield an approval.

For example, a lender might require a minimum monthly income of $2,500. Another might be satisfied with any steady income that can be verified through bank statements rather than traditional pay stubs. This distinction is vital when you are trying to secure funds on a tight deadline.

Lender Name Loan Amounts Credit Requirements Funding Speed
FastLendGo $500 – $5,000+ Bad/Fair Credit Fast Access
Avant See site Around 580 See site
Prosper $2,000 – $50,000 See site See site
Max Cash $250 – $10,000+ Bad Credit In Minutes
Upgrade Up to $50,000 See site See site
LendingPoint $1,000 – $36,500 See site See site

1. FastLendGo

FastLendGo – fastlendgo.com

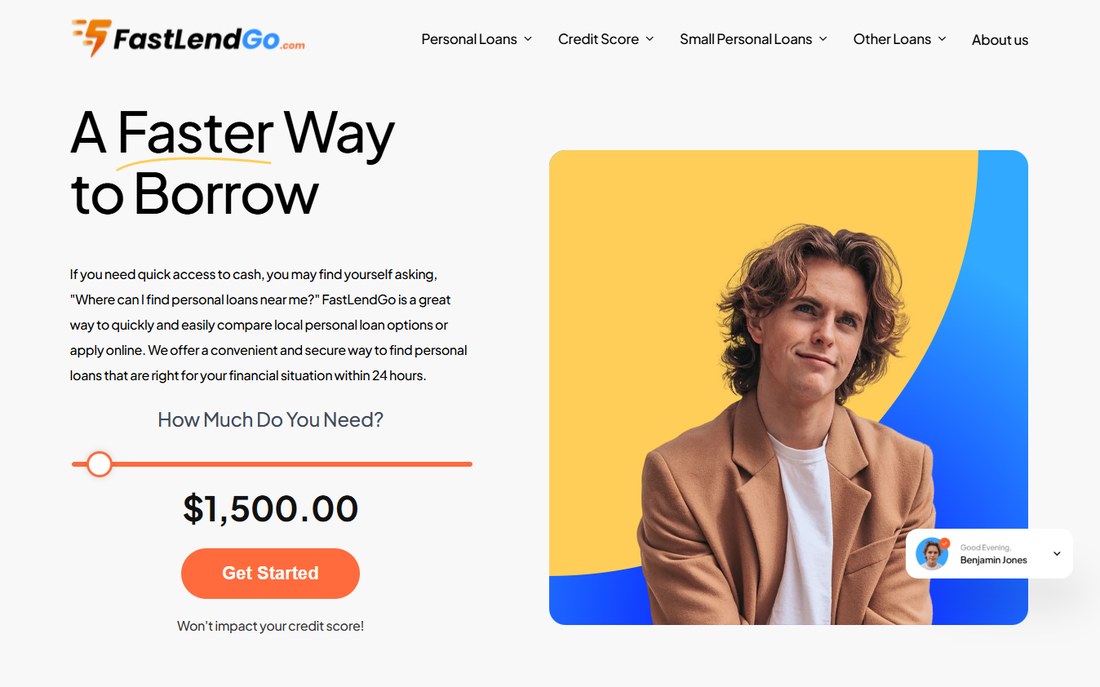
FastLendGo positions itself as a versatile partner for those needing quick cash to navigate life’s sudden hurdles. They offer a wide range of options, from small $500 loans to larger sums of $5,000 or more. This flexibility is a godsend for someone who just needs to cover a quick auto repair or a dental bill. Because they cater to specific needs, the application process is often streamlined to focus on the necessity of the funds rather than a deep dive into a decade of credit history. (fastlendgo.com)

This lender is particularly useful for individuals with bad or fair credit who might be ignored elsewhere. They cater to various needs, including motorcycle loans and roof financing. If you are looking for a way to compare local options quickly, this platform simplifies the often overwhelming search process. By specializing in niche lending, they can offer products that traditional personal loan providers won’t touch, such as collateralized options that use your vehicle or property to secure the funds.

Pros:

  • Wide variety of loan purposes including emergency and auto repairs.
  • Options for small-dollar amounts starting at $500.
  • Targets individuals with bad or fair credit.

Cons:

  • Limited information provided regarding specific interest rate ranges.

2. Avant
Avant – avant.com

Avant operates with a philosophy of helping people move forward financially, even when the road gets bumpy. They offer both personal loans and credit cards designed to help with debt consolidation or unexpected expenses. Their tools are built to simplify the journey toward better financial health, providing a digital interface that guides you through the necessary documentation without the need for a physical branch visit.

They are a solid choice for those hovering around the 580 credit score mark. Instead of judging you solely on a number, they focus on providing solutions like installment loans to help manage your monthly budget. Their model is designed to look at the “whole person,” meaning they may consider your debt-to-income ratio more heavily than a single late payment from two years ago. This is a proactive approach to credit management that prioritizes your ability to repay over your history of struggle.

Pros:

  • Offers both loans and credit card solutions.
  • Focuses on debt consolidation and home improvement.
  • User-friendly digital tools for financial management.

Cons:

  • Credit requirements may still exclude those with very low scores.

3. Prosper
Prosper – prosper.com

Prosper is a well-known name in the peer-to-peer (P2P) lending space, offering a different flavor of financing. Instead of a traditional bank, you are often borrowing from other individuals who are looking to earn interest on their extra cash. This can sometimes lead to more flexibility for those with non-traditional financial profiles, as the “lenders” in this scenario are often more willing to take on risk in exchange for higher potential returns.

The platform offers significant loan amounts, ranging from $2,000 all the way up to $50,000. This makes them a strong contender for major life events like weddings, significant debt restructuring, or large home improvements. Because the funding comes from multiple individual investors rather than a single institutional pool, the approval criteria can sometimes feel more nuanced. Their reputation is backed by high ratings from long-term customers who appreciate the transparent marketplace model.

Pros:

  • High maximum loan amounts up to $50,000.
  • Peer-to-peer model can offer diverse options.
  • Strong customer rating on third-party review sites.

Cons:

  • The peer-to-peer model can result in variable approval timelines.

4. Max Cash
Max Cash – maxcash.com

When you are staring at a sudden bill and the clock is ticking, Max Cash steps into the ring. They specialize in speed, offering installment loans and even title loans in a matter of minutes. This is clearly designed for the “emergency” scenario where every second counts—think a sudden transmission failure in your car that prevents you from getting to work, or an urgent medical procedure that requires a deposit.

Their loan amounts are highly segmented, starting as low as $250. This makes them an excellent option for those who don’t want to take on more debt than absolutely necessary. If you only need $300 to cover a utility bill, taking out a $5,000 loan is a recipe for disaster. Max Cash allows for surgical precision in borrowing. They provide a “relief” focused service for those in urgent financial straits who need liquidity immediately without the bureaucracy of a major bank.

Pros:

  • Extremely fast processing for emergency needs.
  • Very low entry point for small loans ($250).
  • Wide range of products including title loans.

Cons:

  • High-speed, small-dollar loans often carry very high interest rates.

5. Upgrade
Upgrade – upgrade.com

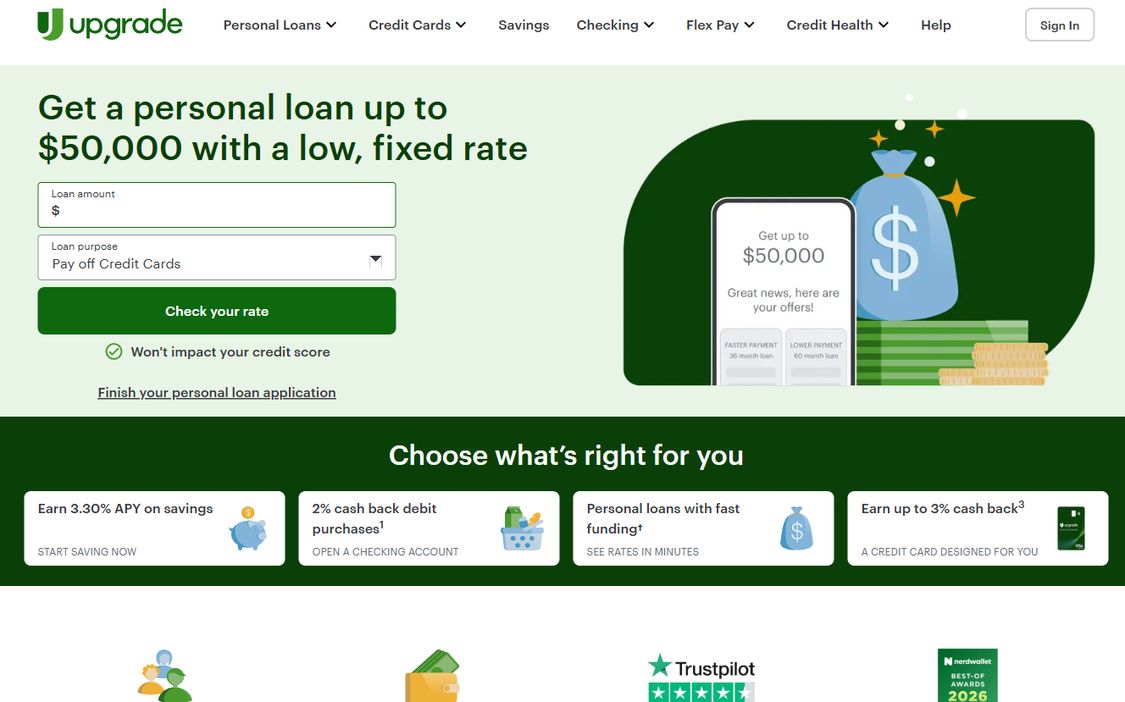
Upgrade is more than just a lender; they are a full-scale financial services provider. They offer personal loans, credit cards, and even checking accounts. This makes them a great “one-stop shop” for someone looking to consolidate their financial life into one ecosystem. By bringing multiple financial products under one roof, you can often find more streamlined management of your overall cash flow.

With a maximum loan amount of $50,000, they are suitable for significant life changes like business ventures or large purchases. Their model is built around helping customers earn rewards and manage their cash flow more effectively through their various products. They often use a combination of credit scores and income verification to determine eligibility, which can be a benefit for those who have a high income but a lower credit score due to past mishaps.

Pros:

  • Comprehensive suite of products including checking accounts.
  • High loan limits up to $50,000.
  • Offers cash back incentives on certain products.

Cons:

  • May require a more stable financial profile than specialized sub-600 lenders.

6. LendingPoint
LendingPoint – lendingpoint.com

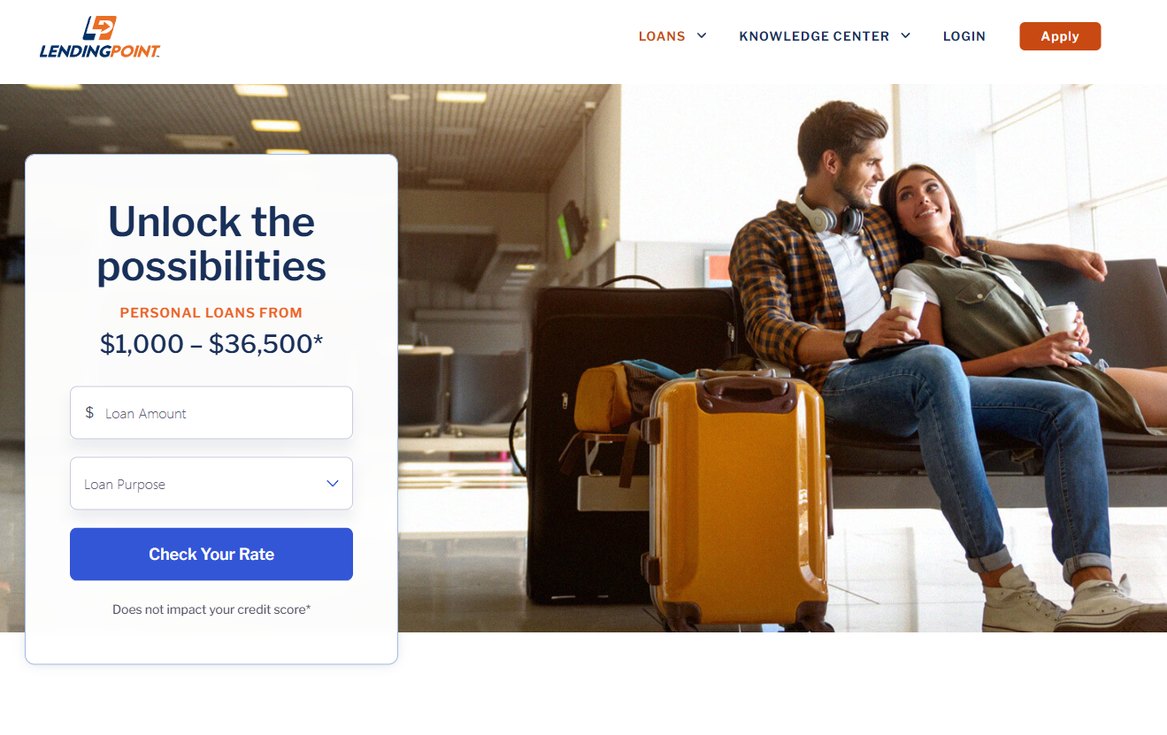
LendingPoint focuses on helping users unlock possibilities through personalized personal loans. They offer amounts ranging from $1,000 to $36,500, making them a middle-ground option for those who need more than a quick cash advance but less than a major bank loan. They target consumers who are looking for a way to bridge the gap between being “unbankable” and having a standard prime credit score.

Their application process is designed to be efficient, allowing you to check your rate without impacting your credit score. This is a massive advantage for someone with a sub-600 score who cannot afford to lose any more points to hard inquiries. Every time you apply for credit and are denied, it leaves a mark on your report. LendingPoint’s “soft pull” feature allows you to shop for terms with confidence and zero risk to your credit standing.

Pros:

  • Check rates without affecting your credit score.
  • Significant loan amounts up to $36,500.
  • Clear purposes for loans like medical or travel expenses.

Cons:

  • Credit requirements are not explicitly stated as “low credit” friendly.

Understanding the True Cost of Sub-600 Borrowing

When your credit is below 600, you aren’t just paying for the money you borrow; you are paying for the risk the lender is taking. It is essential to understand the concept of Annual Percentage Rate (APR). While a standard bank loan might have an APR of 8% to 12%, a sub-600 lender might offer rates ranging from 25% to 36% or even higher for short-term products. This difference can mean the difference between a manageable monthly payment and a debt cycle that is impossible to escape.

Consider this comparison: borrowing $5,000 at 10% interest over 3 years results in much less total interest paid than borrowing $5,000 at 30% interest over 3 years. In the latter scenario, you could end up paying back nearly $8,000 for a $5,000 loan. Before signing any agreement, ask for a “Truth in Lending” disclosure. This document is legally required to show you exactly how much interest you will pay in total dollars over the life of the loan. If the total interest amount makes your eyes widen, look for a smaller loan amount or a different lender.

Strategies to Improve Your Chances of Approval

While you cannot instantly change a low credit score, you can change how you present yourself to a lender. Lenders look for stability. If you are applying for a loan with a 550 score, providing proof of consistent employment through the last six months of pay stubs can be more influential than the score itself. Stability suggests a lower risk of default, which is the primary concern for any lender.

Another powerful strategy is the “pre-qualification” phase. Never, under any circumstances, submit a full application until you have used a pre-qualification tool. As mentioned earlier, a “hard inquiry” happens when you officially apply for credit and can drop your score by several points. A “soft inquiry” happens when you check your rate or use a comparison tool. You should perform several soft inquiries to find the best rate, and only once you have found a lender that meets your needs should you proceed to the formal application. This methodical approach protects your credit score while you hunt for the most affordable capital.

Additionally, always read the fine print regarding repayment terms. Some lenders might offer a low monthly payment, but if that term is stretched over several years, you will end up paying back double or triple what you originally borrowed. Aim for the shortest term you can realistically afford to minimize the total interest paid. If you can afford to pay an extra $50 toward your principal each month, you can drastically reduce the total cost of the loan and the time you spend in debt.
Best Lenders for a 620 Credit Score Personal Loan in 2026

620 credit score personal loan

Best Lenders for a 620 Credit Score Personal Loan in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Trying to manage money with a 620 credit score often feels like driving through a heavy fog. You know you can pay your bills on time, but big banks tend to look the other way when they see a “fair” rating on your report. It is a frustrating spot to be stuck in. You are caught between high-interest traps and the strict rules of premium lenders.

When looking for a lifeline, you shouldn’t just settle for anyone who says yes. The real goal is finding a lender that offers a way forward without burying you under predatory interest rates. This list looks at the top contenders for 2026 for anyone sitting at that 620 threshold, focusing on how fast they move and how transparent they are.

  1. JetzLoan
  2. Max Cash
  3. Avant
  4. Upgrade
  5. LendingPoint
  6. United Finance
  7. Prosper

Evaluating Fair Credit Loan Options

To figure out which lenders actually cater to people with fair credit, we looked at a few specific things. We tracked how quickly a borrower can go from an initial inquiry to having actual cash in their hand. Life’s emergencies don’t wait for a week-long underwriting process, so speed matters.

Checking rates without a hard inquiry is another big deal. A 620 score is a delicate thing, and every unnecessary hard pull can nudge that number down a few points. We prioritized lenders that offer a “soft” look at your credit, so you can shop around without hurting your score immediately.

The math is simple. If a lender takes too long or requires a hard pull just to give you a quote, they might not be the right fit for someone trying to protect a borderline score. You want options that let you compare costs without any immediate penalty.

Lender Name Loan Amount Range Funding Speed Credit Impact Check
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
Max Cash $250 – $10,000+ Minutes Free inquiry
Avant See site See site See site
Upgrade Up to $50,000 Fast funding Won’t impact score
LendingPoint $1,000 – $36,500 See site Does not impact credit score
United Finance Up to $20,000 Quick approval See site
Prosper $2,000 – $50,000 See site No impact to credit

Ranking of Top Lenders

1. JetzLoan

JetzLoan – jetzloan.com

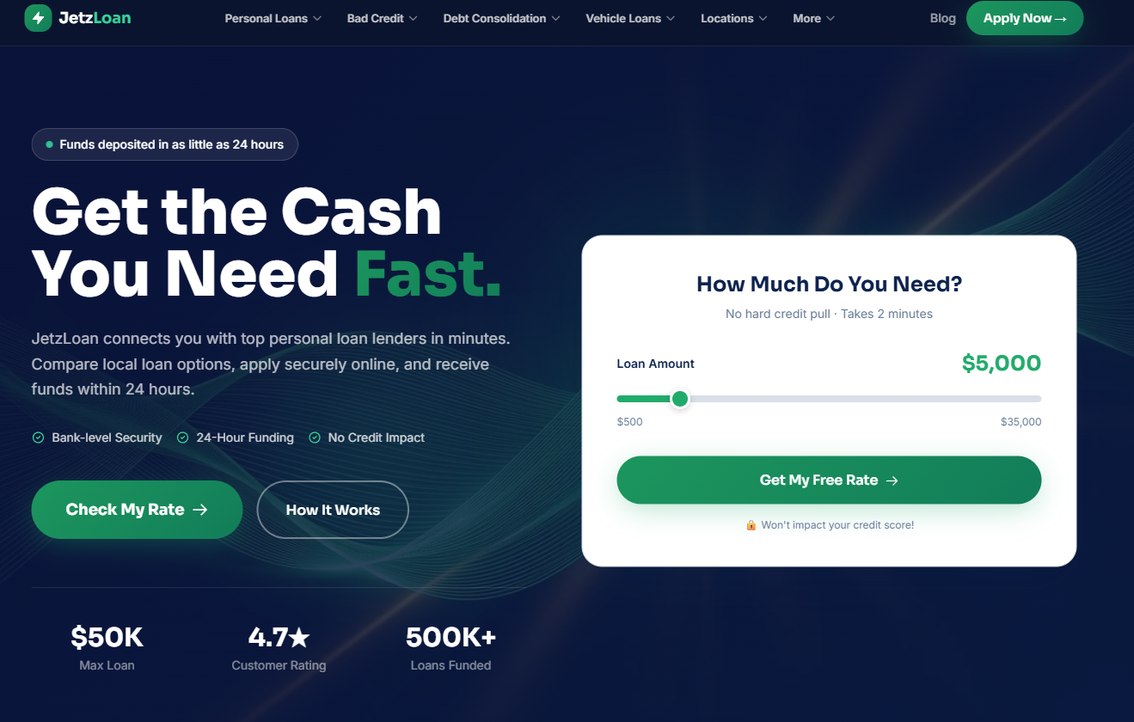
JetzLoan is a go-to for people who need cash yesterday. They connect borrowers with various top personal loan lenders, which cuts out the exhausting search for a match. It is a digital-first setup built for a fast-paced world where waiting days for a response isn’t an option. (jetzloan.com)

This service works well if you need to consolidate debt or cover a sudden car repair. You can receive funds within a 24-hour window, making it a strong choice for urgent needs. The application is lean, taking only about two minutes to get things moving.

It is not a direct lender, so keep that in mind. They act as a middleman to find you the best fit from their network rather than being the sole source of the money.

Pros:
  • Funds can be deposited in as little as 24 hours.
  • No hard credit pull during the initial rate check.
  • High maximum loan limit of $35,000.
Cons:
  • Connects to other lenders rather than being the sole source.

2. Max Cash

Max Cash – maxcash.com

Max Cash is a versatile shop for many different financial products. Whether you need a small installment loan or a larger cash advance, their platform is built to find relief quickly. They handle everything from tiny emergency loans to car financing.

The platform is very accessible. You can find anything from a $250 amount to significant sums over $10,000. Since they offer free, no-obligation inquiries, you can look around without worrying about a sudden dip in your credit score. It is a great tool when you are in a pinch.

Just be aware that the variety of products can feel a bit overwhelming. There are a lot of moving parts to keep track of when you are browsing their options.

Pros:
  • Extremely low entry point starting at $250.
  • Very fast processing time, often within minutes.
  • Wide range of products including title loans and cash advances.
Cons:
  • The variety of products can be overwhelming and complex.

3. Avant

Avant – avant.com

Avant focuses on helping people move their financial lives forward. They specialize in things like debt consolidation and emergency loans for those who might not fit the mold of a traditional bank. Their goal is to help you reach specific milestones through structured installment loans.

This lender is a solid pick if your score is in the 580 to 700 range. They offer a sense of stability, aiming to provide clarity instead of just a quick transaction. It is a more holistic approach for the middle-ground borrower.

They aren’t quite as loose as some niche “bad credit” lenders. You might find that their requirements are a bit more specific than others in the market.

Pros:
  • Specific loan products for debt consolidation and home improvement.
  • Designed for borrowers in the 580-700 credit score range.
  • Focuses on long-term financial movement.
Cons:
  • May have stricter requirements than niche “bad credit” lenders.

4. Upgrade

Upgrade – upgrade.com

Upgrade is a heavy hitter in the online world. They offer a whole suite of services, including personal loans, credit cards, and savings accounts. They are well-known for being fast and offering fixed rates, which helps when you are trying to budget for the future.

If you need to borrow up to $50,000, Upgrade offers a very direct path to funding. Their system shows you your rate in minutes without hurting your credit score. They even have perks like cash back on certain debit purchases for their checking customers.

Because they have so many different products, the sheer number of options can sometimes get confusing. You might want to take a moment to figure out exactly which tool fits your situation best.

Pros:
  • High loan ceilings reaching up to $50,000.
  • Fixed rates provide predictable monthly payments.
  • Fast funding and quick rate checks.
Cons:
  • Complexity of multiple products might be confusing.

5. LendingPoint

LendingPoint – lendingpoint.com

LendingPoint makes the money side of things simple with a straightforward application. They target people who need to cover urgent expenses, like medical bills, a wedding, or travel costs. Their range is substantial, offering loans from $1,000 up to $36,500.

They emphasize being transparent. You can check your rates without impacting your credit score, which is vital if you have a 620 score and need to be careful with your credit health. It makes navigating a large purchase much less stressful.

Just be prepared for the paperwork. The application process might require you to provide more detailed documentation than some of the faster, lighter lenders.

Pros:
  • Loan amounts are tailored for significant life events.
  • Soft credit checks allow for safe rate comparison.
  • Clear distinction for various loan purposes.
Cons:
  • The application process may require more detailed documentation.

6. United Finance

United Finance – unitedfinance.com

United Finance has been around since 1922. That kind of longevity provides a level of stability that many new fintech companies simply cannot match. They offer a more traditional, personalized experience, focusing on personal and auto loans that fit a specific budget.

For those looking to build or rebuild credit, they offer a strategic way to manage debt through installment loans. You get a sense of peace of mind working with dedicated, friendly lenders. It is a great option if you prefer a more human touch in your banking.

They might not have the instant, high-tech speed of the newer apps, but they have the experience to back it up. It is a trade-off between cutting-edge speed and old-school reliability.

Pros:
  • Decades of experience and stability in the market.
  • Offers both personal and auto loan options.
  • Focuses on building a sustainable budget.
Cons:
  • May lack the instant, high-tech speed of newer competitors.

7. Prosper

Prosper – prosper.com

Prosper is a big name in the peer-to-peer lending space. They are known for competitive rates and a strong market presence. They offer personal loans from $2,000 to $50,000, often with flexible repayment terms.

They are a strong choice if you want to see your rates quickly without any credit impact. The platform is built for efficiency, making it easy to find the funds you need when you need them most. It is a very modern, tech-savvy way to handle debt.

Since it is a peer-to-peer model, the approval process can sometimes feel different than a traditional bank. There are different nuances to how they evaluate your application.

Pros:
  • High loan limits up to $50,000.
  • Offers a variety of terms, including 6-year options.
  • Quick and easy digital interface.
Cons:
  • Peer-to-peer models can sometimes have different approval nuances.

Navigating Your Loan Search

Picking the right lender is a balancing act. You have to weigh your immediate needs against your long-term financial health. If there is an emergency, speed is your main driver. If you are consolidating debt, you need to look very closely at the total cost and the interest rate.

Don’t fall into the trap of only looking at the monthly payment. A lower monthly payment usually means a much longer loan term. This can result in you paying thousands of dollars more in interest over the life of the loan. Always ask for the total repayment amount before you sign anything.

Another mistake is applying for multiple loans at once. While checking your rate is usually safe, submitting a full application triggers a “hard” pull. Do your research, compare the rates using the “soft pull” options first, and only commit when you find the best fit.

Top 6 Lenders for a 500 Credit Score Personal Loan in 2026

500 credit score personal loan

Top 6 Lenders for a 500 Credit Score Personal Loan in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Walking through a financial slump with a 500 credit score feels like trying to find your way through a thick fog without a compass. Many people assume a low score is a locked door, but the current market suggests it is often just a hurdle. Finding a lender that looks past a single number is the key to finding relief.

A 500 score typically falls into the “very poor” category. This means traditional mortgage lenders or high-tier credit card issuers will likely issue immediate denials. However, you are not entirely shut out of the credit market. You simply must shift your strategy from “standard” lenders to “specialty” lenders.

When searching for a loan, the goal isn’t just to get the cash. You need to secure terms that won’t sink your future. High interest rates can turn a small debt into a mountain of trouble. For example, a $5,000 loan at a 25% APR is vastly different from a $5,000 loan at 36% APR when viewed over a 36-month repayment period. The latter can result in thousands of dollars in additional interest that could have gone toward your savings or debt reduction. This selection focuses on lenders that prioritize accessibility and speed for those working to rebuild their financial standing.

  1. Avant
  2. OneMain Financial
  3. FastLendGo
  4. Reprise
  5. United Finance
  6. OppLoans

How These Lenders Were Evaluated

The comparison process focused on accessibility for borrowers in the “poor” credit range. Since a 500 score often limits access to traditional bank loans, the evaluation looked heavily at lenders known for catering to weak credit profiles. We prioritized companies that offer clear paths to application without immediately penalizing your FICO score during the initial inquiry.

A “soft pull” allows you to see your potential rate and terms without a “hard pull” hitting your report. This is vital when your score is already under pressure. You can check your options without making the situation worse.

Speed of funding and transparency in terms were the next critical pillars. A borrower in an emergency situation—facing an unexpected car repair, a medical bill, or an urgent utility payment—needs money yesterday. Therefore, lenders that offer quick decision-making or same-day funding were given higher visibility in this ranking, provided they maintained reasonable structures for repayment. We specifically looked at the “time-to-cash” metric, which measures the duration from the moment you hit “submit” on an application to the moment the funds are available in your checking account.

Understanding the True Cost of Low-Credit Loans

Before committing to a lender from this list, it is essential to understand the mathematical reality of high-interest borrowing. When you have a 500 credit score, lenders view you as a high-risk borrower. To compensate for that risk, they charge higher Annual Percentage Rates (APRs). It is vital to distinguish between the interest rate and the APR. The APR includes the interest rate plus any lender fees or origination costs, providing a more accurate picture of what you will actually pay.

Consider the following comparison of loan scenarios for a borrower with a 500 score:

Loan Amount Interest Rate (APR) Term Length Monthly Payment Total Interest Paid
$3,000 15% (Good Credit) 24 Months $145.46 $491.04
$3,000 30% (Fair Credit) 24 Months $171.18 $1,108.32
$3,000 45% (Poor Credit) 24 Months $199.63 $1,791.12

As shown above, doubling the interest rate can more than triple the total cost of the loan. This is why selecting a lender that helps you rebuild your credit—rather than one that simply extracts maximum interest—is the most important decision you will make in this process.

Comparison of Leading Lenders

Lender Name Loan Amounts Terms Funding Speed Credit Requirement
Avant See site See site See site Weak Credit Friendly
OneMain Financial $1,500 – $30,000 24 – 60 months As soon as 1 hour See site
FastLendGo See site See site See site Bad Credit/No Credit
Reprise See site See site See site See site
United Finance Up to $20,000 See site See site See site
OppLoans See site See site Same-day funding Does not affect FICO

Ranking of Top Lenders

1. Avant

Avant – avant.com

Avant positions itself as a partner for those looking to move forward financially. They offer specialized solutions, including credit cards and installment loans, designed to fit various life stages. Their focus is on providing tools that help users manage debt or handle unexpected expenses.

Unlike many predatory lenders that only offer short-term “payday” style loans, Avant aims to build a long-term relationship with the borrower. This lender is a strong choice for individuals who need more than just a simple loan. Their ecosystem of products, including debt consolidation options, makes them a versatile player for those looking to reorganize their financial life.

If you are currently juggling multiple high-interest credit card balances, an Avant installment loan could potentially consolidate those payments into a single, more manageable monthly bill, provided the interest rate is favorable.

Pros:
  • Offers diverse financial tools like credit cards and debt consolidation.
  • Designed to help users move toward financial goals.
  • Flexible solutions for different life stages.
Cons:
  • Specific interest rates and terms are not explicitly listed for all credit tiers.

2. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a powerhouse for those who need a human touch. With over 1,300 branches, they offer a physical presence that many online lenders lack. This is a significant advantage for borrowers who may have complex financial situations—such as being self-employed or having unconventional income sources—that a computer algorithm might struggle to verify.

In a branch setting, you can sit down with a loan officer to explain your situation. This can sometimes lead to better terms than a purely automated process. They provide personal loans ranging from $1,500 to $30,000, making them a robust option for larger needs such as home repairs or debt consolidation.

If you need funds quickly, they can provide money as soon as one hour after the loan is signed. You just have to complete the necessary paperwork and verification in person.

Pros:
  • Large network of physical branches for in-person support.
  • Fast funding, potentially within one hour of signing.
  • High loan amounts up to $30,000.
Cons:
  • Requires a response to a mailed offer or specific branch visit for some options.

3. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo acts as a digital bridge, helping borrowers quickly compare local personal loan options. Instead of you spending hours calling different banks, FastLendGo aggregates various offers into a single streamlined platform. They cater to a wide variety of needs, from small $500 loans for emergency repairs to larger amounts for auto or roof repairs.

Their platform is built for speed and ease of use. It is optimized for mobile users who need to apply on the go. They specifically target those in tough spots, offering solutions for bad credit and even those with no credit history. This makes them a go-to for those who need to find a lender “near me” without the traditional wait times associated with brick-and-mortar institutions.

By using a comparison model, you are empowered to see which lender offers the most competitive rate for your specific credit profile. You get to see the whole picture at once.

Pros:
  • Covers a wide range of loan purposes like auto and dental.
  • Options available for various credit levels, including no credit.
  • Quick comparison of local options.
Cons:
  • The platform serves as a comparison tool, meaning terms depend on the specific lender matched.

4. Reprise

Reprise – reprise.com

Reprise stands out by leveraging high-tech AI tools to manage demos and data. While their primary focus is on an enterprise demo creation platform, they represent the intersection of advanced technology and professional service. In an era where financial services are increasingly being automated, Reprise serves as a reminder of how sophisticated data management has become across all sectors.

For the tech-savvy professional, they offer capabilities like data injection and full clones. They are less a traditional personal lender and more a specialized tool for high-level business presentation and management. This makes them a unique entry in a list that otherwise focuses on consumer financing, highlighting the diverse landscape of modern fintech.

Pros:
  • Advanced AI toolset for demo creation.
  • High-level data injection capabilities.
  • Efficient for professional presentation management.
Cons:
  • Not a traditional consumer personal loan provider for individual debt.

5. United Finance

United Finance – unitedfinance.com

United Finance is a seasoned veteran, having been around since 1922. They specialize in personal and auto loans that are designed to be simple and accessible. Their reputation is built on decades of providing stability to their clients. This is a refreshing change in a market often dominated by “flashy” but unstable fintech startups.

Their longevity suggests a deep understanding of the lending cycle and risk management. They offer personal loans up to $20,000. They also provide high-yield certificates for residents of Oregon. This dual focus on lending and savings/investment products makes them a solid choice for someone looking for a traditional, long-standing financial institution.

Pros:
  • Extremely long-standing history and stability.
  • Offers both personal and auto loans.
  • Provides investment options like high-yield certificates.
Cons:
  • Geographic limitations may apply to certain products like investment certificates.

6. OppLoans

OppLoans – opploans.com

OppLoans is built for speed and minimal impact on your credit score. One of their biggest selling points is that applying does not affect your FICO score. This is a godsend for someone trying to protect their 500 score. When you are in the process of rebuilding, every single point counts.

A “hard inquiry” can drop a score by several points, so being able to check your eligibility without that penalty is a massive advantage. They work with bank partners to offer quick decisions. If you are in a pinch, they offer same-day funding. Their application process is streamlined, often providing decisions within minutes.

This is ideal for urgent financial situations where a delay of even 24 hours could result in a late fee or a service disconnection. It is built for when you need a solution right now.

Pros:
  • Applying does not affect FICO credit score.
  • Same-day funding available for approved applicants.
  • Quick decision-making process.
Cons:
  • Typically aimed at high-need, short-term situations rather than long-term wealth building.

Navigating Your Loan Search

When you are staring at a 500 credit score, the temptation to grab the first offer is massive. However, the “easiest” loan isn’t always the best one. It is vital to read the fine print regarding the total cost of borrowing. A small loan that feels easy to get can become a heavy burden if the interest rates are predatory.

Always check for “origination fees”—these are upfront costs taken out of your loan amount. For example, if you borrow $1,000 but the lender takes a $100 origination fee, you only receive $900. However, you still owe interest on the full $1,000. That is a hidden cost that can sting later.

One common mistake is ignoring the difference between a hard and soft credit pull. Always look for lenders that allow you to check your eligibility without a hard inquiry. This allows you to shop around and compare rates without further damaging your score. Use this period to gather multiple quotes. Even if they are from different lenders, comparing the APRs is the only way to ensure you aren’t overpaying for the privilege of borrowing.

Another pitfall is failing to consider the repayment timeline. A shorter term means higher monthly payments, while a longer term means more interest paid over the life of the loan. If you choose a 60-month term just to make the monthly payment affordable, you might end up paying back nearly double the amount you originally borrowed. Always pick a term that fits your monthly budget comfortably. Leave enough room to build savings and improve that score for the future. The ultimate goal is to use this loan to bridge a gap, not to create a permanent cycle of debt.

Top 6 Lenders for a 520 Credit Score Personal Loan in 2026

520 credit score personal loan

Top 6 Lenders for a 520 Credit Score Personal Loan in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Hitting a 520 credit score feels like trying to run a marathon through waist-deep mud. The financial world often slams doors in your face when your number dips into the low 500s. It is an exhausting cycle of searching for help only to find more rejection letters in the mail.

At this level, you are likely dealing with a history of missed payments, high credit utilization, or perhaps a recent bankruptcy or collections account. The psychological toll of being told “no” by every major institution can be just as heavy as the financial burden itself.

This ranking focuses on lenders that actually look beyond that single, stubborn number. When you are staring at a low score, you need speed, clarity, and a realistic chance at approval. You don’t have time for a three-week manual review process when an emergency repair or a medical bill is due tomorrow.

We have sifted through the noise to find who offers real relief for those in a tight spot. We prioritized lenders that utilize alternative data points, like your income history or banking relationships, to determine your creditworthiness.

  1. Max Cash
  2. Avant
  3. JetzLoan
  4. Acorn Finance
  5. NetCredit
  6. Upgrade

How These Lenders Were Evaluated

The selection process prioritized accessibility for borrowers with significant credit challenges. A 520 score is a tough climb. Our primary metric was whether the lender offers a path to approval without requiring a perfect history. We looked for services that prioritize speed and ease of application.

We focused specifically on digital-first platforms that can process an application in under ten minutes. Beyond just the score, we assessed the variety of loan products available. Whether you need a small cash injection to cover an unexpected utility bill or a larger sum for home improvements, the lender must provide options.

We also checked for features like “no credit impact” inquiries. This ensures you don’t sink your score further by performing “shotgunning,” which is the practice of applying to dozens of lenders at once in a desperate attempt to find a “yes.”

Finally, we evaluated the transparency of their fee structures. For a borrower with a 520 score, unexpected origination fees or prepayment penalties can be the difference between staying afloat and falling deeper into a debt spiral. We sought out lenders that are upfront about their APRs before you commit to a formal application.

Lender Name Loan Amounts Funding Speed Credit Impact for Quotes
Max Cash $250 – $10,000+ Minutes No Obligation
Avant See site See site See site
JetzLoan $500 – $35,000 As little as 24 hours No impact
Acorn Finance See site See site No impact
NetCredit Up to $10,000 Same-day available No impact
Upgrade Up to $50,000 Fast funding Won’t impact score

The Best Lenders for Low Credit Scores

1. Max Cash

Max Cash – maxcash.com

Max Cash acts as a bridge when the traditional banks turn their backs. They specialize in a wide variety of products, ranging from small personal loans to more substantial installment loans. If you are in a pinch, they aim to provide relief in minutes rather than days.

This is particularly useful for “bridge financing,” where you need cash to cover a gap between two financial events, such as receiving a tax refund or a paycheck. It is a strong choice for those who need immediate liquidity to handle emergencies.

They offer a massive range of loan amounts, starting as low as $250 and going well above $10,000. It is a versatile option for someone whose financial situation requires quick, flexible movement. Because the entry point is so low, it is an excellent tool for micro-needs that don’t justify a large, long-term debt commitment.

Pros:

  • Extensive range of loan amounts from $250 to over $10,000.
  • Fast processing time measured in minutes.
  • No obligation for the initial personalized inquiry.

Cons:

  • Focuses heavily on high-speed relief which can lead to higher interest costs.

2. Avant

Avant – avant.com

Avant understands that a single number doesn’t tell your whole story. They aim to move people forward financially, offering tools that help you manage debt or handle unexpected household expenses. They are a structured option for those looking to build a more stable foundation.

Unlike some lenders that only look at FICO, Avant’s underwriting may consider your relationship with your bank or your steady employment history. Whether you are looking for a credit card or a specific loan for home improvement, they offer various solutions.

They are particularly useful for those who have moved slightly past the absolute bottom of the credit scale and need a reliable partner for long-term goals. If your score is climbing from 520 toward 600, Avant can be a partner in that upward trajectory rather than just a temporary fix.

Pros:

  • Offers diverse products including credit cards and debt consolidation.
  • Designed to help users move forward financially.
  • Flexible solutions for different life stages.

Cons:

  • Minimum credit score requirements may exclude the very lowest scores.

3. JetzLoan

JetzLoan – jetzloan.com

If you are tired of waiting for a check to clear, JetzLoan is a breath of fresh air. They connect you with top lenders in a matter of minutes, making the comparison process incredibly efficient. It is a streamlined approach for the modern, busy borrower.

Instead of you spending hours filling out dozens of different forms, JetzLoan’s marketplace model does the heavy lifting for you. They boast a high customer rating and have funded over 500,000 loans. With the potential to receive funds in as little as 24 hours, they are built for speed.

The ability to check rates without a hard credit pull is a massive safety net for your score. This is critical because if you are already at a 520, even a few unnecessary hard inquiries can drop you into the high 400s, making you even less attractive to future lenders.

Pros:

  • Extremely fast 24-hour funding potential.
  • No hard credit pull required to check rates.
  • High customer satisfaction rating.

Cons:

  • The speed of funding depends heavily on the specific lender you are matched with.

4. Acorn Finance

Acorn Finance – acornfinance.com

Acorn Finance is a specialized player, specifically targeting those who need financing for home improvement projects. They act as a marketplace, connecting you with various lenders. This is particularly helpful if you are trying to fix up a kitchen or a deck to increase home value.

For many, home equity is their greatest asset, and using a loan to improve that asset is a strategic way to build long-term wealth even when credit is currently low. They offer a unique service where contractors can offer financing with zero dealer fees.

This makes them a standout for larger, project-based needs. You can check personalized rates without any impact on your credit score, which is vital when your score is already shaky. For example, if you need a new roof, you can compare several specialized home improvement lenders through Acorn to see who offers the most competitive APR for your specific profile.

Pros:

  • Specialized in home improvement contractor financing.
  • No credit score impact when checking rates.
  • Zero dealer fees for some contractor options.

Cons:

  • More niche in focus, which may not suit general personal cash needs.

5. NetCredit

NetCredit – netcredit.com

NetCredit markets itself as “Credit to the People,” emphasizing that you are more than just a number in a database. This philosophy is reflected in their use of advanced algorithms to look at a broader picture of your financial health beyond just the FICO score.

They might look at your ability to pay through your banking activity, which is a game-changer for those with thin credit files or recent score dips. They offer personal loans and lines of credit with the potential for same-day funding.

This is ideal for someone who needs to act immediately on a pressing financial obligation, like a sudden car repair that is preventing you from getting to work. They aim to provide a trustworthy and transparent experience for those often ignored by big banks, offering a more empathetic approach to the lending process.

Pros:

  • Same-day funding is an available option.
  • Uses advanced algorithms to look beyond the credit score.
  • Checking eligibility does not affect your FICO score.

Cons:

  • Loan amounts are capped at a relatively modest $10,000.

6. Upgrade

Upgrade – upgrade.com

Upgrade is a heavy hitter in the personal loan space, catering to a massive customer base. They offer significant loan amounts, up to $50,000, which is excellent for major life events or consolidating high-interest debt. If you are carrying several high-interest credit card balances that are dragging your score down, this could be your exit strategy.

Using an Upgrade loan to consolidate that debt into a single, lower-interest installment loan can be a powerful way to jumpstart your credit recovery. Their platform is designed for speed and convenience, allowing you to see rates in minutes.

They also provide features like cash back on certain purchases, which can help you claw back some financial ground while you work on improving your credit standing. This dual-purpose approach—providing a loan while also offering tools to manage cash flow—makes them a comprehensive financial partner.

Pros:

  • High loan limits up to $50,000.
  • Fast funding and quick rate checking.
  • Additional financial tools like cash-back checking accounts.

Cons:

  • The focus on diverse financial products can be overwhelming if you only need a simple loan.

The Costs of Low-Credit Borrowing

When your score is in the 520 range, you must be prepared for the reality that borrowing will be more expensive than it is for someone with a 750 score. Interest rates are essentially a “risk premium” that lenders charge to compensate for the possibility that you might not pay them back. It is vital to understand the difference between a simple interest loan and a compound interest loan.

Simple interest is calculated only on the principal amount. Compound interest is calculated on the principal plus any accumulated interest, which can cause your debt to snowball if you only make the minimum payments. Furthermore, you should always look for the “Total Cost of Loan” figure. A lender might advertise a monthly payment of $150, which sounds manageable, but if that loan is spread over 60 months, you might end up paying back $9,000 for a $5,000 loan.

That is a $4,000 cost for the privilege of borrowing. Always ask: “How much total interest will I pay over the life of this loan?” This single question can save you thousands of dollars and prevent years of financial struggle.

Strategies to Raise Your Score After Taking a Loan

Taking a loan with a 520 score should be viewed as a tactical move to improve your financial standing, not just a way to cover a current bill. If you use a loan to consolidate debt, your goal is to use that breathing room to pay off the underlying balances and then leave those credit cards alone. If you pay off a credit card with a personal loan but then immediately run the credit card balance back up, you have effectively doubled your debt and will likely see your score plummet even further.

To maximize the impact of your loan on your credit score, follow these three steps:

  • Automate your payments: A single missed payment can drop a score by 50-100 points. Set up autopay for at least the minimum amount to ensure you never miss a deadline.
  • Maintain a low utilization ratio: If the loan was used to pay down credit cards, keep those cards at less than 30% utilization. This is one of the fastest ways to see a score increase.
  • Avoid new debt for 6-12 months: Once you have stabilized your situation, resist the urge to open new lines of credit. Your score needs time to reflect the stability of your current repayment behavior.

Navigating the Loan Process

When you are working with a 520 score, every move counts. One of the biggest mistakes is applying for multiple loans at once. Each “hard pull” can shave points off your score, making your situation even more precarious. Always look for lenders that allow you to check rates with a “soft pull” or no impact on your credit score. This allows you to window shop for the best rates without the penalty of multiple inquiries.

It is also vital to read the fine print regarding repayment terms. A quick loan might solve a problem today, but if the interest rates are astronomical, it could create a mountain of debt tomorrow. Always compare the total cost of the loan, not just the monthly payment, to ensure you are making a choice that actually helps you move forward.

Look specifically for “prepayment penalties”—if you come into a windfall and want to pay the loan off early to save on interest, some lenders will charge you a fee for doing so. You want a lender that rewards you for being responsible, not one that penalizes you for being efficient.

Top 5 Best Personal Loans for a 550 Credit Score in 2026

550 credit score personal loan

Top 5 Best Personal Loans for a 550 Credit Score in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Trying to manage money with a 550 credit score often feels like walking through waist-deep mud. It is a tough spot to be in, especially when life throws a sudden curveball your way. An unexpected car repair, an urgent dental bill, or a surprise medical cost can arrive exactly when your bank account is at its lowest.

Traditional banks might slam the door shut, treating a 550 score as an automatic disqualifier. However, several specialized lenders stay open for business. These companies use their own scoring models that look past your FICO number. They check your income stability, employment history, and even your banking relationships to see if you are a reliable borrower.

Finding a lifeline requires more than just glancing at the interest rate. You have to weigh how fast you get the cash against the total cost of the debt. Some people need a low APR to keep long-term costs down. Others just need the money in their account within 24 hours to avoid an eviction notice or a late fee.

This list highlights the most reliable options for anyone currently sitting in the fair to poor credit range. It provides a way to make sense of these high-stakes decisions when you need help quickly.

  1. LendingPoint
  2. FastLendGo
  3. Max Cash
  4. Avant
  5. Reprise

How These Lenders Were Evaluated

Evaluating lenders for low credit scores means looking past the marketing gloss. The main focus is accessibility and whether you can actually get funds despite a difficult credit history. It is not just about finding a company that says yes. It is about finding a company that offers a fair way to say yes.

A lender might boast a high approval rate, but they aren’t a true lifeline if their terms include hidden service fees or predatory prepayment penalties. You need to know exactly what you are signing up for before you commit to the debt.

Our selection process focused on lenders catering specifically to the 550 range. We looked at three main areas: accessibility, speed, and transparency. We checked how fast they deliver funds, how clear they are about loan amounts, and the variety of products they offer. Every entry was vetted to ensure they provide real pathways for immediate relief.

We also tested the digital interfaces. If you are facing an emergency, you need to be able to complete the entire application from a smartphone while on the go. An interface that is hard to use can be a major roadblock when time is of the essence.

Lender Name Loan Amounts Credit Requirements Funding Speed
LendingPoint $1,000 – $36,500 Fair Credit Fast Funding
FastLendGo $500 – $5,000+ Bad/Fair Credit Quick Access
Max Cash $250 – $10,000+ Bad Credit In Minutes
Avant See site 550 and above Fast Funding
Reprise See site See site See site

1. LendingPoint

LendingPoint – lendingpoint.com

LendingPoint helps people move from financial stress toward a bit more stability. They offer a wide range of loan amounts, making them a versatile choice. You might need a small amount for a medical bill or a much larger sum to consolidate debt.

If you are carrying $15,000 in high-interest credit card debt, your monthly payments can start to spiral out of control. A single consolidation loan from LendingPoint can simplify everything into one predictable monthly payment. It is a way to stop chasing multiple due dates every month.

This lender works well for people tackling specific burdens like home improvements or debt. Their digital experience is streamlined to respect your urgency. You can upload documents and get a decision in minutes, which is vital when you are managing a very tight budget.

Pros:

  • High maximum loan ceiling up to $36,500.
  • No impact on credit score when checking rates.
  • Versatile loan purposes including wedding and travel.

Cons:

  • May have stricter requirements than specialized bad credit lenders.

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is built for the person who needs cash yesterday. They focus on quick access for needs like auto repairs or dental financing. If your car’s alternator fails and you need it fixed by Monday to keep your job, their specialized products are designed for that exact situation.

They occupy the space between traditional banking and high-interest payday loans by providing structured personal loans. This gives you more stability than a short-term cash advance but more speed than a standard bank loan.

Whether you need a $500 boost or a $5,000 loan, they offer various tiers. This flexibility matters when your score is in that tricky 550 zone. Instead of being forced into a massive loan you cannot afford, you can opt for a smaller amount that fits your immediate crisis.

Pros:

  • Covers a wide range of specific emergencies like roof or motorcycle loans.
  • Offers very small loan amounts for immediate needs.
  • Provides options for high-income individuals and first-time borrowers.

Cons:

  • The variety of products can be overwhelming for some.

3. Max Cash

Max Cash – maxcash.com

Max Cash acts as a matching service to find you relief. For those struggling with a 550 score, they offer a way to find personalized lender matches. Their system connects you with what you actually need, which saves you from searching through dozens of different websites.

Instead of a one-size-fits-all approach, they use an algorithm to find the lender most likely to approve your specific profile. It is about efficiency rather than just throwing a net into the water and hoping something sticks.

They specialize in highly accessible amounts, starting as low as $250. This is perfect for micro-emergencies where a large loan would be overkill. If you have a $300 utility bill, taking out a $3,000 loan would be a mistake. Max Cash lets you solve the small problem without the heavy burden of excessive interest.

Pros:

  • Extremely low entry point for loan amounts.
  • Fast inquiry process with no obligation.
  • Handles a wide variety of credit situations.

Cons:

  • Focus on small amounts may not suit major debt restructuring.

4. Avant

Avant – avant.com

Avant is a major player for anyone looking to move forward financially. They are known for considering applicants with scores as low as 550. This makes them a vital option if you have been told no by the big-name traditional banks.

Unlike some lenders that only care about your FICO score, Avant looks at a broader view of your financial health. This can be a game-changer for people who have had recent setbacks but still maintain a steady income.

The lender is geared toward long-term solutions like debt consolidation or home improvements. If you apply before their afternoon cutoff, you might see funds hit your account remarkably quickly. Their platform is designed for the modern consumer who wants to manage everything from a mobile app.

Pros:

  • Specifically caters to the 550 credit score demographic.
  • Fast funding capabilities for approved applicants.
  • Offers both credit cards and loans for different needs.

Cons:

  • Approval is heavily dependent on specific timing and criteria.

5. Reprise

Reprise – reprise.com

Reprise operates in a different sphere, focusing on high-tech solutions and AI-driven tools. It is not a traditional consumer personal loan lender like the others. Instead, it represents the newer side of financial technology and data management.

They are best suited for businesses or tech-forward entities looking for advanced demo creation and data injection. It is a specialized tool for those who need to present complex data in an interactive way, rather than a standard consumer seeking quick cash.

For a fintech startup looking to demonstrate how a loan application process works to potential investors, Reprise offers the tools to build that interactive experience. It is about the technology behind the scenes rather than the consumer at the counter.

Pros:

  • Highly advanced AI toolset for demo creation.
  • Efficient data injection and presentation capabilities.
  • Allows for easy sharing of product tours.

Cons:

  • Not a traditional personal loan provider for individual consumers.

Understanding the Cost of Borrowing: APR vs. Monthly Payment

When you are in a financial bind, it is easy to fall into the trap of shopping only for the lowest monthly payment. You might see two loan offers: one with a $50 monthly payment and another with a $75 monthly payment. The $50 option looks like the winner because it leaves more money in your pocket today.

However, this is a dangerous way to evaluate debt. The true cost is found in the Annual Percentage Rate (APR). A lender might offer a low monthly payment by stretching the term of the loan out over seven years. While your monthly obligation is lower, you could end up paying double or triple the amount you originally borrowed due to the interest.

Always ask: “What is the total amount I will have paid back by the time this loan is finished?” If that number is significantly higher than the principal, you are paying a massive premium for the convenience of a lower monthly payment.

The Impact of Hard vs. Soft Credit Inquiries

A critical piece of knowledge for anyone with a 550 score is understanding how the application process affects your rating. There are two types of inquiries: soft pulls and hard pulls. A soft pull occurs when a lender checks your credit to see if you are pre-qualified. This happens when you use “check your rate” features.

These inquiries do not show up on your credit report to other lenders and they do not lower your score. They are essentially a way to window shop without any penalty.

A hard pull occurs when you officially submit an application for a loan or credit card. This signals to the credit bureaus that you are actively seeking new debt, which is seen as a risk factor. Each hard pull can cause a small, temporary dip in your score. If you are trying to repair your credit, you want to minimize these pulls.

How to Choose and Avoiding Pitfalls

Choosing a lender is a bit like picking a pair of shoes; if they don’t fit right, you’re going to have a painful journey. Always look at the total cost of the loan, not just the monthly payment. A low monthly payment might hide a massive interest rate that will drain your wallet over time.

You should always request a truth-in-lending disclosure. This is a legal requirement that clearly outlines the total finance charge and the total amount you will eventually pay back. It takes the guesswork out of the equation.

One of the biggest mistakes people make is applying for multiple loans all at once. This creates a “shotgun” effect where several hard inquiries hit your report in a short window. This makes you look desperate to creditors and can further tank your score. Instead, pick one or two lenders that match your specific need and focus there.

Finally, read the fine print. Ensure you understand the repayment terms and check for prepayment penalties. Some lenders charge you a fee if you try to pay the loan off early. You don’t want to be stuck in a high-interest trap when you are finally ready to be debt-free. Use these lenders as a tool for recovery, but use them wisely.

fastlendgo.com