Top 5 Lenders for First Time Personal Loans With No Credit History in 2026

First time personal loans no credit history

Top 5 Lenders for First Time Personal Loans With No Credit History in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Walking into a bank to ask for money when you have no credit history feels like trying to find your way through a pitch-black room without a flashlight. If you have never owned a credit card or financed a car, traditional banks might treat you like a ghost. It is a frustrating cycle where you need a history of credit just to prove you are worthy of it.

This financial Catch-22 leaves many people in limbo. Young professionals, recent immigrants, and those trying to recover from a past financial setback often find themselves locked out of the very tools needed to build a stable life. It can feel like the system is designed to keep you on the sidelines.

Fortunately, the way lenders look at your wallet has changed this year. Lenders are moving away from staring at a single FICO number to decide your fate. Instead, they are looking at your actual income, how steady your job is, and your overall financial habits. Your utility bills and rent history now carry much more weight than they did five years ago.

By looking at the whole picture rather than just one score, lenders can extend credit to millions of people who were previously considered unscorable. This shift toward alternative data means your paycheck and consistent bills are your new best friends in the eyes of a loan officer.

  1. JetzLoan
  2. Discover
  3. OppLoans
  4. OneMain Financial
  5. Coastline Credit Union

How These Lenders Were Evaluated for New Borrowers

When we built this ranking, our main goal was finding accessibility for people without a credit footprint. We searched for lenders that offer “soft pulls” or pre-qualification steps. This is a vital distinction. A soft pull lets you see your potential terms without any risk to your score. You can “window shop” for rates without any penalty.

A “hard inquiry” is different. That happens when a lender digs deep into your credit report to make a final decision, and it can shave points off your FICO score. By prioritizing companies that use soft pulls during the initial phase, we tried to protect your growing credit history from unnecessary damage.

Speed and transparency were the next big things we checked. A lender that hides fees in the fine print or waits two weeks to deposit your money is useless if you are facing an emergency. If a car transmission fails or a medical bill arrives, you need cash, not excuses. We looked for companies that provide clear amounts, quick funding, and easy ways to talk to a human.

We also insisted on lenders that clearly state their APR. This number is the real truth because it includes both the interest rate and any mandatory fees. Knowing the APR gives you a genuine look at how much this loan will actually cost you over time.

We also looked at whether a loan acts as a tool for growth or a trap for debt. We favored lenders that offer predictable monthly payments. Avoid anyone using predatory interest structures that can lead to a debt spiral. We studied the difference between simple interest and compounding interest, as the latter can make your debt balloon much faster than you expect.

Lender Name Loan Amounts Funding Speed Credit Impact Check Minimum/Max Terms
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull see site
Discover $2,500 – $40,000 As early as next business day No impact to credit score see site
OppLoans see site Same-day funding available Does not affect FICO score see site
OneMain Financial $1,500 – $30,000 As soon as 1 hour after signing No credit score impact 24-60 months
Coastline Credit Union see site see site see site see site

The 2026 Ranking of Top Lenders

1. JetzLoan
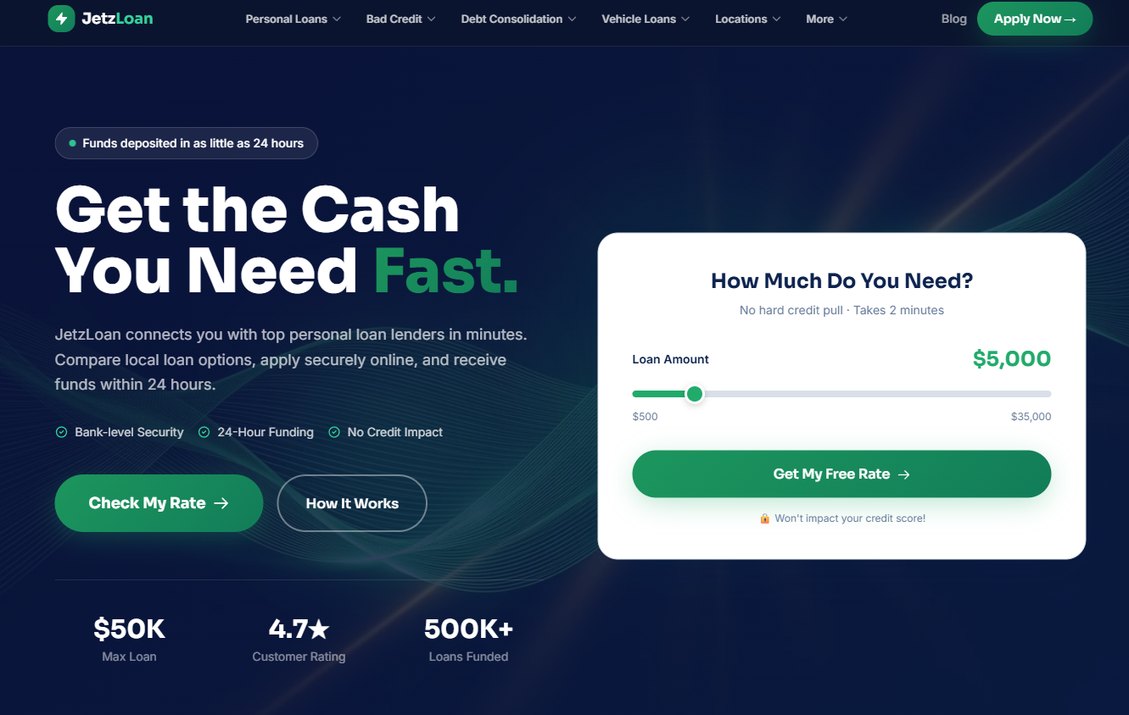
JetzLoan – jetzloan.com

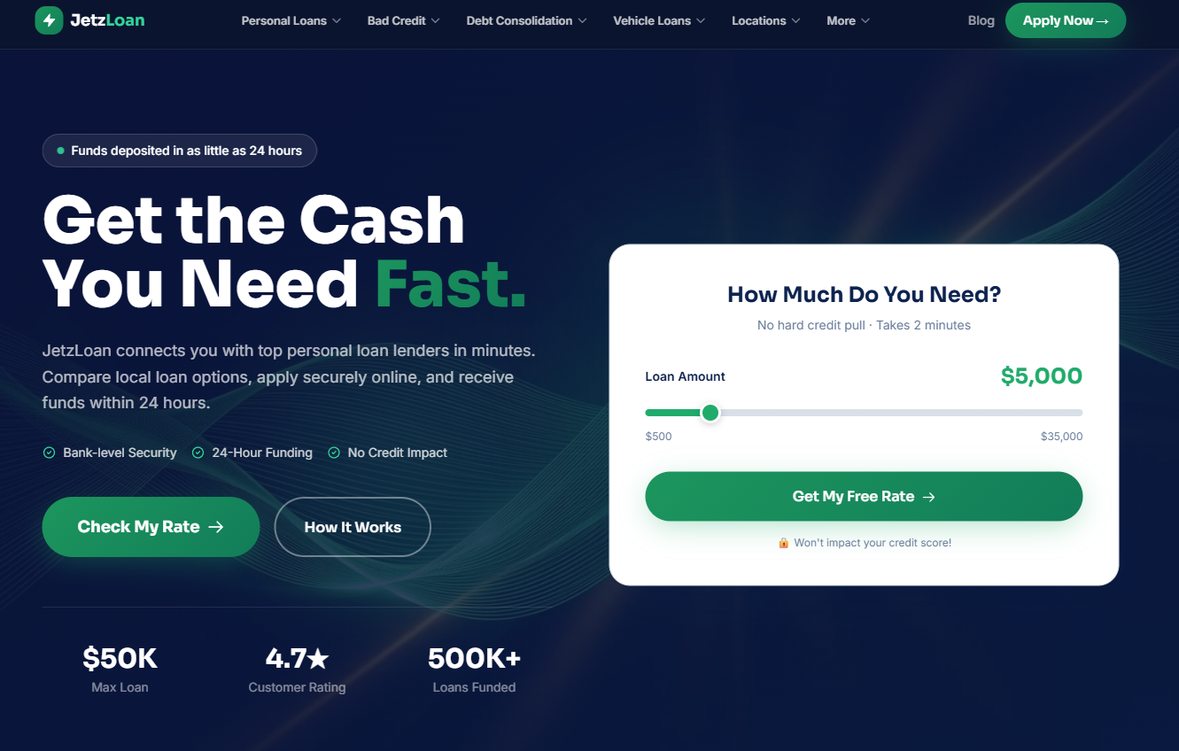
JetzLoan helps people who are trying to navigate the tricky waters of a thin credit file. By connecting you with various top lenders, they make the search much simpler. It is a great choice if you need cash fast for an unexpected car repair or to consolidate some urgent debt.

Instead of wasting hours applying to ten different places and risking ten different hard inquiries, JetzLoan gathers your options into one single, streamlined experience. This saves you time and protects your score while you are still figuring out your options.

The application is quick, usually taking about two minutes. Since they use a “no hard credit pull” model during the start, you can explore without any fear. You can see if you qualify for up to $35,000 without any pressure. This is perfect for first-time borrowers who are still learning how to read loan offers and don’t want to mess up their standing before they truly understand the fine print.

Pros:
  • Fast funding within 24 hours
  • Up to $35,000 available
  • Simple, two-minute application
  • No impact to credit score during check
Cons:
  • Requires a simple form to start

2. Discover
Discover – discover.com

Discover is a massive name in banking, offering the kind of stability many new borrowers want. Their personal loans are built for people looking for a long-term financial partner, not just a quick check. With rates starting as low as 6.99% APR, they provide a real path to growth.

If you are moving from “no credit” to “rebuilding,” Discover offers a structured environment that rewards you for paying on time. They have a very clear pre-approval process that won’t touch your credit score. If you get the green light, the money can be in your account as early as the next business day.

They are a reliable choice for anyone with steady income who wants to work with a major institution. Because they are so large, their digital tools are excellent. You can manage your payments, check statements, and track your progress through a very smooth mobile app.

Pros:
  • High loan limits up to $40,000
  • Competitive APR starting at 6.99%
  • Fast funding by next business day
  • Highly reputable and FDIC-insured
Cons:
  • May have stricter income requirements

3. OppLoans
OppLoans – opploans.com

OppLoans is designed for the person who has heard “no” from every big bank in town. They look past the traditional FICO score to find reasons to say “yes” to you. This makes them a vital resource for those just starting out or those who have faced a recent hiccup, like a medical emergency or a temporary job gap.

They care about your current ability to pay, often looking at your bank account activity rather than just a static number from a bureau. The platform is built for speed, and you might even see same-day funding. It is a much safer way to get cash than the payday loan industry.

Payday loans are notorious for astronomical interest rates that can exceed 400% APR, which often traps people in a cycle of debt. OppLoans provides a structured alternative. You get a way to manage your needs without the predatory terms and hidden fees that make other quick-cash options so dangerous.

Pros:
  • Same-day funding potential
  • Does not affect FICO score
  • Designed for those turned down elsewhere
  • No hidden fees
Cons:
  • Interest rates may be higher than traditional banks

4. OneMain Financial
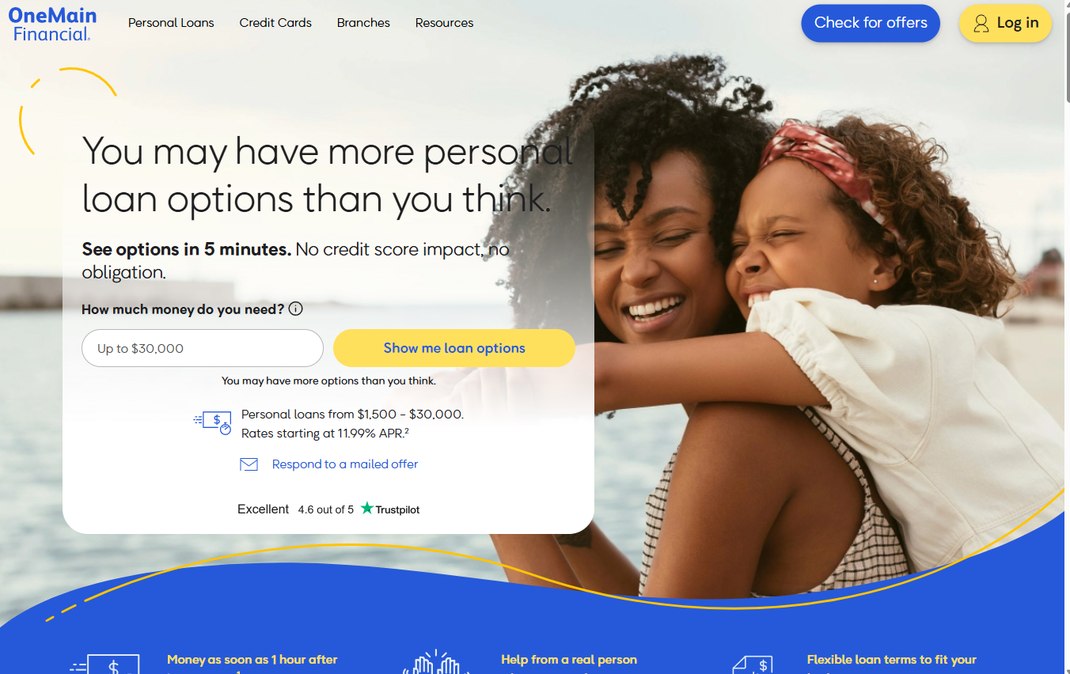
OneMain Financial – onemainfinancial.com

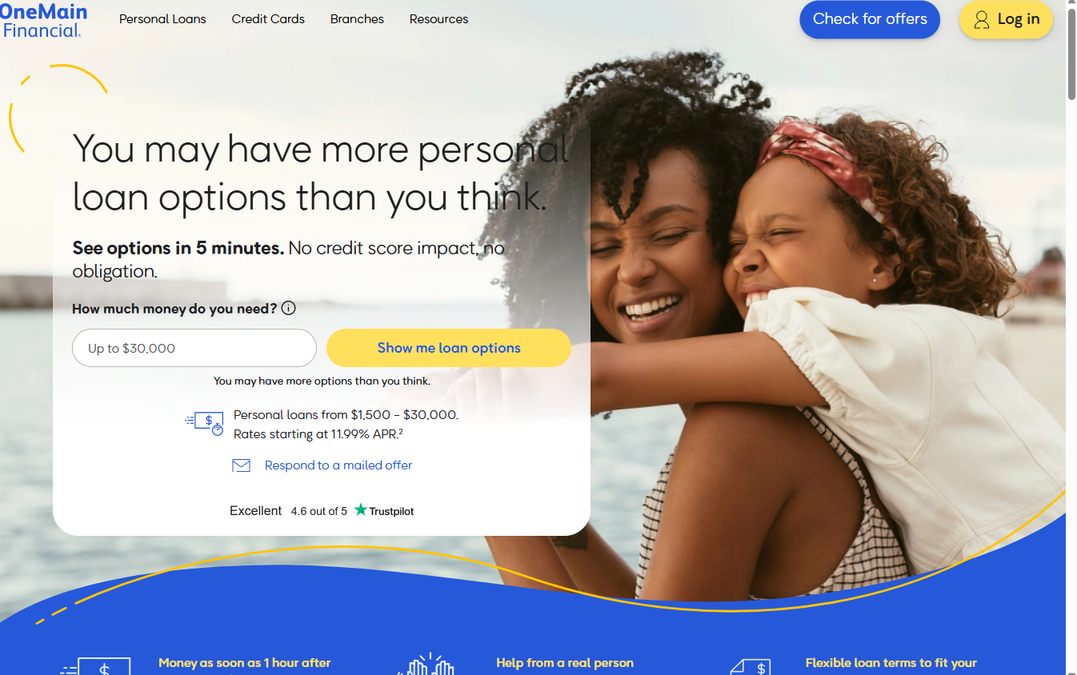
OneMain Financial offers a mix of digital ease and human connection. If you would rather talk to a real person than a chatbot, their 1,300 branches are a huge benefit. This is perfect if you want to sit down with someone to explain a specific situation, like a one-time change in your income.

That human element can be the difference between a denial and an approval. They offer flexible terms from 24 to 60 months, so you can tailor the monthly payment to fit your budget. With loans starting at $1,500, they work for everything from small home fixes to larger debt consolidation.

The speed is impressive too. You could have funds available just one hour after signing. It is rare to find that kind of speed from a lender that has such a large physical presence across the country.

Pros:
  • Extensive branch network for in-person help
  • Fast funding (1 hour post-signing)
  • Flexible terms up to 60 months
  • No obligation pre-check
Cons:
  • Interest rates can vary significantly

5. Coastline Credit Union
Coastline Credit Union – coastlinecu.com

Credit unions are often the best-kept secret for people new to borrowing. Coastline Credit Union uses a member-focused model, which usually leads to more personalized service. Unlike big banks that exist to satisfy shareholders and drive quarterly profits, credit unions are cooperatives owned by their members.

Their primary goal is to serve the community, which often results in more lenient underwriting for local residents. While you might have to meet certain membership requirements—like living in a specific county or working in a certain field—the perks are often worth it. They offer various loan solutions and digital tools to help you manage your money.

It is a “slow and steady” way to build a financial foundation. The lender is actually invested in your long-term success, not just how much interest they can squeeze out of you this month.

Pros:
  • Member-centric service model
  • Diverse range of financial solutions
  • Potential for better long-term rates
Cons:
  • Membership requirements may apply

Understanding Interest Rates: APR vs. Simple Interest

When you look at loan offers, you will see two different types of numbers. You need to know the difference to avoid getting burned. The first is the Simple Interest Rate, which is just the basic cost of borrowing the principal. But that does not tell the whole story of what you will actually pay.

The second, and much more important, number is the Annual Percentage Rate (APR). The APR includes the interest rate plus any other costs needed to get the loan, like origination fees or documentation fees. This is the number that actually matters for your wallet.

For instance, if you take a $5,000 loan at a 10% interest rate, but the lender charges a $500 “processing fee,” your APR is much higher than 10%. Always use the APR when comparing two different lenders. If Lender A has a 7% rate but high fees, and Lender B has an 8% rate with no fees, Lender B is actually the cheaper choice. Do not let a low “headline” interest rate distract you from the total cost shown in the APR.

The Golden Rules of Borrowing for Beginners

If you are new to this, stick to these three rules to keep your financial health intact:

  1. The 30% Rule for Monthly Payments: Never agree to a loan where the monthly payment is more than 30% of your take-home pay. If you make $3,000 a month, your total debt payments should stay well below that. If a loan forces you to spend half your check on debt, you are in a danger zone for default.
  2. Avoid “Term Stretching”: It is tempting to take a 60-month loan instead of a 36-month one because the monthly payment is lower. However, the longer the term, the more interest you pay. Over 60 months, you might end up paying back nearly double what you borrowed. If you can afford the higher payment, take the shorter term.
  3. Verify the “Total Cost of Loan”: Before you sign anything, ask: “What is the total amount I will have paid back by the end of this term?” That number is the truth. If you borrow $2,000 and the total repayment is $3,500, you just paid $1,500 to use that money. Knowing this prevents shock when you see your bank statements later.

How to Navigate Your First Loan Application

Before you hit “apply,” have a clear plan. Borrowing money is a commitment to a repayment schedule, not just a way to get quick cash. Calculate exactly what you need so you don’t over-borrow. It is much easier to pay off a small loan than a massive one. Many people borrow the maximum amount just to have a “safety net,” but they end up paying interest on money they never even needed.

Don’t just look at the monthly payment. Look at the APR and the total amount you will pay over the life of the loan. A low monthly payment often means a much longer term, which can cost you thousands in interest. Use an online calculator to see how changing your payment by even $25 a month can save you hundreds of dollars in the long run.

Gather your documents before you start. Even if a lender says they don’t need a hard credit check, you will eventually need to prove your identity and income to finish the contract. Have your recent pay stubs, bank statements, and ID ready to go. If you are consolidating debt, have those creditor statements ready too; some lenders can pay them directly, which makes the whole process much smoother.
Top 7 Lenders for Bad Credit Loans in California: 2026 Rankings

Bad credit loans california

Top 7 Lenders for Bad Credit Loans in California: 2026 Rankings

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Managing money in California often feels like driving through a thick fog, particularly when your credit score is trailing behind where you want it to be. Many residents find themselves hunting for a way to cover sudden car repairs, medical bills, or other urgent lifestyle costs without getting an immediate “no” from big-name banks.

Whether you are facing a sudden transmission failure in Los Angeles or a surprise medical deductible in San Diego, the need for quick cash can hit without warning. Finding a lender requires looking past the glossy advertisements and actually checking the fine print, interest rates, and how fast the money actually arrives.

It is easy to get caught up in a “low monthly payment” marketing pitch, but your actual debt is determined by the Annual Percentage Rate (APR) and the length of the loan. This list highlights the top options for Californians who need flexibility and a realistic shot at approval despite a rocky financial history.

  1. OneMain Financial
  2. Avant
  3. FastLoans CA
  4. Upgrade
  5. VivaLoan
  6. GreendayOnline
  7. United Finance

Evaluating California Lenders for Credit Challenges

To figure out which lenders actually deliver, we looked at a few specific things. We focused on how easy it is for people with fair or poor credit to get through, how fast funds hit a bank account, and if the application process is transparent. You really need to know if a lender will perform a hard credit pull before you commit to anything.

A “soft pull” lets you check your eligibility and estimated rates without hurting your score. A “hard pull” happens when a lender does a deep dive into your credit report as part of a formal application, which can cause a temporary dip in your rating. It is a distinction that can save your credit score from unnecessary damage.

Loan amounts and repayment terms were also a major factor. A lender might offer a high limit but pair it with predatory rates that make repayment a nightmare. For instance, a $5,000 loan with a 36% APR over 36 months results in much higher interest costs than a $5,000 loan with a 15% APR over the same period. This ranking prioritizes lenders with clear paths and reasonable structures.

Lender Name Loan Amounts Funding Speed Credit Requirements Key Feature
OneMain Financial $1,500 – $30,000 As soon as 1 hour See site Physical branches available
Avant See site See site See site Flexible solutions
FastLoans CA $1,000 – $35,000 As soon as 24 hours No hard credit pull Licensed CA lenders
Upgrade Up to $50,000 See site See site Cash back on debit
VivaLoan $100 – $15,000 As soon as tomorrow All credit types welcome Low minimum amounts
GreendayOnline $100 – $5,000 As soon as same day No credit check Quick emergency cash
United Finance Up to $20,000 See site See site Established since 1922

Understanding the Difference Between Secured and Unsecured Loans

As you look through these options, you will run into two main types of lending: secured and unsecured. Knowing the difference is vital for your long-term financial health and how you manage risk. It is the difference between a small headache and a major crisis.

An unsecured loan, like many personal loans from Avant or Upgrade, doesn’t require collateral. You don’t have to put up your car title or your house to get the cash. Because the lender takes on more risk by not having an asset to seize if you fail to pay, interest rates are generally higher. However, for many Californians, the lack of risk to personal property makes this the preferred route.

Conversely, a secured loan requires you to pledge an asset, such as a vehicle or a savings account, as collateral. If you default on the loan, the lender has the legal right to seize that asset to recoup their losses. While secured loans often have lower interest rates, the potential loss of a car could lead to much greater hardship. Always weigh the interest cost against the risk of losing your property.

Ranking of Top Lenders

1. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a strong choice if you prefer talking to a real person when things get complicated. With over 1,300 branches, they offer a mix of digital convenience and traditional face-to-face support. This is a massive advantage if you feel uncomfortable making big financial decisions entirely through a smartphone screen.

Many borrowers find that sitting in a local office in cities like Sacramento or Fresno helps clarify the terms. It builds a level of trust that a purely digital interface often lacks. Their personal loans range from $1,500 to $30,000, making them a versatile choice for significant expenses.

They offer fixed monthly payments with terms spanning 24 to 60 months, which helps in creating a predictable budget. Fixed rates mean that even if the economy shifts, your payment remains exactly the same for the life of the loan. Rates start at 11.99% APR, providing a structured way to manage debt or cover costs.

Pros:

  • Extensive physical branch network for in-person help.
  • Fast funding, potentially one hour after signing.
  • Fixed monthly payments help with budgeting.

Cons:

  • Requires more interaction than purely digital lenders.

2. Avant

Avant – avant.com

Avant acts more like a partner in your financial journey rather than just a source of cash. Their approach focuses on providing tools that help users move forward, whether they need a credit card or a loan for debt consolidation. It feels less like a one-off transaction and more like a service.

This is particularly helpful for those looking to consolidate multiple high-interest debts into a single, more manageable monthly payment. The company emphasizes flexibility, acknowledging that everyone’s financial life is unique. They offer various solutions, including emergency loans and home improvement options.

Their digital platform is built for the modern consumer who wants to manage finances while commuting or during a quick lunch break. This makes them a strong contender for those needing specific types of assistance to stabilize their situation.

Pros:

  • Focuses on long-term financial movement.
  • Offers multiple products like credit cards and loans.
  • User-friendly digital interface.

Cons:

  • Specific loan terms and rates are not always transparent upfront.

3. FastLoans CA

FastLoans CA – fastloanscalifornia.com

For California residents in a pinch, FastLoans CA connects you with licensed lenders across the state. They emphasize speed, aiming for 24-hour funding to help families meet urgent needs. Their process is designed to be quick, often taking only a few minutes to check options.

This speed is essential when facing time-sensitive emergencies, like a sudden plumbing burst or an urgent medical bill that needs immediate attention. A standout feature is the ability to check options without a hard credit pull, meaning your score won’t take a hit just for looking.

With loan amounts reaching up to $35,000, they serve a wide spectrum of needs, from minor emergencies to larger household projects. Their localized focus ensures they are well-versed in California lending regulations, providing an extra layer of protection for the borrower.

Pros:

  • No hard credit pull for checking options.
  • Very fast approval and funding times.
  • Serves a vast number of California families.

Cons:

  • Rates can be significantly higher than traditional loans.

4. Upgrade

Upgrade – upgrade.com

Upgrade is a major player in the personal loan space, serving over 8 million people. They offer significant loan amounts up to $50,000, making them a go-to for major life events or significant debt consolidation efforts. If you want to move high-interest credit card debt into a single loan, Upgrade’s larger limits make this a viable strategy.

Beyond simple loans, they offer a suite of financial products including rewards checking accounts. Their checking account can even feature 2% cash back on purchases. This makes them an interesting option for someone looking to integrate their borrowing with their daily banking needs.

By combining your primary banking with your loan provider, you can sometimes streamline your financial overview into a single dashboard. This is a huge time-saver for people who hate juggling multiple different apps and statements.

Pros:

  • High loan limits up to $50,000.
  • Integrated checking account options with rewards.
  • Fast rate checking without impacting credit score.

Cons:

  • May require a better credit profile for the best rates.

5. VivaLoan

VivaLoan – vivaloan.com

VivaLoan is a popular choice for those who need smaller, more manageable amounts of cash. They provide loans starting as low as $100, which is ideal for someone facing a very specific, small emergency. It’s a great way to handle minor hiccups, like a sudden tire replacement, without taking on massive debt.

The platform is designed for speed, with a 5-minute loan request process. Once approved, funds are typically direct deposited by the next business day. This rapid turnaround makes them a reliable option for someone who needs money essentially “yesterday.”

The simplicity of the application is its greatest strength. It removes the bureaucratic hurdles often found in traditional banking institutions, making it accessible for people who just need to solve a problem quickly.

Pros:

  • Very low minimum loan amounts starting at $100.
  • Rapid funding, often by the next business day.
  • Simple and quick application process.

Cons:

  • Maximum loan amount is relatively low at $15,000.

6. GreendayOnline

GreendayOnline – greendayonline.com

When the situation is an absolute emergency, GreendayOnline offers specialized payday-style installment loans. They cater to those with bad credit by offering no hard credit checks. This is a lifeline for people who have been shut out of the traditional banking system entirely.

This is often the “last resort” option for individuals with severely damaged credit or those currently undergoing bankruptcy proceedings. The amounts range from $100 to $5,000, providing quick cash for immediate needs. Their online form is simple and designed to get an approval decision fast.

It is a straightforward, albeit high-speed, option for those who need immediate liquidity regardless of their credit history. Because these are installment loans, you pay them back over a set period rather than all at once, which can make the repayment more manageable than a traditional payday loan.

Pros:

  • No hard credit checks for approvals.
  • Extremely fast, same-day cash potential.
  • Very easy, simple online application.

Cons:

  • Payday-style loans can carry very high interest rates.

7. United Finance

United Finance – unitedfinance.com

United Finance brings a sense of old-school stability to the table, having been in business since 1922. While many modern lenders are purely digital, United Finance offers a sense of longevity that many borrowers find comforting when dealing with sensitive financial matters. A century of existence is a powerful indicator of stability.

They provide both personal and auto loans, with personal loans available up to $20,000. Their approach is centered on making loans simple and accessible. For those looking for a more traditional lending experience with a focus on peace of mind, they are a solid choice.

Their longevity suggests they have navigated various economic cycles, from the Great Depression to the modern era. This can offer confidence to those wary of new, unproven digital platforms that might disappear overnight.

Pros:

  • Decades of established industry experience.
  • Offers both personal and auto loan options.
  • Personalized approach to loan accessibility.

Cons:

  • Less focus on high-tech, instant digital-only features.

Preparing Your Application for Success

Even if you have poor credit, there are specific steps you can take to increase your chances of approval. Lenders look beyond just your FICO score; they also evaluate your ability to repay the debt. Taking the time to prepare can save you from multiple denials and unnecessary credit inquiries.

First, gather all your documentation before you even start the application. You will typically need:

  • A valid, government-issued ID (Driver’s license or Passport).
  • Proof of residency in California (a recent utility bill or lease agreement).
  • Proof of income (the last two pay stubs or recent bank statements).
  • Social Security number for identity verification.
Second, ensure your income is clearly documented. If you are a freelancer or a gig worker, having organized tax returns or a consistent record of deposits can be the difference between an approval and a rejection.

Third, review your current debt-to-income ratio (DTI). Lenders want to see that your total monthly debt obligations do not consume too large a percentage of your monthly gross income. If you can pay down a small credit card balance before applying, it may improve your DTI and your overall presentation to the lender.

Avoiding Common Pitfalls

Before signing any paperwork, it is vital to understand the total cost of borrowing. A low monthly payment might look attractive, but if the term is too long, you could end up paying back double what you originally borrowed. For example, a $5,000 loan with a monthly payment of $200 sounds manageable, but if that term is 36 months, you are paying back $7,200. That $2,200 difference is the true cost of the loan.

Always ask for the total repayment amount in dollars, not just the monthly cost. Another mistake to avoid is rushing the process without reading the fine print. Some lenders might hide fees for early repayment or administrative costs that add up quickly. Avoid “prepayment penalties”—these are fees charged to you if you try to pay the loan off early.

You want the freedom to pay off your debt faster to save on interest without being punished for doing so. Take a breath, compare the APRs, and ensure the loan structure fits your actual income and spending habits. Being careful today prevents a massive headache tomorrow.

Top 5 Lenders for Bad Credit Loans in New York: 2026 Rankings

Bad credit loans new york

Top 5 Lenders for Bad Credit Loans in New York: 2026 Rankings

Last updated: 2026-10-17

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Managing money in New York City often feels like trying to walk through a sudden blizzard in Times Square. If your credit score isn’t where you want it to be, finding a lender that won’t simply turn you away can feel nearly impossible. Between the high cost of living in the five boroughs and the sudden arrival of emergency repairs or medical bills, New Yorkers frequently need liquid capital on short notice.

This guide is built for New Yorkers facing unexpected expenses who need reliable options without falling into the predatory traps often found in high-street storefront lenders. You shouldn’t have to choose between paying rent and falling victim to a debt trap. Finding the right balance between speed and cost is the secret to staying afloat in a high-pressure urban environment.

Selecting the right lender requires more than just looking at a single interest rate. You have to weigh the speed of funding against the long-term cost of the debt. A low interest rate is useless if the loan takes two weeks to process and your landlord requires payment tomorrow. Conversely, a lightning-fast loan might come with astronomical APRs that make repayment impossible.

We look at how these providers handle credit checks, how quickly they move money into your bank account, and whether their terms are transparent or full of hidden traps. We evaluate these factors based on real-world utility for someone living in a high-pressure city. Our goal is to help you see past the marketing and find actual financial utility.

  1. SkyOne
  2. United Finance
  3. JetzLoan
  4. Experian
  5. GreendayOnline

How These New York Loan Options Were Evaluated

The evaluation process focused on accessibility for individuals with less-than-perfect credit scores. We looked at whether a lender performs a hard credit pull during the initial inquiry phase. This matters because a hard pull can impact your score before you even know if you are approved. In a competitive market like New York, where credit utilization and score fluctuations are closely watched, a “soft pull” for quotes is a vital safeguard.

Speed of funding is also a massive factor for those in urgent situations. Whether it is a car repair needed to get to work or a sudden utility shut-off notice, time is of the essence. We prioritized lenders that move quickly without sacrificing the transparency of their terms. We wanted to see who actually gets money into your account when you need it most.

We also scrutinized the range of loan amounts available to ensure a variety of needs are met. A $500 loan might fix a broken appliance, but a $25,000 loan might be necessary to consolidate high-interest credit card debt that is stifling your monthly cash flow. We prioritized clarity regarding repayment terms to ensure the lenders listed provide a genuine service rather than a debt trap.

We specifically looked for indicators of “predatory lending,” such as excessive origination fees that are tacked onto the principal. We also checked for a lack of clarity regarding the total cost of credit over the life of the loan. If a lender hides the real cost behind fine print, they didn’t make our list.

Lender Name Loan Amounts Funding Speed Credit Requirement
SkyOne $500 – $50,000 see site Personal Loans available
United Finance see site see site Installment loans available
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
Experian $2,000 – $50,000 Same-day funding available see site
GreendayOnline $100 – $5,000 As soon as the same day Bad credit welcome

The Definitive Ranking of Lenders

1. SkyOne

SkyOne – skyone.org

SkyOne operates as a federal credit union, offering a structured approach to personal financing. Unlike traditional commercial banks that may have rigid, automated rejection algorithms, credit unions are member-owned. This often makes them much more holistic in their approach to lending. They provide personal loans and lines of credit that might be a lifeline for those looking to stabilize their finances.

Their rates for personal loans can start as low as 13.99% APR. This is quite competitive when compared to the average interest rate of a high-interest credit card. If you are looking to manage a significant amount of debt or fund a major purchase—such as a down payment for a vehicle or a home renovation—their higher limits up to $50,000 provide significant breathing room for your budget.

This option is particularly suited for those who prefer a community-focused institution over a massive, impersonal bank. Because they are a credit union, the relationship is often more collaborative. This makes them a strong choice for those looking for long-term financial stability rather than a quick fix.

Pros:

  • Competitive APR starting at 13.99% for personal loans.
  • High maximum loan amounts up to $50,000.
  • Offers both loans and lines of credit for flexibility.

Cons:

  • Credit union membership requirements may apply.

2. United Finance

United Finance – unitedfinance.com

United Finance has been a staple in the lending industry since 1922, bringing decades of experience to the table. They focus on installment loans, which offer a more predictable way to manage repayments compared to high-interest payday loans. In an installment loan, you pay back a fixed amount of principal and interest over a set period. This allows for much tighter budgeting.

This is a stark contrast to “revolving” debt or payday loans where the interest can compound so rapidly that the principal remains untouched for months. They emphasize ethical lending and have issued warnings about scammers impersonating their brand. This dedication to security is vital for New Yorkers who are often targets of predatory financial solicitations via email or text.

When a lender has a history spanning a century, they have weathered multiple economic cycles. This gives them a level of institutional stability that newer, fintech-only startups may lack. It is a solid choice for those seeking a traditional, established lending experience with predictable monthly obligations.

Pros:

  • Extensive history and established reputation since 1922.
  • Focuses on installment loans rather than risky payday cycles.
  • Strong emphasis on consumer fraud protection and security.

Cons:

  • Service area is limited to specific states like Oregon and Nevada.

3. JetzLoan

JetzLoan – jetzloan.com

If you find yourself in a pinch and need cash yesterday, JetzLoan is built for speed. They specialize in connecting users with top lenders in just minutes. The most significant advantage here is the ability to check your rate without a hard credit pull. Your score stays safe during the comparison process.

This “pre-qualification” phase is essential. Many people mistakenly believe that applying for a loan is a guarantee of a score drop. With JetzLoan, you can shop around for the best terms without any immediate impact on your credit report. The platform is streamlined to be incredibly user-friendly, taking less than two minutes to fill out the initial form.

You won’t find the endless paperwork of a brick-and-mortar bank here. The digital interface is designed for someone on the go, perhaps using a smartphone while commuting on the subway. With funds potentially hitting your account in as little as 24 hours, it is a go-to for those who cannot afford to wait for traditional bank processing times.

Pros:

  • No hard credit pull during the initial rate check.
  • Extremely fast funding, often within 24 hours.
  • User-friendly, quick two-minute application process.

Cons:

  • Maximum loan amount is capped at $35,000.

4. Experian

Experian – experian.com

Experian is a household name when it comes to credit monitoring, and their loan services reflect that expertise. They understand the intricacies of the credit scoring models better than almost anyone else. They offer personal loans ranging from $2,000 up to $50,000, with flexible repayment terms spanning 24 to 72 months. This flexibility is key when trying to balance monthly expenses.

A longer term means lower monthly payments, which can provide immediate relief to your monthly cash flow. However, keep in mind this will increase the total interest paid over the life of the loan. They are particularly useful for those looking to improve their financial standing through tools like credit boosting. By using services that report utility or rent payments, you might be able to raise your score.

This creates a virtuous cycle. You use the loan to fix a financial hurdle, and then use Experian’s ecosystem to ensure your score is higher when you go to refinance or buy a car in the future. It is a way to turn a temporary setback into a long-term advantage.

Pros:

  • Same-day funding is available for certain loan types.
  • Flexible repayment terms up to 72 months.
  • Integrated tools to help boost credit scores.

Cons:

  • Approval odds and score increases are not guaranteed.

5. GreendayOnline

GreendayOnline – greendayonline.com

GreendayOnline is designed for those who need small, quick injections of cash to cover immediate gaps. They offer installment loans ranging from $100 to $5,000. This is a niche service meant for emergency situations where the primary goal is speed and ease of access. Think of it as a “micro-loan” option for life’s small, sudden inconveniences.

While it won’t help you consolidate a massive mountain of debt, it is excellent for bridging the gap between paychecks. The process is entirely online, making it incredibly convenient for busy New Yorkers on the move. They specifically welcome those with bad credit, providing a path to cash that doesn’t require a grueling, traditional application process.

This makes them an essential fallback for individuals who have been stung by previous credit setbacks but need to move forward immediately. It is a simple, straightforward solution for those who just need a little extra help to get through the month.

Pros:

  • Extremely low minimum entry point starting at $100.
  • Very fast approval and same-day cash availability.
  • Designed specifically to accommodate bad credit applicants.

Cons:

  • Loan amounts are relatively small compared to other lenders.

How to Compare Loan Offers: A Step-by-Step Guide

When you have multiple offers on the table, the numbers can become a blur of percentages and dates. To make an informed decision, follow this systematic approach:

  • Calculate the APR, not just the Interest Rate: The interest rate is the cost of borrowing the principal, but the Annual Percentage Rate (APR) includes fees like origination fees or processing costs. Always use the APR as your primary comparison metric.
  • Determine Your “Maximum Monthly Outflow”: Before looking at the loan, look at your budget. If you can only afford an extra $150 a month, don’t take a loan that requires a $200 payment, even if the total interest rate is low.
  • Check for Prepayment Penalties: Some lenders charge you a fee if you try to pay the loan off early. If you expect a tax refund or a bonus later this year, you want a loan that allows you to pay it off early without penalty.
  • Verify the Funding Timeline: If you need the money for an emergency, ask specifically, “When will the funds be cleared and available in my bank account?” There is a difference between “approved” and “available.”

Common Pitfalls to Avoid in the NYC Lending Market

The sheer density of financial services in New York can be overwhelming, and predatory lenders often use high-pressure tactics to close deals. Be wary of any lender that calls you repeatedly or uses aggressive language like “last chance” or “immediate rejection if you don’t act now.” Legitimate lenders are professional and will allow you the time to read the fine print.

Another common mistake is “loan stacking.” This occurs when a borrower takes out a small, high-interest loan to pay off a different high-interest loan. While it might feel like you are solving a problem, you are actually just moving the debt around while the interest continues to accumulate. If you find yourself needing to take out a second loan to pay for the first, it is time to stop and seek debt counseling.

Finally, always verify the legitimacy of online lenders. Even if a website looks professional, ensure they are registered to operate in your state and have a clear physical address and verifiable customer reviews. In a digital world, a polished interface is the bare minimum; actual stability is proven through historical reputation and transparent terms.

Navigating Your Loan Options Wisely

Before signing any paperwork, take a moment to breathe. It is easy to get swept up in the excitement of a quick approval, but you must look closely at the total cost of borrowing. Always ask if there are origination fees or prepayment penalties that might make the loan more expensive than it looks on the surface. A $1,000 loan that costs $100 in fees just to receive the money is significantly more expensive than the advertised rate suggests.

Avoid the temptation to take out multiple small loans from different sources to cover one large debt. This can lead to a downward spiral that is very difficult to escape. Instead, try to consolidate your needs into one manageable monthly payment whenever possible to keep your budget predictable and your stress levels low. Managing one single, predictable payment is much easier for the human brain to process than juggling five different due dates and varying interest rates every month.

Top 6 Lenders for Loans for the Unemployed with Bad Credit in 2026

Loans for the unemployed with bad credit

Top 6 Lenders for Loans for the Unemployed with Bad Credit in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Losing a job feels like a heavy blow to the gut. Suddenly, you’re staring down a mountain of bills that don’t care about your employment status. When that steady paycheck vanishes, the stress of keeping a roof over your head can feel suffocating.

This isn’t just about changing your lifestyle; it’s about basic survival. From the rent due on the first to the utility bills that keep the lights on, the sudden lack of income threatens your core security. Finding a way to bridge that gap is a daunting task, often requiring a delicate balancing act between staying afloat today and maintaining some semblance of financial stability for tomorrow.

The situation gets even tougher if your credit history is anything less than perfect. Most traditional banks will turn their backs the moment they see a low score or a gap in your work history. To a standard lender, being unemployed looks like a massive risk of default. This often triggers an automatic rejection from their automated underwriting systems.

This list examines which lenders offer actual options for people navigating these specific, difficult financial waters throughout 2026.

  1. Avant
  2. Upgrade
  3. FastLendGo
  4. Wells Fargo
  5. NetCredit
  6. OneMain Financial

How These Lenders Were Evaluated

Picking a lender requires looking past the glossy advertisements. We focused on how fast you get the money and how flexible the application process actually is. For someone without a current job, being able to use alternative verification methods—like bank statements instead of traditional pay stubs—is a massive deal. It’s the difference between getting a loan and getting a rejection letter.

We checked how lenders verify income through third-party data aggregators. This can be a lifesaver if you are a freelancer or if your income is irregular. It moves the conversation away from “do you have a boss?” toward “can you actually pay this back?”

Transparency matters too. A lender might offer quick cash, but if the interest rates are predatory, you aren’t solving your problem; you’re just delaying it. A low monthly payment sounds great, but if the term is stretched to 72 months, you might end up paying back double what you borrowed. We looked for a balance between accessibility for bad credit and reasonable repayment structures.

Lender Name Loan Amounts Terms/Rates Funding Speed Credit Requirements
Avant See site See site See site Bad Credit Options
Upgrade Up to $50,000 See site Fast funding See site
FastLendGo $500 – $5,000+ See site Quick access Bad/Fair/Good
Wells Fargo See site See site See site Traditional Requirements
NetCredit Up to $10,000 See site Same-day available Advanced Algorithms
OneMain Financial $1,500 – $30,000 From 11.99% APR As soon as 1 hour See site

1. Avant

Avant – avant.com

Avant tries to help people move forward even when life gets messy. They offer a variety of tools, including credit cards and installment loans, aimed at those needing a fresh start. Their approach works differently than the big banks. Instead of relying solely on rigid FICO scores, they use a proprietary model to look at a wider range of financial indicators.

This makes them a practical choice for debt consolidation or emergency funds. If you have a sudden car repair that might prevent you from getting to interviews, or if you just need to reorganize several debts into one monthly payment, their setup might work for you. It is a useful option for anyone moving between jobs or managing irregular income streams.

Pros:

  • Flexible loan solutions for different needs
  • Offers credit card options alongside loans
  • Focuses on helping users move forward
Cons:
  • Specific interest rates not publicly listed in all contexts

2. Upgrade

Upgrade – upgrade.com

Upgrade is a major player in the personal loan market, with amounts going as high as $50,000. They cover everything from home improvements to large, one-time purchases. Their platform is built for speed. You can check your rates in just a few minutes without hurting your credit score because they use a “soft pull” for the initial check.

This “soft pull” is a lifesaver when you’re in a tight spot. It lets you shop around for the best terms without piling on more “hard inquiries” that tank your score. They also offer a checking account that gives cash back on debit purchases, making them a decent one-stop financial hub for many people.

If you need substantial capital to settle debts or fund a project, Upgrade offers a very streamlined experience. Since most of the process happens on a smartphone, it’s ideal for people who might not have easy access to a computer or a physical bank branch. It’s built for the digital age.

Pros:

  • High loan amounts up to $50,000
  • Fast rate checking with no credit impact
  • Cash back rewards on checking accounts
Cons:
  • May require higher credit for the best rates

3. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo works well for people needing quick cash for specific, immediate emergencies. They focus on smaller personal loans, starting as low as $500. This makes them a strong choice for things like dental bills, auto repairs, or a small utility deposit. Because the amounts are smaller, getting through the door is often easier than with a massive bank. (fastlendgo.com)

The service is designed for simplicity. You can quickly compare options online. Whether your credit is bad, fair, or good, they have a product tier that fits your specific situation. For instance, if you have a “fair” score but can show a history of consistent income, you might find better terms here than at a major institution.

It is a highly accessible option for someone in a pinch who needs a quick infusion of cash to stop a bad situation from getting worse. It’s about immediate relief for immediate problems.

Pros:

  • Low entry point for small loans ($500)
  • Covers specific needs like auto or dental
  • Quick comparison of local options
Cons:
  • Small loan focus may not suit large debts

4. Wells Fargo

Wells Fargo – wellsfargo.com

Wells Fargo is a massive, established institution. They offer a full suite of services, from checking accounts to home and auto loans. They are a cornerstone of the American banking system, providing a level of stability and a physical presence that many newer fintech companies simply cannot match.

However, if you are unemployed, getting a loan here is a steep uphill battle. Traditional banks typically demand documented proof of continuous employment for at least two years and a stable debt-to-income ratio. They aren’t usually looking to take risks on anyone without a steady, verifiable paycheck.

That said, their wide range of products makes them a great destination for rebuilding your financial health once you find a new job. If you already have an account with them, it’s worth asking a representative about hardship programs or temporary assistance. Sometimes, a human conversation can open doors that an algorithm will keep shut.

Pros:

  • Extensive range of financial products
  • Highly established and reputable institution
  • Comprehensive wealth management options
Cons:
  • Tighter requirements for traditional loans

5. NetCredit

NetCredit – netcredit.com

NetCredit operates on the idea that you are more than just a number in a database. They use advanced algorithms to look past a standard FICO score. This can be a lifeline for people with imperfect credit who still need significant financing. By looking at how you handle current utility bills or rent, they can see reliability that a credit report might miss.

With loan amounts up to $10,000 and options for same-day funding, they prioritize speed. Their application process is simple, making them an attractive option for covering urgent expenses or consolidating high-interest debt. It’s a common way to take multiple small, expensive credit card balances and turn them into one single, lower-interest monthly payment.

Pros:

  • Uses advanced algorithms for underwriting
  • Same-day funding availability
  • Loans up to $10,000 available
Cons:
  • Subject to underwriting partner bank rules

6. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a great choice if you prefer talking to someone in person. They have about 1,300 branches across the country. They offer personal loans from $1,500 up to $30,000, with rates starting at 11.99% APR. Having a physical branch can be a huge comfort when you’re dealing with high-stress financial times.

One of their best features is how fast you can get the money. You can see funding as soon as one hour after signing the loan. This is perfect for an emergency, like a broken furnace or an urgent medical bill, where every hour counts. Being able to sit down with a loan officer to explain your specific situation provides a level of reassurance that a website can’t provide.

Pros:

  • Very fast funding (as soon as 1 hour)
  • Extensive branch network for in-person help
  • Predictable fixed monthly payments
Cons:
  • Requires a loan signing process

Understanding the Real Cost of Borrowing

Before you sign anything, you must understand the difference between the APR (Annual Percentage Rate) and your monthly payment. The APR includes the interest rate and any mandatory fees. It is the only way to see the true cost of the loan. When you are in a crisis, you might focus only on the monthly payment, but a low payment can be a trap if the term is too long.

A $500 monthly payment sounds manageable. But if you’re paying that for five years, you’re paying back way more than you originally borrowed. It is an illusion of affordability that can lead to a debt trap.

Keep these three metrics in mind when you’re comparing offers:

  • Total Cost of Loan: Multiply your monthly payment by the total number of months and add any upfront fees. This is the actual price of the money.
  • Prepayment Penalties: If you get a new job and want to pay the loan off early to save on interest, check if there is a fee for doing so. Look for a “no prepayment penalty” clause.
  • Origination Fees: Some lenders take a fee out of the loan before you even see it. If you borrow $1,000 but only get $950, your interest rate is actually higher than the number they quoted you.

Strategic Steps for Financial Recovery

If you use a loan to bridge the gap while you’re unemployed, treat it as a tool, not a lifestyle. Use the money for the essentials: housing, food, transportation, and utilities. Don’t use it to keep up appearances or maintain a lifestyle that your current income can’t support. The goal is to buy yourself enough time to find a job without drowning in high-interest debt.

While you navigate this period, follow these tactical steps to protect your credit and your sanity:

  1. Contact Your Current Creditors: If you can’t make a mortgage or car payment, call the lender *before* you miss the due date. Many have hardship or forbearance programs for exactly this reason.
  2. Prioritize “Survival” Expenses: If money is tight, pay your rent, utilities, and food first. Credit scores matter, but shelter and food come before credit card companies.
  3. Audit Your Subscriptions: It sounds small, but canceling a streaming service or a gym membership can save you $50 or $100 a month. That adds up when you’re on a lean budget.
  4. Document Everything: Keep a folder of every loan application, term, and email from lenders. If a dispute happens later, having a paper trail will be your best friend.

When you’re between jobs, every dollar counts. Mistakes can be incredibly expensive. Always read the fine print and look for the total cost of borrowing, not just the monthly payment. You don’t want to be trapped by high interest when you’re already struggling.

Resist the urge to take out several small loans from different places at once. That is a quick way to create a cycle of debt that is nearly impossible to escape. Instead, find one solution that addresses your most urgent need and has a repayment schedule that actually fits your reality.

If things get really difficult, remember there are resources beyond high-interest loans. Sometimes negotiating with your current creditors or looking into local assistance programs can provide more relief than taking on new debt. Always weigh the long-term impact of a loan against what you need right this second.

Top 6 Lenders for Personal Loans for High Income Individuals in 2026

Personal loans for high income individuals

Top 6 Lenders for Personal Loans for High Income Individuals in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

High earners often hit a wall when trying to access liquidity. You might see a massive salary on your tax returns, yet finding a lender that understands your complex cash flow or specific tax structures can feel like a marathon. It isn’t just about grabbing the cash. It is about finding a partner that respects your time and your financial sophistication.

For many top-tier professionals—surgeons, corporate executives, or specialized engineers—standard algorithmic lending models often miss the mark. These models fail to capture the nuances of your actual wealth. You might have significant deferred compensation, stock options, or seasonal bonuses that don’t show up on a traditional pay stub in a way that a basic credit model understands. This discrepancy can lead to frustrating denials or suboptimal interest rates despite an impeccable net worth.

Choosing the right lender requires looking beyond surface-level interest rates. You need to consider the speed of funding, the flexibility of repayment terms, and the ease of the digital interface. For those with significant assets, the friction of paperwork can be a dealbreaker. If you are closing a real estate deal or a private equity investment, spending three days uploading tax returns to a legacy bank is not an option.

This list focuses on providers that balance efficiency with the specific needs of high-net-worth borrowers. We prioritized those who offer digital-first experiences and rapid deployment of capital. We want to highlight lenders that won’t slow down your momentum when you need to move quickly on an opportunity.

  1. Discover
  2. Avant
  3. JetzLoan
  4. OneMain Financial
  5. LendingPoint
  6. Upgrade

How These Financial Providers Were Evaluated

The evaluation process focused on the specific requirements of high-income earners. This includes the ability to secure significant loan amounts without the cumbersome requirement of collateral. Many professionals need the ability to borrow against future earnings or current assets without a hard credit pull during the initial phase. We specifically looked for lenders that utilize “soft pulls” for the pre-qualification stage. This allows you to run the numbers without any risk to your credit score.

Speed of capital deployment was another critical metric. A high-earner might need funds for a sudden real estate opportunity or a strategic investment. Therefore, lenders that offer rapid funding, sometimes within twenty-four hours or even a single hour, were prioritized. We also looked at the transparency of their digital application processes to ensure no hidden surprises. A lender that hides “origination fees” deep within a 20-page PDF is a red flag for a borrower who values efficiency and clarity.

Furthermore, we examined the scalability of the loan products. A lender that only offers $5,000 might be useful for a minor repair, but it fails to serve the needs of someone looking to consolidate high-interest debt or fund a significant lifestyle upgrade. We sought out providers that offer a meaningful ceiling on loan amounts, typically $30,000 or higher. This ensures the liquidity provided is actually useful for high-net-worth strategic planning.

Comparative Overview of Top Lenders

Lender Name Max Loan Amount Funding Speed Interest Rate / APR Info Credit Check Impact
Discover $40,000 Next business day 6.99% – 24.99% No impact for pre-approval
Avant See site See site See site See site
JetzLoan $50,000 As little as 24 hours See site No hard credit pull
OneMain Financial $30,000 As soon as 1 hour Starting at 11.99% APR No impact for checking
LendingPoint $36,500 See site See site No impact for checking
Upgrade $50,000 Fast funding See site No impact for checking

Ranking the Best Lenders for High Earners

1. Discover

Discover – discover.com

Discover is a solid choice for those who value a brand backed by the full faith and credit of the U.S. Government. Their personal loans are straightforward, offering amounts from $2,500 up to $40,000. It is a reliable choice for those who want stability and a well-established institution behind their debt. If you are tired of fintech startups that might pivot their business model overnight, Discover offers a sense of permanence and institutional security.

The platform is incredibly user-friendly, allowing for a quick check to see if you are pre-approved. This is vital for high-income individuals who do not want to see their credit score take a hit just to see what kind of terms they might qualify for. It is a low-friction way to explore your options. The digital interface is streamlined, minimizing the time spent navigating through unnecessary menus. This is a luxury in itself for the time-constrained professional.

Pros:

  • Funds can be sent as early as the next business day.
  • No fees and flexible terms are available.
  • Pre-approval check does not impact your credit score.

Cons:

  • Maximum loan amount is capped at $40,000.

2. Avant

Avant – avant.com

Avant focuses on providing tailored solutions for people who are actively moving their financial lives forward. They offer a variety of products, including credit cards and loans designed for debt consolidation or home improvements. It is a versatile option for those who need a lender that can adapt to different life stages. For example, your debt-to-income ratio might fluctuate during a transition from a high-earning associate to a partner in a firm.

The company emphasizes flexible choices and friendly support, making it easier to navigate the complexities of personal debt. Whether you are looking for a quick fix for an unexpected expense or a long-term strategy for debt management, their tools are built to simplify the journey. Their approach is less about “one size fits all” and more about providing a menu of options that align with your specific financial velocity.

Pros:

  • Flexible loan solutions for various needs.
  • User-friendly digital tools for managing finances.
  • Provides multiple paths for debt management.

Cons:

  • Specific loan terms and limits are not explicitly detailed.

3. JetzLoan

JetzLoan – jetzloan.com

For the professional who needs capital yesterday, JetzLoan is a high-speed contender. They connect you with top lenders in minutes and can facilitate funding in as little as twenty-four hours. This is perfect for those who find the traditional banking pace to be far too sluggish for their lifestyle. If you have been presented with a time-sensitive investment opportunity—perhaps a real estate auction or a private placement—the speed offered here is a significant competitive advantage.

The process is incredibly streamlined, taking less than two minutes to complete a simple form. With a maximum loan amount of $50,000, they cater to significant needs without the headache of a hard credit pull during the initial rate check. This “marketplace” model allows you to see a broad spectrum of options without the repetitive task of applying to multiple banks individually. It saves you hours of administrative overhead.

Pros:

  • Extremely fast funding, potentially within 24 hours.
  • No hard credit pull required for initial rate check.
  • High maximum loan amount of $50,000.

Cons:

  • The platform acts as a connector rather than a direct lender.

4. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a powerhouse for those who prefer a mix of digital ease and human interaction. They offer personal loans ranging from $1,500 to $30,000, with rates starting at 11.99% APR. Their ability to provide money as soon as one hour after signing is a massive selling point for urgent needs. This level of speed is rare in the unsecured loan market and makes them a top choice for emergency liquidity.

If you prefer talking to a real person, you can visit one of their 1,300 branches. This hybrid model is ideal for high earners who might want the convenience of an app but still value the security of a face-to-face meeting when dealing with significant financial matters. Having a physical location to visit can provide peace of mind, especially if you need to discuss complex repayment structures or specific documentation that a purely digital lender might reject.

Pros:

  • Rapid funding, potentially in just one hour.
  • Extensive branch network for in-person support.
  • Flexible terms from 24 to 60 months.

Cons:

  • Rates for unsecured loans can be higher than secured options.

5. LendingPoint

LendingPoint – lendingpoint.com

LendingPoint positions itself as a solution for various life events, from weddings to medical expenses. They offer loans between $1,000 and $36,500, providing a solid middle ground for those who need more than a small micro-loan but less than a massive mortgage. Their underwriting process is designed to be more sophisticated than basic consumer lenders, often looking at a broader picture of your financial health.

The platform is designed to make money easy, with a process that allows you to check your rate without impacting your credit score. This allows you to shop around and compare your options against other lenders without any financial penalty to your credit profile. This ability to “window shop” is critical for high-earners who are often managing multiple lines of credit and need to be precise about which debt they are taking on and at what cost.

Pros:

  • Wide range of loan purposes supported.
  • Check rates without impacting credit scores.
  • Significant loan amounts up to $36,500.

Cons:

  • Loan amounts are lower than some specialized lenders.

6. Upgrade

Upgrade – upgrade.com

Upgrade is a comprehensive financial tool for the modern consumer, offering personal loans up to $50,000. They focus on speed and high-tech integration, allowing you to see rates in minutes. It is an excellent choice for those who want to manage their loans, savings, and checking in one ecosystem. Their technology-forward approach reduces the “friction of friction,” meaning fewer steps between application and disbursement.

Their ecosystem is quite robust, with options to earn cash back on various transactions and high APY on savings. It is a “one-stop-shop” approach that appeals to high earners who want to consolidate their financial life into a single, efficient digital interface. By centralizing these functions, you can get a clearer view of your total liquidity at any given moment, which is essential for sophisticated cash flow management.

Pros:

  • Large loan limit of up to $50,000.
  • Integrated financial ecosystem with savings and checking.
  • Fast rate checking with no credit impact.

Cons:

  • The complexity of the ecosystem might feel overwhelming to some.

Strategic Use of Personal Loans for High Earners

For those with high income, personal loans should not just be viewed as “debt,” but as a strategic tool for capital management. When used correctly, these loans can serve as a bridge to larger wealth-building opportunities. Consider the following strategic applications:

  • Arbitrage Opportunities: If you encounter a time-sensitive investment—such as a distressed real estate sale or a private equity opportunity—a personal loan can provide the necessary liquidity to secure the deal while you wait for your quarterly bonus or the sale of another asset to close. The cost of the interest is weighed against the potential upside of the investment.

  • Tax Optimization: While personal loans are not tax-deductible in the same way mortgage interest is, they can be used to manage cash flow during high-tax years. For example, using a loan to fund a major capital expense now might allow you to defer using your own cash reserves, keeping your liquidity available for other high-yield investments.

  • Debt Refinancing: High earners often carry multiple lines of credit, including premium credit cards with varying interest rates. Consolidating these into a single, lower-interest personal loan can simplify your monthly cash flow and reduce the total interest paid over time.

Avoiding Pitfalls in Personal Lending

Even with a high income, it is easy to make mistakes that can erode your wealth over time. One of the most common errors is ignoring the total cost of credit in favor of a low monthly payment. When you are looking at a $50,000 loan, a difference of 2% in interest can result in thousands of dollars of wasted capital over the life of the loan. Always look at the APR, not just the monthly installment, to see the true cost of your borrowing. The APR accounts for both the interest rate and any mandatory fees, giving you the most accurate picture of the cost.

Another mistake is failing to compare the funding speed with the necessity of the funds. If you need money for an immediate opportunity, a slightly higher rate might be worth it if the capital arrives in an hour. For example, if a business opportunity requires a 24-hour turnaround, a 12% loan delivered in an hour is far more valuable than a 7% loan that takes ten days to process. Conversely, for long-term debt consolidation, prioritize the lowest possible APR over speed.

Lastly, keep an eye on the fine print regarding prepayment penalties. High earners often find themselves with extra liquidity and may want to pay off a loan early to save on interest. If your lender charges a fee for doing this, you might find that the “cheap” loan becomes quite expensive in the end. Before signing, ask explicitly: “Is there a penalty for paying this loan off in full within the first twelve months?” For a high-income individual with fluctuating cash inflows, this flexibility is a non-negotiable requirement for a smart lending partner.