6 Best Lenders for Plastic Surgery Loans for Bad Credit in 2026

Plastic surgery loans for bad credit

6 Best Lenders for Plastic Surgery Loans for Bad Credit in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Walking into a surgeon’s office should feel like a step toward a new you, not a descent into financial dread. Many people find themselves staring at a dream procedure while their credit score sits in the basement, making the dream feel entirely out of reach. It is a heavy burden to carry when your physical goals collide with your financial reality.

The psychological weight of debt can often overshadow the excitement of a transformation. This creates a cycle of anxiety that prevents many from seeking the care they need. It is hard to focus on healing when you are worried about how to pay for the scalpel.

Finding the right way to pay for cosmetic work requires looking past the shiny brochures. You need a lender that understands the delicate nature of medical financing, especially when your credit history isn’t perfect. Traditional personal loans from major national banks often have rigid criteria that disqualify anyone with a single late payment or a high debt-to-income ratio.

This list highlights the top options available this year for those navigating the tricky waters of medical debt and reconstruction.

  1. JetzLoan
  2. Cherry
  3. CareCredit
  4. United Credit
  5. Acorn Finance
  6. MedLoan Finance

How These Medical Financing Options Were Evaluated

The selection process focused on accessibility for individuals with less-than-stellar credit histories. It is easy to find lenders for those with perfect scores, but the real challenge lies in finding institutions that don’t immediately slam the door shut. We looked for providers that offer high approval rates and transparent terms to prevent hidden surprises later.

A “hidden surprise” in medical financing often manifests as an unexpected origination fee or a sudden spike in APR after a promotional period ends. You don’t want to find out you are ineligible after you have already scheduled your surgery and perhaps even paid a non-refundable deposit.

Speed of funding and the ability to check rates without a hard credit pull were also vital. We prioritized services that offer instant or very fast decisions, ensuring that the path from consultation to the operating room is as smooth as possible. We specifically analyzed the “soft pull” mechanisms of each provider to ensure users could shop with confidence.

Lender Name Loan Amount Range Funding Speed Credit Check Impact
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
Cherry See site Immediate upon approval No hard credit check
CareCredit See site Instant decisions Prequalify with no impact
United Credit See site See site See site
Acorn Finance See site See site No credit score impact
MedLoan Finance $500 – $100,000 See site See site

Understanding the Cost of Credit: APR vs. Fixed Terms

Before selecting a lender, it is crucial to understand the mathematical difference between the types of financing available. Most medical loans fall into two categories: revolving credit and installment loans. Revolving credit, like CareCredit, functions much like a credit card. You have a limit, and as you pay it down, you can use that credit again.

This is excellent for ongoing treatments, like orthodontic work or multiple dermatological sessions, but it requires disciplined management to avoid high interest rates. If you let the balance sit, the costs can spiral quickly.

Installment loans, offered by providers like JetzLoan or MedLoan Finance, provide a lump sum upfront that you pay back in fixed monthly increments. This is often better for a one-time major surgery, such as a rhinoplasty or a tummy tuck, because it provides a predictable repayment schedule. When comparing offers, always look at the Annual Percentage Rate (APR), not just the monthly payment. A low monthly payment might seem attractive, but if it is spread over 60 months, you may end up paying double the original cost of the procedure in interest alone.

The Top-Rated Financing Solutions

1. JetzLoan
JetzLoan – jetzloan.com

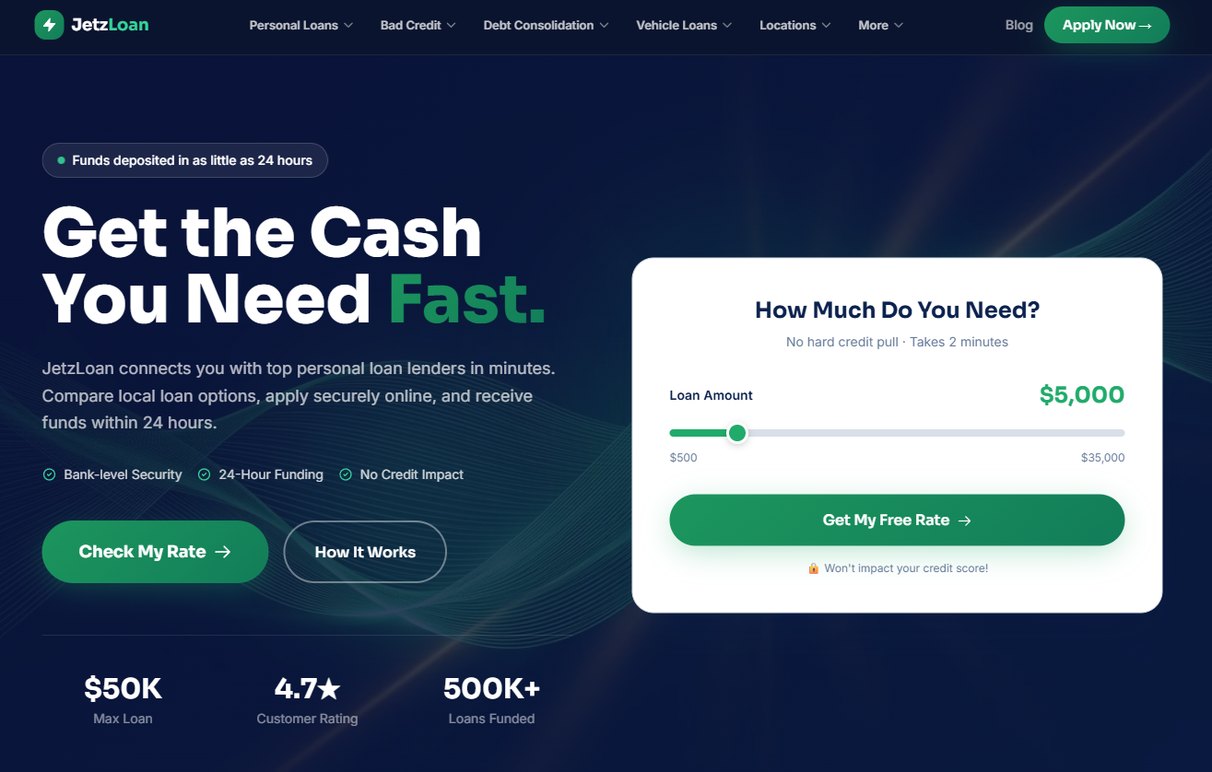
JetzLoan acts as a high-speed bridge for those needing quick cash for medical needs. It is designed for speed, aiming to get funds into your bank account in as little as 24 hours. This makes it a powerhouse for last-minute surgical requirements or unexpected medical costs that cannot wait, such as emergency dental work or urgent corrective procedures. (jetzloan.com)

The platform is incredibly user-friendly, allowing you to check rates in just two minutes. Because there is no hard credit pull, you can shop around without fear of lowering your score. This “soft pull” mechanism allows you to see your potential interest rate and term length before you commit to a formal application.

It is a practical choice for anyone who needs a significant amount, up to $35,000, without the usual bureaucratic delays associated with traditional bank loans. It gets the job done when timing is everything.

  • Pros: Extremely fast funding, no impact on credit score during checks, up to $35,000 available.
  • Cons: Maximum loan amount may be lower than some specialized medical loans.

2. Cherry
Cherry – withcherry.com

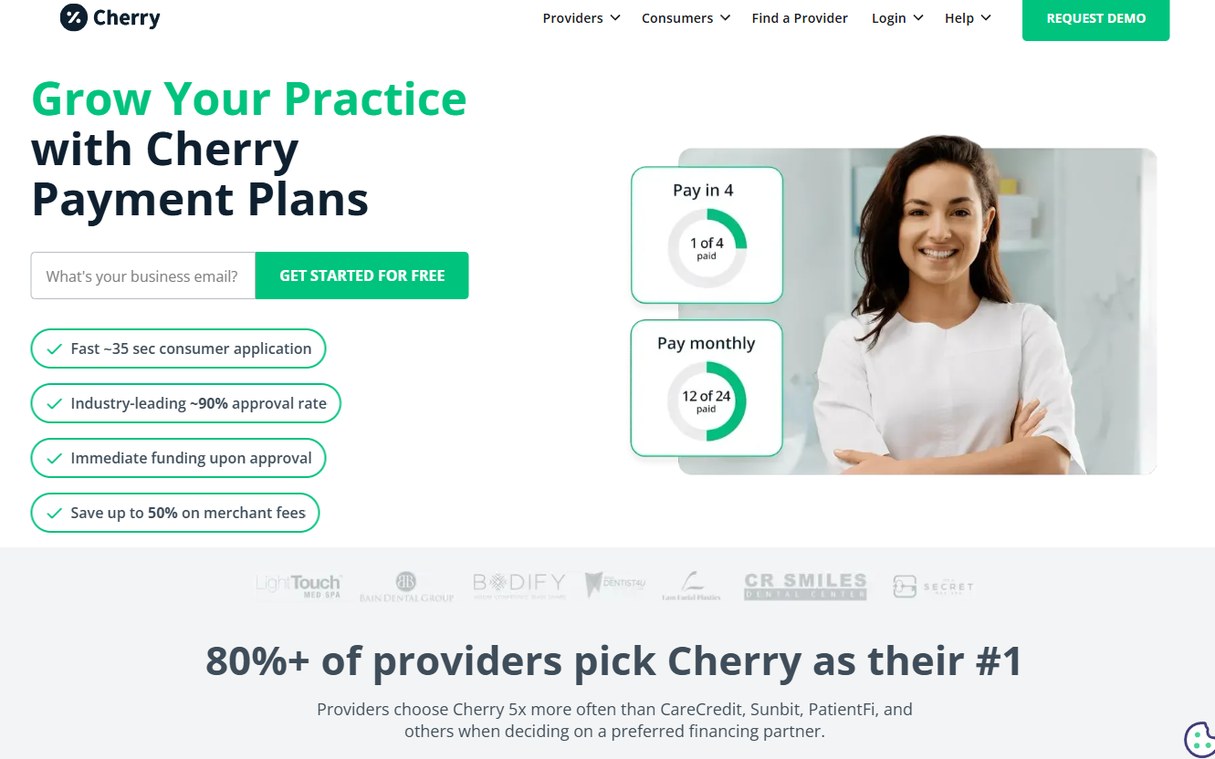
Cherry has become a massive name in the healthcare space, trusted by tens of thousands of providers. It is a favorite for patients who want a “no fuss” experience. The application process is lightning-fast, often taking only about 35 seconds to complete, which is ideal for busy people who are visiting multiple specialists in a single day.

This option is particularly strong for those seeking high approval rates. It offers a sense of ease that can alleviate the stress of medical debt. Many providers choose Cherry over other competitors because it simplifies the checkout process at the doctor’s office, making the transaction feel almost seamless.

It functions much like a digital payment service specifically tailored for the medical industry, removing the awkwardness of discussing finances in a clinical setting. You can focus on your health instead of your wallet.

  • Pros: Very high approval rates, instant approval, extremely fast application.
  • Cons: Approval is subject to provider participation and specific medical terms.

3. CareCredit
CareCredit – carecredit.com

CareCredit is a household name in the wellness industry, accepted at hundreds of thousands of locations. It functions as a dedicated health and wellness credit card. This makes it highly versatile, as you can use it for a wide range of procedures beyond just cosmetic surgery, including vision care, veterinary services, and even some types of physical therapy.

The flexibility of this credit card is its greatest strength. It allows you to pay over time, which can help manage your cash flow while you recover. Many patients utilize the “deferred interest” promotional offers, which allow for 6, 12, or 24 months of interest-free payments.

However, this is a double-edged sword. If you fail to pay the full balance by the expiration date, interest is often backdated to the original purchase date. This can result in a massive, sudden bill that catches you completely off guard.

  • Pros: Massive acceptance network, flexible financing options, instant credit decisions.
  • Cons: Requires credit approval; interest rates can be high if terms aren’t met.

4. United Credit
United Credit – unitedcredit.com

United Credit focuses on building long-term relationships rather than just closing a single transaction. They work with a variety of lenders to ensure that consumers have multiple options. This variety is a lifeline for those with varying credit profiles, from excellent to bad credit. Instead of a “one size fits all” approach, they act as a conduit to a wider market of lending specialists.

Their approach is centered around personal well-being and supporting the consumer’s journey. By maintaining a deep network of lenders, they can often find a path forward when a single bank might say no. This is particularly helpful for individuals who have been denied by major banks due to being “self-employed” or having a non-traditional income stream.

It is a solid choice for those who want a more personalized lending experience and a higher chance of approval. They look at the whole person, not just a number.

  • Pros: Wide variety of options through multiple lenders, supports diverse credit backgrounds.
  • Cons: The process may involve more steps due to the variety of lender options.

5. Acorn Finance
Acorn Finance – acornfinance.com

Acorn Finance operates somewhat differently by offering financing that is often used for larger home and medical projects. They specialize in connecting borrowers with personalized rates without the traditional sting of a credit score impact. It is a very transparent way to shop for rates, acting as an aggregator that brings various specialized lenders to one dashboard.

The platform is highly rated by users who appreciate the speed of the SMS and email application processes. Even if your credit is not perfect, they aim to find a contractor or provider who can accommodate your specific needs.

This makes them an excellent resource for complex medical transformations that involve multiple stages or providers, such as a full facial reconstruction or extensive orthopedic surgery involving several different specialists. It keeps everything in one place.

  • Pros: No credit score impact when checking rates, user-friendly SMS/Email applications.
  • Cons: More geared toward larger project financing rather than small cosmetic tweaks.

6. MedLoan Finance
MedLoan Finance – medloanfinance.com

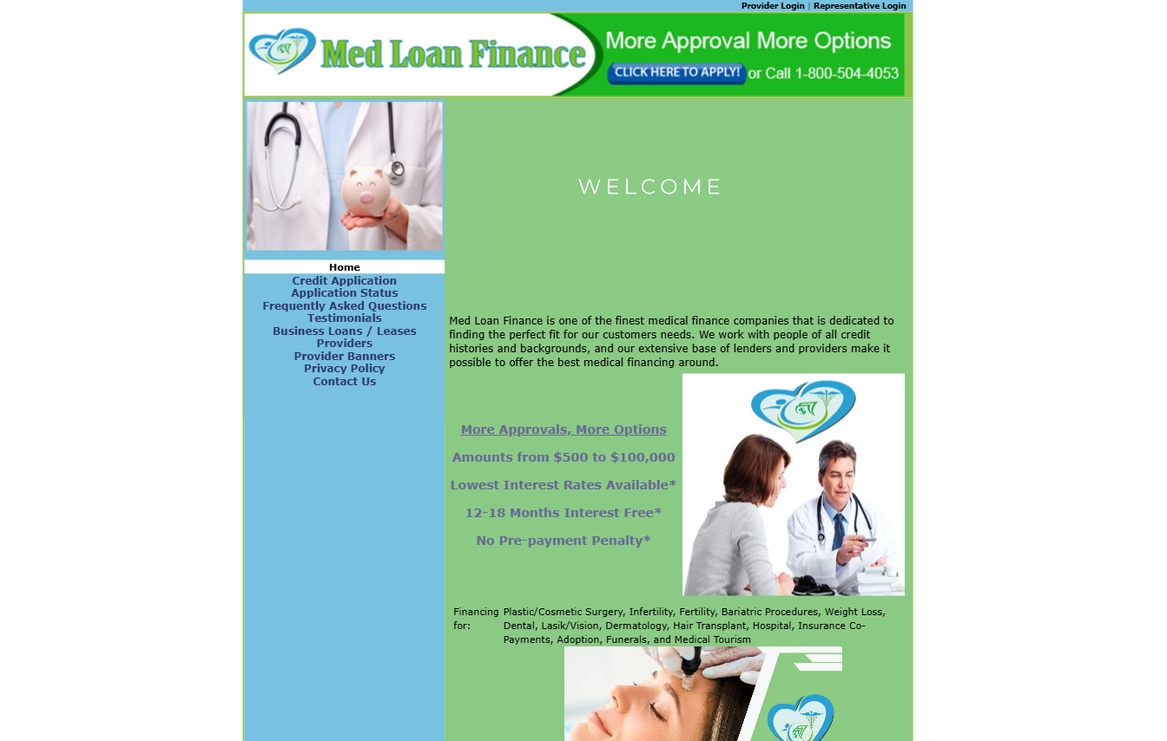
MedLoan Finance is a dedicated player in the medical sector, focusing heavily on specific procedures like bariatric, dental, or cosmetic surgery. They are built to work with people of all credit histories and backgrounds, aiming to provide the “best medical financing around” through specialized medical underwriting.

With loan amounts reaching up to $100,000, this is a serious option for major reconstructive or aesthetic journeys. Unlike general-purpose personal loans, they understand the specific timelines of medical recovery. They offer specialized terms, including the potential for interest-free periods of 12 to 18 months.

This can be a massive relief during recovery when you may be unable to work for a short period due to the surgical procedure. It provides a cushion when you need it most.

  • Pros: High maximum loan amounts, specialized medical focus, potential for interest-free terms.
  • Cons: Terms and interest rates are subject to specific medical procedure types.

Navigating Your Financing Journey

Choosing a lender is not just about the lowest interest rate; it is about finding a partner that fits your specific surgical plan. If you need a quick fix for a small procedure, a fast-funding option like JetzLoan might be your best bet. However, if you are planning a major reconstructive surgery, the higher limits of MedLoan Finance might be necessary to cover the surgeon, the anesthesia, the facility fees, and the post-operative care.

Avoid the mistake of applying for multiple hard credit pulls in a short window. This can make you look desperate to lenders and drop your score further. Each time a lender performs a “hard pull” to make a final decision, it leaves a footprint on your credit report.

Instead, always use the “no impact” or “pre-qualification” tools first. This allows you to compare your real options without any financial penalty, letting you build a mental roadmap of your potential debt before you commit. It is better to know the cost of the money before you spend the money.

Lastly, read the fine print regarding “interest-free” periods. Many medical lenders offer promotional windows, but if you miss a payment or fail to pay the balance by a certain date, you could be hit with retroactive interest. This is not just a small fee; it can be thousands of dollars depending on the principal amount. Stay organized, set up autopay to avoid accidental missed payments, and treat your medical loan with the same seriousness as a mortgage.
Top 6 Lenders for Bad Credit Loans in Arkansas: A 2026 Review

Bad credit loans arkansas

Top 6 Lenders for Bad Credit Loans in Arkansas: A 2026 Review

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Trying to manage money in the Natural State can feel like hacking through a thicket when your credit score isn’t exactly where you want it. Many Arkansans deal with sudden car repairs or medical bills without any safety net. When the bills start piling up on the kitchen table, finding a reliable lender becomes the top priority.

Living in Little Rock during a humid summer means a broken HVAC system isn’t just an inconvenience; it’s a crisis. Similarly, if a truck used for work in Northwest Arkansas needs an urgent repair, the need for quick cash hits hard. The pressure to find liquidity fast can be overwhelming when you’re just trying to keep things running.

When you search for relief, look for transparency and speed. You need to know the total cost of borrowing before any ink hits the paper. This list helps clarify which providers offer the best paths for those working to rebuild their financial footing. A single hidden fee or a misunderstood rate can turn a necessary cash infusion into a long-term burden.

  1. FastLendGo
  2. Balance Credit
  3. NetCredit
  4. Rent-A-Center
  5. Roadrunner Financial
  6. Best Egg

How We Evaluated Arkansas Lending Options

We measured each provider against specific criteria relevant to the Arkansas market. Our focus was on how easy it is to apply without hurting a credit score and how quickly funds actually hit a bank account. Speed is often the difference between a minor hiccup and a major crisis. If a utility shut-off notice arrives, a lender taking five days to process is far less useful than one offering same-day funding.

We also looked at loan amounts and repayment flexibility. A lender that only offers tiny sums might not help with a $3,000 transmission replacement. We prioritized companies that consider people with less-than-perfect credit history. This ensures the list covers a variety of needs, from a quick $500 bridge to $50,000 for debt consolidation.

The goal was to find options that actually work for real people. We didn’t want a list of companies that look good on paper but fail when you actually need the cash. Every provider here was vetted for their ability to deliver on their promises in the real world.

Lender Name Max Loan Amount Funding Speed Credit Requirements
FastLendGo See site See site Bad/Fair/Good
Balance Credit $4,000 Next business day Inclusive consideration
NetCredit $10,000 Same-day available See site
Rent-A-Center See site See site No credit needed
Roadrunner Financial See site Real-time decision All credit welcome
Best Egg $50,000 See site See site

The Best Lenders for Arkansas Residents

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo helps people who need quick cash for specific life events. Whether it is a sudden dental bill or an auto repair, this provider focuses on speed. It is a practical choice for people who want to compare local options without a long, drawn-out process. They understand that emergencies don’t wait for bank holidays. (fastlendgo.com)

This lender is useful for those who might not qualify for traditional bank loans due to a thin credit file. They offer various tiers, from small $500 loans for immediate necessities up to larger personal financing for significant life changes. It is a versatile tool for navigating emergencies, sitting between high-interest payday loans and restrictive traditional banks.

The application process is built for speed. If you are facing a sudden expense, you can’t afford to wait weeks for an answer. They aim to get you an answer when you actually need it.

Pros:

  • Quick access to various loan amounts
  • Covers specific needs like dental or roof financing
  • Simple online comparison process

Cons:

  • Website structure can be complex to navigate

2. Balance Credit

Balance Credit – balancecredit.com

Balance Credit acts as a partner for those in tight financial spots. Sometimes you just need cash to keep things moving, like paying a deposit on a new apartment or covering a utility spike. Their focus is on simplicity. They try to ensure the application doesn’t add stress through endless paperwork or confusing jargon.

One standout feature is the lack of penalties for paying off a loan early. This is a huge win for anyone trying to save money on interest. If you get a tax refund or a work bonus, you can apply that money immediately toward your principal. You won’t be punished for being proactive with your finances.

By removing prepayment penalties, they give you more control over your debt. You won’t find yourself trapped in a loan just because you tried to be responsible with your extra cash.

Pros:

  • No penalties for early payoffs
  • Fast funding by the next business day
  • No impact to credit score during eligibility check

Cons:

  • Loan amounts are capped at a relatively low $4,000

3. NetCredit

NetCredit – netcredit.com

NetCredit operates on the idea that you are more than just a number in a database. They use algorithms to look at a broader picture of your financial health. This can be a lifesaver for people who have a few hiccups in their credit history, like a single late payment from a year ago, but are otherwise stable earners.

With loans reaching up to $10,000, they offer more substantial support than many quick-cash providers. This amount is often the sweet spot for consolidating several smaller, high-interest credit card balances into one single monthly payment. It’s a way to simplify your life without a massive amount of paperwork.

You can check your eligibility without affecting your FICO score. This makes it a low-risk way to explore your options before you commit to a formal application. It’s a smart way to see what you qualify for without any guesswork.

Pros:

  • Higher loan limits up to $10,000
  • Same-day funding availability
  • Holistic review of applicants

Cons:

  • Terms may vary based on underwriting

4. Rent-A-Center

Rent-A-Center – rentacenter.com

Rent-A-Center takes a different approach by focusing on rent-to-own solutions. Instead of a traditional cash loan, you are getting the items you need through a lease-to-own model. This is ideal for furniture, electronics, or appliances when an upfront cost is out of reach and you need to furnish a home immediately.

This is a “no credit needed” path. It is a game-changer for those who have been shut out of the traditional banking system or those who simply do not want a hard credit inquiry. It allows for immediate access to essentials like a refrigerator or a sofa with very low startup costs.

This model works well for short-term cash flow gaps. If you need a washing machine today to keep your life running, this is a practical way to get it without needing a bank’s approval.

Pros:

  • No credit check required for many items
  • Low entry cost to get started
  • Wide variety of household goods

Cons:

  • Total cost over time can be high due to rent structure

5. Roadrunner Financial

Roadrunner Financial – roadrunnerfinancial.com

Roadrunner Financial is a specialized player for powersports enthusiasts. If you want a new ATV, motorcycle, or even a golf cart, this is a dedicated path. They focus on getting you riding quickly without the usual dealership haggling or the long wait times of big-box financing departments.

They offer a quick pre-qualification process that gives you a real-time decision. This is perfect for someone who has found a great deal at a local dealership in Fayetteville or Fort Smith and needs to act fast. Knowing your budget and availability upfront lets you walk into a dealership with confidence.

They understand the specific needs of this market, such as seasonal riding needs. It’s a niche service that skips the generalities and goes straight to what you actually need to buy.

Pros:

  • Specialized for powersports vehicles
  • Real-time decisions with no credit impact
  • Competitive rates valid for 30 days

Cons:

  • Highly niche; not for general personal use

6. Best Egg

Best Egg – bestegg.com

Best Egg is a heavy hitter in the personal loan space, offering much larger sums for debt consolidation. If you are trying to roll several high-interest payments into one manageable monthly chunk, this is a strong candidate. They use technology to simplify the user experience rather than making it complicated.

They offer fixed interest rates and flexible terms, which provides more stability than variable-rate loans. For those with a bit more collateral, like home fixtures or other assets, they can even offer lower rates to help you save money over the life of the loan.

This makes them a premium choice for those looking to move away from survival mode and into long-term financial planning. It’s about making a big move to get your finances back on track permanently.

Pros:

  • Large loan amounts up to $50,000
  • Fixed interest rates provide predictability
  • Excellent customer reviews and BBB rating

Cons:

  • May require better credit for the best rates

How to Compare Loan Terms Like a Pro

Before you sign a loan agreement, understand the difference between the “APR” and the “Interest Rate.” The interest rate only tells you the cost of the principal, while the APR includes other costs like origination or processing fees. When comparing two lenders, always look at the APR to see the true cost of the money.

Consider these three comparison steps:

  1. Calculate the Total Repayment: Take your monthly payment and multiply it by the number of months in the term. Subtract the original loan amount from this total to see exactly how much you are paying in interest and fees.
  2. Check for Prepayment Penalties: As mentioned with Balance Credit, some lenders charge you a fee for paying the loan back early. Always prioritize lenders that allow early payoff without extra charges.
  3. Evaluate the Monthly Impact: Look at your current monthly budget. Does the new loan payment fit comfortably, or does it leave you with zero margin for error if another emergency arises?

Common Pitfalls to Avoid in Arkansas

Navigating your borrowing journey requires vigilance. Choosing a lender isn’t just about the lowest number on the screen. You must look at the fine print to ensure you aren’t walking into a trap. Always check for hidden fees, like origination costs or late penalties, which can quietly balloon your debt.

For example, a $1,000 loan with a $100 origination fee means you only actually receive $900, but you are paying interest on the full $1,000. Avoid the mistake of taking out a loan you cannot afford to pay back. It sounds simple, but when you are in a crisis, it is easy to lose sight of the monthly obligation.

A loan is a tool to solve a problem, not a way to create a larger one later. If you are borrowing money to pay off other debt, ensure the new interest rate is significantly lower than the debt you are replacing. Otherwise, you are simply shuffling debt around without actually solving the problem.

Finally, always compare the total cost of credit. A lender might offer a low monthly payment, but if the term is three years long, you might end up paying double what you borrowed. Take a deep breath, read the terms, and pick the option that truly fits your life.

Top 5 Lenders for Personal Loans for Low Income Individuals in 2026

Personal loans for low income individuals

Top 5 Lenders for Personal Loans for Low Income Individuals in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Trying to find breathing room when your paycheck barely covers the basics feels like swimming against a heavy tide. You might find yourself staring at a mountain of bills, wondering if there is a lifeline available that doesn’t require a perfect credit score. It is a stressful place to be.

Unexpected expenses have a way of derailing a carefully managed budget in a single afternoon. A sudden transmission failure in your car, an unexpected medical co-pay, or a seasonal spike in utility costs can throw everything off balance. When things get tight, you need options that work for your specific situation.

When searching for a way forward, look past the flashy marketing. You need to know how fast the money actually arrives, what the total cost looks like over time, and whether checking your rate will tank your score. The difference between a helpful tool and a financial burden often lies in the fine print of the Annual Percentage Rate (APR) and the repayment terms.

This list focuses on lenders that offer accessible paths for those often overlooked by traditional big banks. We have included a spectrum of options, ranging from high-speed emergency funds to long-term debt consolidation tools.

  1. JetzLoan
  2. Best Egg
  3. Avant
  4. OneMain Financial
  5. OppLoans

How These Lenders Were Evaluated

Our selection process involved looking at how these companies treat borrowers who might be struggling. We focused heavily on accessibility, specifically looking for lenders that offer quick decisions. We wanted to find companies that don’t require a hard credit pull just to see your options. It is vital to know if a lender will actually talk to you or if they will just send a rejection letter.

We examined their reputation for customer service and the clarity of their fee structures. We also looked at how they handle various credit profiles to ensure they are useful for a wide range of people. Transparency is not a luxury; it is a necessity when you are trying to manage your money.

Speed and transparency were also key pillars of this evaluation. For someone living paycheck to paycheck, waiting ten business days for funds is not an option. We prioritized companies that provide rapid funding, whether that is within twenty-four hours or even the same business day. We want the help to arrive when it is actually needed most.

We also looked at the “soft inquiry” model. This allows you to shop for the best rate without the penalty of a hard credit pull. This feature is critical for anyone trying to protect their remaining credit health while looking for better terms.

Lender Name Loan Amount Range Funding Speed Credit Impact Check
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
Best Egg Up to $50,000 See site See site
Avant See site See site
OneMain Financial $1,500 – $30,000 As soon as 1 hour No credit score impact
OppLoans See site Same-day funding available Does not affect FICO score

Top Rated Lenders for Accessible Credit

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan connects borrowers with a variety of top personal loan lenders in just a few minutes. It is designed for speed and simplicity. This makes it a strong choice for anyone needing to consolidate debt or cover a vehicle loan quickly. The process is streamlined to keep the stress to a minimum. It uses a digital-first approach for those who cannot afford to wait for traditional banking cycles. (jetzloan.com)

This service is particularly helpful for those who are nervous about their credit score. Because they offer a way to check rates without a hard credit pull, you can shop around without fear of damaging your standing. This “pre-qualification” phase is essential. It allows you to see a potential interest rate and term length before you commit to a formal application.

They have built a reputation for reliability in a crowded market. With a 4.7-star rating and over 500,000 loans funded, they know how to deliver. It is a solid option if you need to see your numbers before you make a big decision.

Pros:

  • No hard credit pull to check rates
  • Fast funding in as little as 24 hours
  • Up to $35,000 in loan amounts

Cons:

  • Limited to a maximum of $35,000

2. Best Egg

Best Egg – bestegg.com

Best Egg is a major player in the personal loan space. They are well-known for helping people consolidate high-interest debt. Their goal is to simplify your monthly payments. They aim to turn a chaotic pile of bills, such as multiple credit card balances or high-interest medical debt, into one manageable chunk. By consolidating, you can often secure a lower interest rate than what you are currently paying on individual cards.

This can lead to significant long-term savings and a clearer path to being debt-free. They have built significant trust through an A+ rating from the Better Business Bureau and thousands of positive reviews. For homeowners, there might be additional opportunities to access lower rates by using fixtures like cabinets or vanities as collateral. However, most users opt for their standard unsecured personal loans.

It is a more structured approach to borrowing. This makes it ideal for those looking for a long-term financial strategy rather than a quick fix. If you want to get organized and stay organized, this might be the right fit.

Pros:

  • High loan limits up to $50,000
  • Excellent BBB rating
  • Potential homeowner discounts

Cons:

  • Requires more information for the application

3. Avant

Avant – avant.com

Avant focuses on the idea that everyone’s financial journey is unique. They offer a variety of tools and solutions, including credit cards and installment loans. Their services are specifically designed to help people move forward. Whether you are covering an unexpected emergency or funding a home improvement project, they aim to provide options that fit your life.

Unlike banks that use rigid, automated scoring, Avant looks at a broader picture of your financial health. They position themselves as a partner in your financial life. This offers flexible choices for those who might find traditional banking difficult. It is a versatile option for those who need something specific, like a debt consolidation loan, rather than a one-size-fits-all solution.

Their platform is built for those seeking a clear answer to difficult financial questions. They provide a streamlined digital experience that minimizes the paperwork typically associated with personal loans. It is built for the modern borrower who wants answers, not endless forms.

Pros:

  • Flexible loan and credit card options
  • Designed for various life stages
  • Focus on moving forward financially

Cons:

  • Specific qualifying criteria not always transparent

4. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a standout for those who prefer a human touch. With over 1,300 branches, they offer the ability to speak with a real person. This can be a lifeline when you are confused by complex terms or when your situation has nuances that an algorithm might miss. This physical presence provides a level of security and accessibility for those who prefer to handle their business in person.

The speed of their service is quite impressive. Money could potentially be available just one hour after signing. They offer loans ranging from $1,500 to $30,000 with fixed monthly payments. This helps with budgeting because you know exactly what will leave your bank account each month. This predictability is vital for families living on a strict monthly budget.

It is an excellent choice for someone who needs cash almost immediately to handle a pressing matter. If you have an urgent car repair or a sudden home maintenance issue, having a local branch to visit can provide peace of mind. You can walk in, talk it out, and get moving.

Pros:

  • Extensive branch network for in-person help
  • Very fast funding after signing
  • Fixed monthly payments for 24-60 months

Cons:

  • Interest rates can vary significantly

5. OppLoans

OppLoans – opploans.com

OppLoans is built around the idea that a credit score doesn’t tell the whole story. Their bank partners look at more than just that single number. They consider factors like your employment history and income stability. This makes them a viable option for those who have been turned down elsewhere due to a recent dip in credit caused by a life event.

If you have faced a medical emergency or a period of unemployment, they might still work with you. It is a practical solution for people who need to avoid hidden fees and complicated fine print. The application process is remarkably quick, with decisions often arriving in minutes. If you are approved, you might see the money in your account as early as the same business day.

This makes them a high-speed option for emergency situations where every hour counts. Whether you are trying to prevent a utility shut-off or covering an immediate cost of living gap, they provide quick relief. Their transparency regarding fees ensures you aren’t surprised by the total cost of borrowing.

Pros:

  • Same-day funding is a possibility
  • Does not affect FICO credit score to apply
  • No hidden fees

Cons:

  • May not be suitable for long-term debt

The Total Cost of Borrowing

When you are in a rush, the interest rate is often the first thing people overlook. However, it is the most important number on the page. You must distinguish between the APR (Annual Percentage Rate) and the simple interest rate. The APR is a more accurate representation of the cost because it includes interest and any mandatory fees, such as origination or processing costs.

For example, a loan might have a 10% interest rate, but if there is a $300 origination fee on a $2,000 loan, your APR will be significantly higher. To calculate the true impact on your budget, perform a quick “monthly impact test” before signing. Take the total monthly payment and multiply it by the number of months in your term. Subtract the original amount you borrowed from that total.

The result is the actual cost of the loan in dollars. If you are borrowing $2,000 to cover a repair, but you will end up paying $600 in interest over the life of the loan, ask yourself if that is a sustainable cost for your current budget. Understanding this math prevents the “debt trap” where you are working just to pay off the interest on previous loans.

Common Pitfalls to Avoid When Applying

One common mistake is borrowing more than you can realistically pay back each month. It might be tempting to take the maximum amount offered. For instance, you might take a $5,000 loan when you only need $3,500. However, a higher principal amount means a higher monthly payment. This can lead to a cycle of debt that is hard to escape, especially if your income fluctuates.

Always build a small buffer into your budget before committing to a new monthly obligation. This helps account for unexpected fluctuations in your regular living expenses. You don’t want your new loan payment to be the reason you can’t pay your electric bill next month.

Another trap is ignoring the impact of different types of inquiries. While many of these lenders allow you to check your rate without hurting your score through a “soft pull,” a “hard inquiry” will occur once you actually accept the loan. This is a formal request from the lender to view your full credit report, and it can cause a temporary dip in your score. Be sure you are certain about the terms before you move from the “checking” phase to the “signing” phase.

Additionally, avoid the temptation of “rolling over” short-term loans into new loans. This is a common way that small debts grow into unmanageable financial burdens. It feels like you are staying afloat, but you are actually just sinking more slowly.

The 5 Best Furniture Financing Options for 2026

Furniture financing

The 5 Best Furniture Financing Options for 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Walking into a showroom and falling in love with a velvet sofa is a feeling most of us know well. However, that immediate spark often hits a brick wall when the price tag comes into view. Financing lets you bring that comfort home today by spreading the cost over several months or even years.

Deferring large expenses helps manage modern household needs. It is especially helpful when moving into a new place or replacing a mattress or dining table. You shouldn’t have to wait for a savings account to catch up just to sleep on a decent bed.

Picking a lender involves more than just looking at a monthly payment. You have to dig into the fine print and interest rates. You also need to know if a provider requires a perfect credit score. A high interest rate can effectively double the cost of your furniture. A $1,000 sofa can quickly become a $2,000 expense by the time you make that final installment.

Look past the initial aesthetic appeal. You must evaluate the mathematical reality of your debt. This review looks at the top contenders for home furnishings debt. Whether you want a short-term promotion or a long-term plan, knowing your options is the first step toward responsible decorating.

  1. Furniture Row
  2. FastLendGo
  3. Jordan’s
  4. Rent-A-Center
  5. CashUSA

How These Lenders Were Evaluated

Evaluating furniture financing requires looking beyond the furniture itself. We focused on how flexible the terms are and how easy the application process feels. A zero percent interest offer sounds like a dream. However, those plans usually come with strict credit requirements.

Many “no interest if paid in full” plans demand a high FICO score. Lenders want to see stable, verifiable income to ensure they aren’t taking on too much risk. We also looked at how quickly you can actually get the funds. Some lenders focus on those with established credit histories to offer the lowest APRs. Others cater to people needing a second chance after credit hiccups.

We weighed the speed of approval against the total cost of borrowing. This provides a clear picture for every budget. Our evaluation analyzed these specific metrics:

  • Speed of Approval: How long from clicking “apply” to having credit ready at the register?
  • Transparency: Does the lender clearly state all fees, or are there hidden origination fees or late penalties?
  • Flexibility: Can you pay the loan off early without penalties? This is vital if you plan to make extra payments to save on interest.
  • Minimum Requirements: Is there a hard minimum credit score or a pathway for those with limited history?
Lender Max Loan Amount Interest Rate Options Credit Requirements
Furniture Row see site 0% APR available Subject to approval
FastLendGo $5,000 see site Bad, Fair, and Good
Jordan’s see site 0% APR for 24 months Subject to approval
Rent-A-Center see site Rent-to-own No credit needed
CashUSA $10,000 see site see site

Top Furniture Financing Rankings

1. Furniture Row

Furniture Row – furniturerow.com

Furniture Row is a strong choice for those combining high-quality goods with specialized financial tools. They partner with various institutions to offer promotional terms. This variety helps shoppers find a plan that fits their specific lifestyle and budget. They offer a spectrum of options rather than a one-size-fits-all approach.

The availability of 0% interest financing is a major draw. For those who qualify, this avoids the heavy weight of interest. Imagine buying a $3,000 sectional sofa. With 0% interest over 12 months, you pay $250 per month. If you were forced into a standard 18% APR loan, that same sofa could cost you nearly $3,500.

This makes premium items feel much more attainable for the average household. Just make sure you can manage the monthly cash flow. It is a great way to get high-end items without a massive upfront hit to your bank account.

Pros:

  • Special 0% interest financing available.
  • Large selection of living, dining, and bedroom furniture.
  • Options for both in-store and online shopping.

Cons:

  • Requires qualifying for specific promotional terms.
  • Missing a single payment can often result in “retroactive interest,” where you are charged interest from the original purchase date.

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo works well for anyone needing quick access to cash for various needs. While they handle more than just furniture, their personal loan structures are ideal for furnishing an entire apartment. Unlike store-specific credit, a personal loan from FastLendGo gives you total freedom. You can shop at multiple stores to maximize value.

They are particularly useful if your credit score isn’t exactly where you want it to be. By offering solutions for bad, fair, and good credit, they open doors that many traditional banks slam shut. This is a streamlined way to compare options without the headache of visiting multiple branches. It is a digital-first approach for a fast-moving world.

This is helpful if you need to furnish a rental property on a tight deadline. You get the cash in a lump sum and can shop wherever you please. It removes the restriction of being tied to a single retailer’s inventory.

Pros:

  • Covers a wide range of credit scores.
  • Provides loans from $500 up to $5,000.
  • Fast online application process.

Cons:

  • Primarily focused on personal loans rather than direct store credit.
  • Terms may be shorter than long-term furniture-specific installments.

3. Jordan’s

Jordan's – jordansfurniture.com

Jordan’s Furniture is a major player known for an impressive showroom experience. They offer sophisticated financing that makes high-end purchases feel manageable. Their promotions often include perks like free white glove delivery. This adds massive value to a large purchase by saving you labor and stress.

White glove delivery includes bringing items inside, assembling them, and removing all the packaging. When paired with high-quality goods, the financing becomes even more attractive. The 24-month 0% APR option is a standout feature for many buyers. It allows you to upgrade your bedroom or living room without the immediate sting of a massive bill.

It is a strategic choice for those with a steady income who prefer to preserve cash for rent or emergency savings. This “interest-free” window acts as a short-term loan. It lets your money work elsewhere while you enjoy your new home comforts.

Pros:

  • Promotional 0% APR for 24 months.
  • White glove delivery options available.
  • Wide variety of home categories including gaming and outdoor.

Cons:

  • Promotional rates are subject to credit approval.
  • High-end inventory can lead to high total debt if not carefully managed.

4. Rent-A-Center

Rent-A-Center – rentacenter.com

Rent-A-Center is the go-to option for those who want to avoid the traditional credit system entirely. Their rent-to-own model is built on flexibility. You can get the gear you need today without the immediate pressure of a long-term commitment or a formal credit check. This is essentially a lease-to-own agreement.

You pay for the use of the item, with the option to own it after a set number of payments. This is a lifeline for individuals in transitional phases of life. Students or people moving for seasonal work often find this model helpful. You can start with a small down payment and upgrade as your needs evolve.

For instance, you might start with a basic coffee table. After a few months of successful payments, you could swap it for a larger entertainment center. It provides a level of freedom that standard installment loans simply do not offer. You aren’t locked into one piece of furniture forever.

Pros:

  • No credit needed to get started.
  • High flexibility to upgrade or change plans.
  • Low entry cost to start renting.

Cons:

  • Rent-to-own models can be more expensive in the long run.
  • If you do not complete the full term, you do not own the items and have essentially paid for “renting” without equity.

5. CashUSA

CashUSA – cashusa.com

CashUSA operates as a digital connector. They help users find personal loans that meet specific criteria. If you need up to $10,000 to remodel a room, this service can point you toward a lender. It is a modern, efficient way to shop for credit. It works much like a comparison engine for your finances.

The process is designed to be simple. It typically involves just four steps: application, comparison, selection, and funding. While they may connect you to debt relief if a loan isn’t found, their primary goal is facilitating connections. This is ideal for the tech-savvy consumer who wants to see multiple options on a single screen.

You can skip the hours spent on the phone with different banks. Instead, you get a streamlined online experience. It saves time when you are looking to make significant household changes quickly.

Pros:

  • Potential for loans up to $10,000.
  • Fast connection to lenders.
  • Simple, streamlined online application.

Cons:

  • May provide marketing offers instead of loans if not matched.

Essential Questions to Ask Before Signing

Before you settle on a financing plan, perform a “stress test” on your budget. Many consumers fall into the trap of looking only at the monthly payment. A $50 monthly payment sounds incredibly manageable. However, if that payment lasts for 60 months, you are paying for that item for five years.

If the interest rate is high, you might end up paying for the item twice. Use this checklist when talking to a salesperson or a loan officer. It will help you avoid expensive surprises later on:

  1. “What is the total cost of the item including all interest and fees?” This is the most important number in the transaction.
  2. “Is there a penalty for early repayment?” If you get a bonus and want to pay off your sofa in month six, you should be allowed to do so without a penalty.
  3. “What happens if I am one day late on a payment?” Some contracts have strict “default” clauses where you lose all your 0% interest benefits and are charged backdated interest immediately.
  4. “Are there any origination fees or service charges?” Some lenders add a $100 “processing fee” upfront that isn’t included in the advertised monthly payment.

How to Choose the Right Plan

Before signing your name, look closely at the total cost of ownership. A low monthly payment can be deceptive if it is stretched over a decade. Always ask, “What is the total amount I will have paid by the end of this term?” This simple math reveals the true cost of the “deal.”

Avoid the trap of taking on more debt than your monthly budget allows. It is easy to get swept up in the excitement of a new dining set. However, financial stability is the foundation of a happy home. If you choose a rent-to-own option, remember you are paying for flexibility, not necessarily the lowest price.

Rent-to-own is a service for convenience. Personal loans and store credit are tools for ownership and building equity. Always check the interest requirements. If you qualify for a 0% APR deal, ensure you understand the penalties for a single late payment. One missed deadline can trigger a massive interest spike.

Stay organized and stay diligent. Use a calendar to track your payment dates. Consider setting up autopay so you never miss a beat. By being proactive, you can enjoy your beautiful new furniture without the lingering stress of debt.

Top 6 Land Loans for Bad Credit Options in 2026

Land loans for bad credit

Top 6 Land Loans for Bad Credit Options in 2026

Last updated: 2026-10-17

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Finding the right dirt is often easier than finding the money to buy it. For many dreamers, the idea of owning a slice of the countryside or a quiet wooded lot feels just out of reach. Credit histories often act as a wall. Traditional banks frequently turn up their noses when a score dips below certain numbers, often demanding a 20% to 30% down payment that most first-time buyers simply do not have sitting in a savings account.

They view raw land as a high-risk asset. Unlike a residential home, land doesn’t offer a physical structure to serve as collateral if the loan goes sour. This makes securing financing a bit of a climb. You have to find lenders who see the value in the soil rather than just the digits on a credit report.

This list focuses on finding paths through those financial hurdles. Whether you want a small garden plot, a few acres for a weekend retreat, or a massive acreage for a homestead, you need to know your options. Understanding the difference between a “raw land loan” (land with nothing on it) and a “finished lot” (land with utility access and road frontage) is your first step toward matching with the right capital provider.

  1. Acorn Finance
  2. JetzLoan
  3. LightStream
  4. Country Bank
  5. Lendersa
  6. USDA

How These Land Loan Options Were Evaluated

The evaluation process focused on accessibility for different credit profiles. Not every lender is built for the same purpose. It is vital to know the distinction between personal loans, hard money, and government-backed programs. A lender that provides a quick cash injection might not be the right fit for a long-term mortgage. For example, a personal loan might offer speed, but you will likely face a higher interest rate than a traditional mortgage secured by the property itself.

Conversely, a traditional mortgage might take 45 days to close. In that time, your dream property might be sold to someone else. Speed of funding and the impact of credit inquiries were also key metrics. Some providers allow you to check rates without hurting your score. This is a lifesaver when you are trying to understand your borrowing power before committing to an offer.

We prioritized transparency. We looked at how quickly funds move, the complexity of the application, and what kind of collateral is actually required for the deal. We looked specifically at whether the lender requires a “hard pull” that stays on your report or a “soft pull” which is just an inquiry for informational purposes. It makes a world of difference when you are on a tight budget.

Lender Name Max Loan Amount Funding Speed Credit Requirement Best For
Acorn Finance See site See site Good & Bad Credit Contractor/Home Improvement
JetzLoan $50,000 24 Hours No Hard Pull Check Fast Cash/Debt Consolidation
LightStream $100,000 See site Good to Excellent High Credit Borrowers
Country Bank See site 60 Day Rate Lock Subject to Approval Raw Land/Buildable Lots
Lendersa See site Fast Closing Varies (Hard Money) Fix and Flip/Investors
USDA See site See site Varies Rural Development/Homes

Ranking of Land Loan Providers

1. Acorn Finance

Acorn Finance – acornfinance.com

Acorn Finance acts as a bridge between borrowers and various financing options. They specialize in providing $0 dealer fees. This is a breath of fresh air in an industry known for hidden costs and service charges that can add thousands to your total loan amount. It is a solid choice if you need to combine land acquisition with immediate improvements, such as clearing trees or installing a driveway.

This provider is particularly useful for those who need to get a project moving quickly. Because they cater to both good and bad credit, the barrier to entry is significantly lower than a standard big-box bank. Instead of being judged solely on a FICO score, the variety of lenders they connect you with means there is a higher probability of finding a specialist who understands your specific situation.

It is a practical tool for the modern borrower who needs flexibility. You won’t find yourself stuck in a loop of denials if you have a complicated financial history. They focus on matching you with someone who can actually say “yes” to your project.

Pros:
  • $0 dealer fees for contractors and borrowers
  • Personalized rates with no credit score impact during checking
  • High customer satisfaction with 4.3 stars on Trustpilot
Cons:
  • May not offer the lowest rates compared to prime lenders

2. JetzLoan

JetzLoan – jetzloan.com

When time is of the essence, JetzLoan moves with impressive speed. They can deposit funds in as little as 24 hours. This makes them a go-to for urgent land deals or consolidation. This speed is essential in competitive markets where a seller might be looking for a “cash offer” to bypass the lengthy appraisal and inspection processes required by traditional banks.

The application process is remarkably streamlined. It takes only about two minutes to complete. This makes it an ideal option for someone who has found a parcel of land at an auction and needs to secure funds immediately to show proof of capability. The ability to check rates without a hard credit pull is a major advantage for those with sensitive credit. This allows a borrower to shop around without fear of further damaging their score.

It is a high-speed option for a fast-paced market. If you find that perfect lot on a Friday afternoon, you don’t want to be waiting until next month to prove you can pay for it. JetzLoan fills that gap for those who need to act fast.

Pros:
  • Funding in as little as 24 hours
  • No hard credit pull to check rates
  • High loan limits up to $50,000
Cons:
  • Limited to personal loan structures rather than traditional land mortgages

3. LightStream

LightStream – lightstream.com

LightStream is a different beast entirely. They cater to those who have already climbed the credit ladder. They offer low fixed rates that are hard to beat if you have good to excellent credit. It is a premium service for those who want stability and predictability. You can lock in a rate and know exactly what your monthly payment will be for the duration of the loan.

The loan amounts can reach up to $100,000. This provides significant breathing room for substantial land purchases or for purchasing a large plot to subdivide. However, if your credit is currently in the “bad” category, this particular door will likely remain closed. They use automated underwriting processes that prioritize high FICO scores and stable income history.

It is a destination for the credit-worthy who want to avoid the higher interest rates of subprime lenders. If your finances are in order, this is often the most efficient way to move forward. They make the process incredibly smooth for those who meet their criteria.

Pros:
  • Low fixed interest rates
  • Loan amounts up to $100,000
  • Highly reputable through Truist
Cons:
  • Requires good to excellent credit; not for bad credit

4. Country Bank

Country Bank – countrybank.com

Country Bank offers a more traditional, community-focused approach to lending. They are an FDIC-insured institution that understands the nuance of land in ways a large national bank cannot. While a national bank might reject a loan for a lot that has no paved road access, a community-focused bank understands the local zoning laws and the intrinsic value of that specific piece of geography.

One standout feature is their 60-day rate lock, which provides a sense of security in a volatile market. This allows a buyer to plan their next steps, such as hiring an architect or a surveyor, without worrying that interest rates will spike before they can close the deal. They provide tailored solutions for both raw land and buildable lots. They recognize that the risk profile of each is vastly different.

This is a great choice for someone looking for a long-term relationship with their lender. They know the area and they know the land. That local knowledge can be the difference between a deal falling through and a deal closing smoothly.

Pros:
  • 60-day rate lock availability
  • FDIC-insured security
  • Offers financing for both raw and buildable land
Cons:
  • Standard bank approval processes can be rigorous

5. Lendersa

Lendersa – lendersa.com

Lendersa is built for the investor who needs to move at the speed of light. Using AI to match borrowers with hundreds of hard money lenders and private investors, they optimize for closing speed. This is a high-octane option for real estate professionals who specialize in land flipping or quick acquisitions for development projects. While a traditional bank might take weeks to verify surveys, Lendersa’s network is built for rapid movement.

If you are looking to jump into an auction or a fast-moving “fix and flip” scenario, this is where you look. They focus on getting the deal closed in days rather than months. This is crucial when competition is fierce and a seller demands a quick close. They cover both residential and commercial property types, providing a wide net for diverse investment strategies.

It is not for everyone, as the terms are often quite different from a standard mortgage. However, for the professional investor, the speed can be worth the premium. It is all about how fast you can turn the property around for your next move.

Pros:
  • Uses AI to match lenders and optimize rates
  • Designed for fast closing and auctions
  • Covers residential and commercial property types
Cons:
  • Hard money terms can be much more expensive than traditional loans

6. USDA

USDA – rd.usda.gov

The USDA is a government-backed option that focuses on the backbone of the country: rural development. They provide loans and grants aimed at helping people buy, build, or repair homes in specific rural areas. This is a mission-driven approach to lending designed to prevent rural depopulation by making it easier for young families and homesteaders to establish roots.

This is an excellent path for those looking to live in a rural setting and build a life from the ground up. The programs are designed to strengthen rural economies and expand opportunities for families who might otherwise be overlooked due to low down payments or specific income requirements. If you qualify, this can be one of the most affordable ways to acquire property in the country.

It requires a bit more paperwork and a specific location, but the payoff is significant. It is a program built for people, not just for profit. If you fit the criteria, it is a very powerful tool for homeownership.

Pros:
  • Government-backed stability and support
  • Focuses on rural economic development
  • Offers various programs including grants and loans
Cons:
  • Strict geographic requirements for eligibility

Understanding Land vs. Home Loans

Before applying, it is vital to understand the fundamental differences in how lenders view land versus a residential house. When you buy a house, the building itself acts as security. If you stop paying, the bank can sell the house and recoup their money. When you buy land, the security is just the dirt. If the market for that specific area dips, the land may not be worth what you paid for it, making it much riskier for the lender.

Because of this risk, land loans often require more from the borrower. You might face higher down payments, often 20% to 50% for raw land. You may also see higher interest rates than traditional residential mortgages. Lenders often demand more extensive documentation regarding access, easements, and utilities. In some cases, especially with hard money, you might even see short-term repayment options.

Essential Steps for Securing Your Land Deal

To ensure you aren’t left with a beautiful piece of property that is impossible to live on, follow these specific steps during your due diligence phase:

  1. Verify Access: Never assume a dirt path is a legal right-of-way. Ensure the property has “legal access” to a public road. Without this, the land is virtually unmarketable and unfinanceable.
  2. Check Utilities: Ask for a “perc test” if you plan to install a septic system. If the soil doesn’t drain properly, you might be unable to build a home. Additionally, check the cost to bring electricity to the site; running power lines can cost tens of thousands of dollars.
  3. Review Zoning: Just because it is “rural” doesn’t mean you can build whatever you want. Check local ordinances for setbacks, minimum acreage requirements, and restrictions on livestock or structures.
  4. Survey the Boundaries: Don’t rely on old fences or “handshake” agreements with neighbors. A professional survey is the only way to ensure you are actually buying the acreage you think you are.

Choosing a lender is not a one-size-fits-all endeavor. If you are an investor needing to move on a property immediately, a hard money lender like Lendersa might be your best bet, even if the cost is higher. If you are a long-term resident looking for stability, a traditional bank or a USDA program might be more appropriate.

One common mistake is failing to account for the “hidden” costs of land. Unlike a house, land often requires immediate investment in road access, water, and electricity. Always ensure your loan amount leaves room for these essential infrastructure upgrades. If you use your entire budget to buy the dirt, you may find yourself owning a beautiful view that you cannot actually reach or inhabit.

Always remember to check the impact of your inquiry. Utilizing lenders like JetzLoan or Acorn Finance that offer no-impact rate checks can save your credit score from unnecessary dents. Knowledge is power, and in the world of land lending, information is your best tool for success. Take your time, do your homework, and ensure your financing matches your long-term vision for the land.