The 5 Best Lenders for Bad Credit Loans in Arizona for 2026

Bad credit loans arizona

The 5 Best Lenders for Bad Credit Loans in Arizona for 2026

Last updated: 2026-10-17

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Surviving the Arizona heat is hard enough without a financial crisis hitting you like a desert storm. Many locals find themselves staring at a massive medical bill or a broken car engine when their credit score is sitting in the mud. You need a lender that cares about your situation more than a three-digit number on a screen.

Whether an AC unit dies in the middle of a Phoenix July or you face an unexpected legal bill in Tucson, cash becomes a necessity overnight. The trick is finding a way forward without falling into a predatory trap. It is vital to look at your options before the stress of a deadline forces you into a bad deal.

This list highlights lenders that actually understand the needs of people living in the Valley of the Sun. We looked for speed and clear terms above all else. It isn’t just about getting a check today; it is about making sure you aren’t paying for that money for the next decade.

A quick $500 for a car part might seem like a small fix, but bad math can turn that into a $1,500 headache. We evaluated these lenders based on how fast they move and how honest they are about the total cost. You deserve to know exactly what you are signing up for.

  1. NBA Arizona
  2. Arizona Zip Loan
  3. Sun West
  4. Arizona Financial
  5. Cash Time

How Arizona Lenders Were Evaluated

We checked how easy it is for someone from Phoenix to Sedona to get help. Our focus was on how fast the money arrives and what kind of products are available for people with less-than-perfect credit. You shouldn’t have to be a millionaire to get a fair shake at a loan.

It is important to see the difference between a big bank and a specialized lender. Traditional banks usually demand high FICO scores and years of steady paychecks. Specialized lenders often look at collateral or other ways to prove you can pay them back, which gets you through the door much faster.

We looked closely at what these companies actually offer right now. We checked loan amounts, the types of loans they provide—like title or personal loans—and how easy the application feels. We tried to find the “friction points” where people usually get stuck, like mountains of paperwork or waiting days for a human to call you back.

Our goal is to give you a clear map so you don’t feel lost when you need cash most. We want to help you avoid the headache of complicated documentation and long, drawn-out waiting periods.

Lender Name Loan Amounts Funding Speed Credit Requirements
NBA Arizona See site See site See site
Arizona Zip Loan Up to $25,000 24hrs Average See site
Sun West See site See site See site
Arizona Financial See site See site See site
Cash Time $100 – $100,000 As fast as 15 Minutes No Problem

Top Rated Arizona Lenders for Challenging Credit

1. NBA Arizona
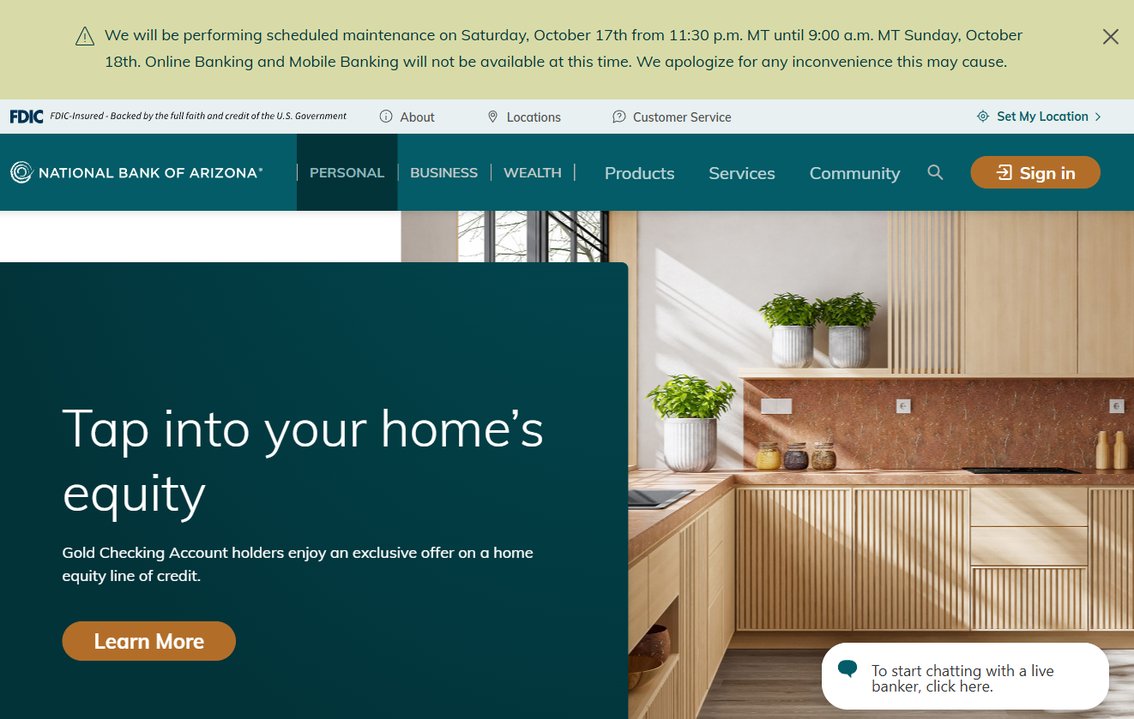
NBA Arizona – nbarizona.com

NBA Arizona operates as a highly secure, FDIC-insured institution. If you are looking for something more permanent than a quick fix, they offer a wide range of banking products. You can find everything from basic checking accounts to complex wealth management and retirement planning.

Since they are FDIC-insured, your deposits are protected up to the legal limit. This gives you a level of security that many “quick cash” lenders simply can’t provide. It is a solid choice if you want a place to grow your money, not just borrow it.

They are a great option for homeowners with equity to use. Gold Checking Account holders can access special offers on home equity lines of credit (HELOCs). A HELOC can be a lifesaver for a homeowner in Scottsdale or Mesa who needs a large sum for a major renovation or to clear out old debt.

Using equity as a safety net often leads to lower interest rates than a standard personal loan. It turns the house you live in into a tool for your financial future.

Pros:

  • FDIC insured and backed by the U.S. Government.
  • Offers premium features through Gold Accounts.
  • Provides comprehensive wealth and retirement planning.

Cons:

  • May require higher credit standards for premium products.
  • Less focused on instant, small-dollar emergency cash.

2. Arizona Zip Loan

If you need money moving as fast as a desert breeze, Arizona Zip Loan is built for that exact speed. They serve families from the busy streets of Phoenix to the quiet views in Sedona. They specialize in closing the gap between slow banks and immediate needs.

This lender works well for home repairs, medical bills, or sudden emergencies. Their process is designed to give you answers without the usual banking headache. You won’t spend weeks waiting for a loan officer to look at your file; the digital and phone-based application is built for speed.

They have built a solid reputation, holding a 4.9-star rating from many Arizona families. These are people who needed reliable support during some of their most stressful moments and found it here.

Pros:

  • Fast average approval time of 24 hours.
  • High customer satisfaction with 4.9-star rating.
  • Covers a wide range of needs from $1,000 to $25,000.

Cons:

  • Approval is subject to their specific credit criteria.
  • Fixed monthly installments may be rigid for some budgets.

3. Sun West
Sun West – mysunwest.com

Sun West Credit Union offers a variety of products for different stages of life. Because a credit union is member-owned, they are often more invested in the local community than a big commercial bank. They want you to succeed because you are part of the group.

You can find high-yield savings, money market accounts, and even complex mortgage options here. They aim to be your one-stop shop for everything from your first car to your forever home.

They offer personal loans, credit cards, and auto loans. If you are trying to fix a bad score, their secured credit builder options are a standout. You provide a small amount of collateral—usually a cash deposit—which acts as a safety net for the lender.

This allows you to show the credit bureaus that you can handle debt responsibly. It is a way to lift your score over time without the high risk of unsecured loans.

Pros:

  • Diverse product range including savings and mortgages.
  • Offers credit-building tools to help improve scores.
  • Provides both digital and in-person banking options.

Cons:

  • Credit union membership may be required.
  • Rates are subject to approval and credit history.

4. Arizona Financial
Arizona Financial – arizonafinancial.org

Arizona Financial focuses on the big milestones. They know that no two lives look the same, so they offer flexible options for buying a home, a car, or consolidating debt. Their mortgage officers are trained to walk you through the scary parts of the process.

They can explain the weird stuff, like escrow accounts, closing costs, and points. For a first-time homebuyer in a growing suburb, having someone to explain these details can make all the difference between a dream and a disaster.

Whether you are looking to buy your first house or refinance to lower your monthly payment, they provide the guidance you need. They understand the local market, from the rising prices in Tempe to the stability of older neighborhoods.

Pros:

  • Specialized support for home buying and refinancing.
  • Flexible options for different life stages.
  • Experienced mortgage officers to guide the process.

Cons:

  • Mortgage focus may be too heavy for quick cash needs.
  • Likely requires a more established credit history for home loans.

5. Cash Time
Cash Time – cashtime.com

When you are in a real pinch and need cash right this second, Cash Time is the heavy hitter. They specialize in title and registration loans, which is perfect if you can’t wait days for an approval. You get the cash quickly, but there is a catch.

A title loan uses your car as security. This means you get the money, but you are putting your ride at risk if you don’t pay the loan back as promised. It is a fast solution, but you have to be careful.

They can fund loans almost instantly, making them ideal for true emergencies. The loan amounts are huge, ranging from a tiny $100 to a massive $100,000. They say bad credit is “no problem,” which makes them very accessible for those who have been turned down elsewhere.

Just remember, that accessibility usually comes with higher interest rates. That is a critical factor to weigh before you sign anything.

Pros:

  • Extremely fast approval, sometimes in as little as 15 minutes.
  • Very high loan limits up to $100,000.
  • Specifically caters to those with bad credit.

Cons:

  • Title loans require using your vehicle as collateral.
  • High interest rates are common with rapid-funding loans.

Understanding the True Cost of Borrowing

Many people fall into a trap by only looking at the monthly payment. A $50 payment looks much better than a $200 payment at first glance. However, that $200 payment might be for a loan that lasts only 6 months, while the $50 one could drag on for 5 years.

In that second case, you end up paying much more for the exact same amount of money. This is the “total cost of credit,” and it is what actually matters. Always look at the big picture, not just the number you owe each month.

To see the real cost, ask for the Annual Percentage Rate (APR). The APR is more accurate because it includes the interest rate plus any mandatory fees. If a lender says the rate is 10% but charges a $500 fee, your actual APR is much higher. Compare loans based on the APR to find the best deal.

How to Prepare for Your Loan Application

If you know you need a loan soon, you can take a few steps now to help your chances. Being prepared is the best way to avoid a financial desert and move toward stability. A little work now saves a lot of stress later.

First, get your paperwork in order. Most lenders will want to see:

  • Proof of identity: A valid Arizona driver’s license or state ID.
  • Proof of income: Your last two pay stubs, W-2s, or bank statements.
  • Proof of residency: A recent utility bill like water or electric.
  • Proof of expenses: Statements for any current debts you want to combine.
Second, check your own credit report. You can get a free copy from the major bureaus. If you see errors—like a debt that isn’t yours—dispute them immediately. One mistake can drop your score by 50 points, which might stop you from getting a better rate at Sun West or Arizona Zip Loan.

Finally, decide exactly how much you actually need. It is tempting to “round up” for a cushion, but that just increases your interest costs. If a transmission repair costs $1,200, don’t ask for $2,000. Borrowing more than you need is a fast way to start a debt cycle that is hard to break.

How to Navigate Your Loan Options

Before you sign anything, read the fine print. It is easy to get excited about seeing a large sum of money, but the cost of that money is the real story. Ask about the total cost and any hidden fees. Specifically, ask about “prepayment penalties.” Some lenders charge you a fee if you try to pay the loan off early, which basically punishes you for being smart with your money.

Try to avoid taking out multiple loans at once. This can create a “debt spiral” that is nearly impossible to escape. Taking a title loan to pay a credit card, then a personal loan to pay the title loan, means you are just paying interest on interest. Focus on one solution that fits your budget and has a predictable schedule you can actually manage every month. If you can’t see yourself making the payment for a full year without a struggle, the loan is likely too big.
Top 6 Lenders for HVAC AC Financing Options in 2026

Hvac ac financing

Top 6 Lenders for HVAC AC Financing Options in 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

When summer heat waves hit or winter chill seeps through the floorboards, a broken HVAC system feels like a sudden emergency. Most homeowners do not have several thousand dollars sitting in a drawer ready to cover a brand-new condenser unit or a furnace replacement. Specialized financing steps in to bridge the gap between a broken unit and a comfortable home.

Choosing the right way to pay for these essential repairs requires looking beyond just the monthly payment. You have to weigh the speed of funding against the long-term cost of interest and the potential impact on your credit score. This list examines various providers to help you find a path that fits your immediate budget and your long-term financial health.

  1. Hearth
  2. JetzLoan
  3. Flexxbuy
  4. AmeriCash Loans
  5. Roadrunner Financial
  6. NetCredit

The Standards for Evaluating HVAC Financing Providers

Finding a lender for home climate control is not like shopping for a car or a small personal loan. HVAC projects are often urgent. If your furnace dies in January, you cannot afford to wait two weeks for a bank to review your paperwork and verify your income.

The comparison below focuses on how quickly funds become available and what kind of credit profile is required to get through the door. Some lenders focus on high-ticket installment loans. Others specialize in quick, short-term advances or lease-to-own models for those with limited credit history. The goal is to match the lender’s strengths to the specific urgency of the repair.

Lender Name Max Loan Amount Funding Speed Credit Requirements
Hearth see site see site see site
JetzLoan $35,000 As little as 24 hours No hard credit pull
Flexxbuy $100,000 Next business day Credit Select (35+ lenders)
AmeriCash Loans see site Instant decision Good credit not needed
Roadrunner Financial see site Two minutes All credit welcome
NetCredit $10,000 Same-day funding available Flexible terms

1. Hearth

Hearth – hearth.com

Hearth operates as a specialized resource for those looking to optimize their home energy efficiency. While many lenders focus purely on the money, this platform provides a deep well of information regarding wood stoves, pellet stoves, and various energy-saving equipment. It acts as a community hub for those wanting to make responsible, clean, and safe fuel choices.

This is an ideal choice for the homeowner who wants to do their homework before committing to a major installation. Instead of just looking at a loan, you can dive into forums and discussions to understand the long-term benefits of the equipment you are financing. It is a knowledge-first approach to home improvement.

Pros:

  • Extensive community forums for technical advice.
  • Focus on energy-efficient and sustainable equipment.
  • Valuable historical data on various heating fuels.

Cons:

  • More of an information and advice resource than a direct lender.

2. JetzLoan

JetzLoan – jetzloan.com

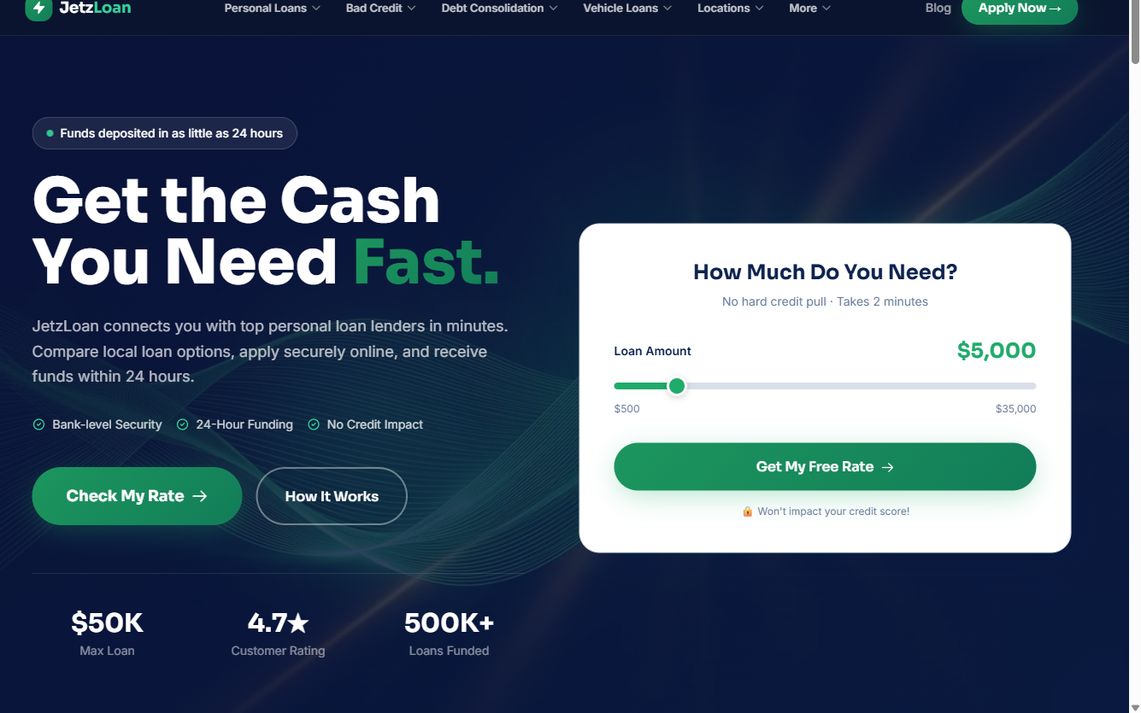
Time is of the essence when your living room feels like a sauna. JetzLoan is built for the person who needs cash in their bank account yesterday. They focus on speed and simplicity, connecting users with top lenders in just a few minutes without the dread of a hard credit pull during the initial phase.

The process is streamlined to prevent the headache of endless paperwork. With the ability to receive funds in as little as 24 hours, it serves as a high-speed bridge for those facing sudden equipment failures. It is a straightforward solution for those who prioritize velocity over complex financial maneuvering.

Pros:

  • No hard credit pull during the initial rate check.
  • Extremely fast funding, potentially within 24 hours.
  • High maximum loan amount of up to $35,000.

Cons:

  • The speed of funding may depend on the specific lender matched.

3. Flexxbuy

Flexxbuy – flexxbuy.com

For businesses and contractors installing expensive high-ticket HVAC systems, Flexxbuy offers a sophisticated way to close sales. They act as a multi-lender platform that allows customers to see several options through a single application. This turns a massive, intimidating price tag into manageable monthly installments that are much easier to swallow.

It is a powerful tool for scaling a business by making it easier for customers to say yes to premium equipment. With loan amounts reaching up to $100,000, it handles the heavy lifting for major commercial or residential installations. The speed of decision-making is designed to keep the project moving forward without delay.

Pros:

  • High loan limits up to $100,000.
  • Decisions are made in seconds.
  • Access to a wide network of over 35 lenders.

Cons:

  • Primarily designed for businesses to offer to their customers.

4. AmeriCash Loans

AmeriCash Loans – americash.com

Sometimes, the traditional banking route is a closed door. AmeriCash Loans is designed for those who need momentum immediately and might not qualify for standard bank loans. They specialize in short-term cash advances and marketplace lending, making it easier for people to find a lender that fits their specific situation.

The application is built to be simple and secure, moving through a marketplace to find a match. It is a fallback option for those who need to act now but may have a less-than-perfect credit history. While it is a marketplace rather than a single lender, it provides a path to quick decisions.

Pros:

  • Instant approval decisions are possible.
  • Good credit is not a strict requirement.
  • Simple, user-friendly application process.

Cons:

  • Terms and requirements are determined by individual lenders in the marketplace.

5. Roadrunner Financial

Roadrunner Financial – roadrunnerfinancial.com

Roadrunner Financial offers a highly specialized approach to financing, often focusing on various types of vehicle and recreational equipment. However, their “all credit welcome” philosophy makes them a versatile option for those looking for quick, personalized loan offers. They aim to remove the haggling and hassle typically found at the point of sale.

The prequalification process is incredibly fast, taking only about two minutes. This allows you to see what you might qualify for without any commitment or impact on your credit score. It is a low-pressure way to gauge your options before you commit to a major purchase or repair.

Pros:

  • No impact on credit score during prequalification.
  • Very fast, two-minute process.
  • Welcomes all credit scores.

Cons:

  • The service is heavily geared toward specific vehicle/recreational types.

6. NetCredit

NetCredit – netcredit.com

NetCredit positions itself as a modern alternative to traditional banking, operating under the philosophy that you are more than just a number in a database. They offer personal loans and lines of credit that provide a level of flexibility that many rigid banks simply cannot match. It is a human-centric approach to digital lending.

If you need a loan up to $10,000 to get your AC running again, NetCredit provides a path with the potential for same-day funding. Their use of advanced algorithms allows for a more nuanced view of your ability to repay, which can be a lifesaver for those who fall just outside the standard FICO requirements.

Pros:

  • Potential for same-day funding.
  • Flexible terms and loan amounts up to $10,000.
  • A more nuanced approach to credit assessment.

Cons:

  • Loan availability is subject to state-specific regulations and partnerships.

Navigating Your Financing Options

When you are staring at a broken air conditioner in the middle of a heatwave, it is easy to make a rushed decision. Avoid the mistake of signing a lease-to-own agreement without understanding if you would be better off with a traditional loan. While lease-to-own can be easier to get, it is often much more expensive over the life of the agreement.

Always ask for a total cost of ownership breakdown. A low monthly payment might look attractive on the surface, but if the term is 96 months, you could end up paying for the unit three times over. Compare the interest rates across multiple providers and always check for any hidden fees that might sneak into the contract at the last minute.

Another common pitfall is failing to verify the credentials of the contractor alongside the lender. A great financing deal is wasted if the technician installing the unit is not licensed or insured. Ensure that the financing is tied to a reputable professional who provides a clear, written estimate before you sign any loan documents.

The 6 Best Lenders for Bad Credit Loans in Pennsylvania for 2026

Bad credit loans pennsylvania

The 6 Best Lenders for Bad Credit Loans in Pennsylvania for 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Life rarely gives you a heads-up when things go wrong. One minute you are driving through Allentown on a rainy Tuesday, and the next, your transmission gives out completely. Maybe an unexpected ER visit leaves you staring at a medical bill you didn’t see coming, or a sudden Pennsylvania winter sends your heating costs through the roof. These hiccups are stressful enough, but they become a nightmare when a low credit score stands between you and the cash you need to keep the lights on.

When past late payments or high credit card balances have bruised your FICO score, traditional banks often shut their doors. They act more like gatekeepers than helpers, leaving many residents to hunt for alternative lifelines. This is where subprime lending enters the picture, and it requires a sharp eye. You have to be careful, because the goal is to find a solution that doesn’t create a whole new crisis next month.

When you are looking for quick cash, your priorities usually shift. You might stop worrying about finding the absolute lowest interest rate and start focusing simply on finding a lender willing to say yes to your financial history. It is a survival tactic, certainly, but it demands a strategic approach to stay ahead of the curve.

  1. GadCapital
  2. FastLendGo
  3. Credit Human
  4. GreendayOnline
  5. Loanz
  6. OppLoans

Evaluating Lending Options Across the Keystone State

Finding a decent lender in Pennsylvania means looking past the flashy social media ads or the bright neon signs in busy city streets. You need to know how they handle credit checks, how fast the money actually hits your bank account, and what the loan amounts look like when you are in a pinch. A resident in Erie likely has different needs than someone living in Philadelphia.

A commuter might just need a quick loan for an auto repair to get to work. On the other hand, a small business owner might need a bridge loan to cover payroll until the next big contract clears. This ranking looks at the specific needs of people facing these kinds of emergencies. We looked at how quickly funds arrive and whether they offer installment-based options.

Avoiding the debt trap is the real goal. A payday loan that requires full repayment in just fourteen days can easily turn into a cycle of endless renewals. Installment loans are often a better bet because they offer a predictable repayment schedule that fits much better with a standard monthly paycheck. It is the difference between a temporary fix and a long-term struggle.

Lender Name Loan Amounts Credit Requirements Funding Speed
GadCapital $100 – $5000+ No Credit Check Instant/Same Day
FastLendGo $500 – $5000+ Bad Credit Welcome Quick Access
Credit Human From $500 No Credit Review See Site
GreendayOnline $100 – $5000 No Hard Credit Check Same Day
Loanz $100 – $10000 See Site Quick/Convenient
OppLoans See Site Does not affect FICO Same-Day Funding

1. GadCapital

GadCapital – gadcapital.com

GadCapital acts as a direct lifeline for people facing immediate financial trouble. They offer options that don’t require a traditional credit check, which is perfect for a Pittsburgh resident who needs cash right now to pay an overdue rent bill or an urgent utility charge. Their model moves much faster than the slow, bureaucratic verification processes at big national banks.

The platform handles everything from small $100 advances to larger sums over $5000. This flexibility matters. A $100 loan might cover a tank of gas and a few groceries, while a $5000 loan could fix a major emergency repair. It is a specialized choice for those who need to bypass the long scrutiny of conventional banks and need an instant digital response.

Pros:
  • No credit checks required for many options
  • High maximum loan amounts up to $5000+
  • Fast, instant online application process
Cons:
  • High urgency can lead to expensive terms

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is a versatile partner for various personal financing needs. They don’t just look at one type of borrower, either. They offer solutions for auto repairs, dental bills, and even roof repairs. This variety makes them a useful starting point for anyone unsure which specific product will fit their situation. (fastlendgo.com)

Whether you need a $500 boost to get to your next paycheck or a $5000 personal loan to consolidate high-interest debts, they aim to make comparing local options simple. This is a great fit for people facing specific household emergencies, like an HVAC unit failing during a humid Pennsylvania summer.

Pros:
  • Wide variety of loan purposes
  • Handles various credit scores from fair to bad
  • Streamlined online comparison tool
Cons:
  • Focuses on comparison rather than direct lending

3. Credit Human

Credit Human – credithuman.com

If you prefer the stability of a member-owned institution, Credit Human offers a different approach. They provide both secured and unsecured options, allowing members to borrow as little as $500 with more traditional repayment structures. Because they operate as a credit union, they tend to focus more on your ability to repay rather than just a number on a report.

This is a good choice for a long-term planner who wants to build financial health while solving a current problem. Their terms can go up to 72 months, which makes monthly payments much easier to handle on a tight budget. Instead of a massive lump sum due in two weeks, you might pay a small, manageable amount every month to keep your cash flow steady.

Pros:
  • Member-owned structure supports community values
  • Flexible repayment terms up to 72 months
  • No credit review on certain products
Cons:
  • Requires membership to access most benefits

4. GreendayOnline

GreendayOnline – greendayonline.com

GreendayOnline is built for speed. If you are staring at a pile of bills and need an answer fast, this platform moves through the process in minutes. Their digital interface works well on mobile phones, which is helpful since many people in a pinch might be accessing these services on the go via a smartphone.

They offer installment loans from $100 up to $5000. Because they avoid hard credit checks, you can find out where you stand without hurting your credit score further. This “soft pull” approach lets you see your options before you make a final commitment, which is vital if you are cautious about your financial standing.

Pros:
  • Fast approval decisions
  • No hard credit checks required
  • Funds can arrive as soon as the same day
Cons:
  • Strictly online process may lack personal touch

5. Loanz

Loanz – loanz.com

Loanz focuses on debt consolidation. If your financial struggle comes from juggling too many different monthly payments—like multiple credit cards and a medical bill—this lender helps you pull those into one manageable slice. By consolidating, you trade several chaotic due dates for one single, predictable payment.

With loan amounts up to $10,000, they offer a way to regain some control. It is a strategic choice for someone looking to reorganize their financial future rather than just looking for a quick fix. Instead of just trying to “get by,” you are working toward a more organized life.

Pros:
  • Strong focus on debt consolidation
  • Higher loan limits up to $10,000
  • Versatile for weddings, travel, or home improvements
Cons:
  • May require more documentation for higher amounts

6. OppLoans

OppLoans – opploans.com

OppLoans works through a network of bank partners. One of their most useful features is the ability to apply without affecting your FICO score. That is a huge relief for anyone watching their rating closely. Most lenders perform a “hard inquiry” that can drop your score, but OppLoans avoids that during the initial phase.

They offer same-day funding for people in a bind. It is a practical option for a consumer who needs a quick bridge to reach their next paycheck without the stress of a hard inquiry. This makes them a strong choice for short-term gaps that only require a few hundred or a few thousand dollars.

Pros:
  • Applying does not impact FICO scores
  • Same-day funding availability
  • Simple and transparent application process
Cons:
  • Approval is based on bank partner criteria

The True Cost of Subprime Borrowing

Check the math before you sign anything. Subprime lending usually carries higher Annual Percentage Rates (APRs) than traditional loans. A 10% APR might be normal for a prime borrower, but subprime rates can be much higher. This isn’t a scam, it’s just a reflection of the risk the lender takes by lending to someone with a history of late payments.

Don’t just look at the monthly payment. If you borrow $1,000 and the payment is $150, it looks affordable. But if you pay that for 12 months, you’ve paid $1,800 total. That $800 difference is the price of convenience. Always use an APR calculator to see the total cost of the loan over its entire life to avoid sticker shock at the end.

How to Apply Safely

To keep your debt manageable and increase your chances of getting approved, follow these steps:

  1. Identify the Exact Need: Figure out exactly how much you need. Borrowing $2,000 when you only need $1,200 is a mistake that just increases your interest costs.
  2. Check Your Score First: Use a free service to see your own score. This helps you decide if you need a “no credit check” option or if you can qualify for a cheaper, traditional loan.
  3. Compare the Total Cost: Look at the “Total Repayment Amount” rather than just the “Monthly Payment” to see the real impact on your wallet.
  4. Read the Repayment Schedule: Make sure the due dates align with when you get paid. If you get paid on the 1st and 15th, a loan due on the 22nd might cause problems.
  5. Verify the Lender’s Credentials: Make sure you are on a secure site with “https” and the padlock icon before you enter any sensitive bank details.

Lending in Pennsylvania

Choosing a lender shouldn’t be a whim. While instant cash sounds great, you have to read the fine print. A loan that solves a $500 problem today could become a $5,000 problem next year if you don’t understand the terms. The difference between an installment loan and a payday loan is the difference between a controlled climb and a freefall.

Don’t just focus on how fast the deposit arrives. Check if the lender uses hard or soft credit pulls. If you are already struggling, the last thing you want is another hard inquiry on your report. Too many inquiries in a short time can signal to banks that you are desperate for cash, which can drive your score down even further.

Think about why you need the money. If you are consolidating debt, a long-term installment loan like those from Loanz might be smarter than a high-interest payday advance. Match the tool to the task. Use short-term tools for quick gaps, and use long-term tools for structural financial changes.

The 4 Best Lenders for Manufactured Home Financing in 2026

Manufactured home financing

The 4 Best Lenders for Manufactured Home Financing in 2026

Last updated: 2026-10-17

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Finding a place to call home often feels like running a marathon through a thunderstorm. For many, that dream home is a manufactured residence, but walking into a traditional bank can feel like hitting a brick wall. If you have encountered a “no” from standard lenders, you are certainly not alone in this struggle.

The complexity of the manufactured housing sector means that the financing process is rarely a straight line. It is a labyrinth of varying regulations, property classifications, and lender appetites. You have to know exactly what you are looking at before you sign anything.

Selecting the right lender depends entirely on your unique financial footprint. Some buyers need high-speed cash for quick repairs, while others require specialized programs designed specifically for mobile homes. Navigating these waters requires knowing which institutions specialize in your specific credit profile and housing type.

For instance, if you are purchasing a home on leased land, your financing needs will differ vastly from someone who owns the land beneath a manufactured home. Understanding this distinction is the first step toward successful homeownership.

  1. FastLendGo
  2. Triad Financial Services
  3. Sound Community Bank
  4. Fannie Mae

Evaluating the 2026 Manufactured Home Lending Landscape

The criteria for this evaluation focus on specialized product availability and accessibility. A lender’s ability to look beyond a simple credit score is paramount in this niche market. We looked at how these providers handle various credit tiers, from high-income professionals to those rebuilding their financial lives.

In 2026, the landscape has shifted toward more data-driven underwriting. This means that a single mistake in your digital financial footprint can impact your eligibility across multiple platforms. It is no longer just about what a human loan officer thinks of your history.

We also weighed the importance of loan structure and speed. In a fast-moving real estate market, waiting weeks for an answer can kill a deal. Therefore, we prioritized lenders that offer clear paths for different borrower needs, whether that involves traditional mortgage backing or specialized chattel financing.

We specifically looked at the distinction between “chattel loans”—which treat the home as personal property—and “real property” loans, where the home and land are bundled together. The latter often offers lower interest rates but requires much stricter documentation and a higher credit threshold.

Lender Name Loan Types Max Loan Amount Min Credit Score Key Feature
FastLendGo Personal Loans See site See site Quick access to cash
Triad Financial Services Manufactured/Mobile See site See site Specialized financing
Sound Community Bank Manufactured Home $350,000 640 FDIC-Insured
Fannie Mae Single-Family See site See site Desktop Underwriter

Understanding the Critical Distinction: Chattel vs. Real Property Loans

Before you begin your applications, you must understand the two primary ways manufactured homes are financed. This is the most frequent source of confusion for first-time buyers. If you don’t get this right, you might face significant delays in the closing process.

It is better to sort this out now rather than discovering a problem when you are ready to move in. The difference between these two loan types changes everything from your interest rate to how you pay the loan back.

What is a Chattel Loan?

A chattel loan is essentially a personal property loan. It is used when the manufactured home is considered a piece of personal property rather than real estate. This is most common when the home is located in a mobile home park where you lease the land from a park owner.

Because the home is not tied to land you own, the lender views the loan more like an auto loan or a high-end personal loan. These loans are often easier to qualify for if your credit is less than perfect. However, they typically carry higher interest rates and shorter repayment terms, such as 10 to 15 years rather than 30.

What is a Real Property Loan?

A real property loan is a traditional mortgage. This is only an option if the home is permanently affixed to land that you (or a co-borrower) own. In this scenario, the home and the land are combined into a single piece of real estate.

This is the “gold standard” for financing because it offers the lowest interest rates and the longest terms. However, the requirements are much more stringent. You will likely need a formal appraisal that accounts for both the structure and the land, and your credit score will need to meet the higher thresholds set by institutions like Sound Community Bank.

Top Ranked Lenders for Manufactured Home Financing

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo operates as a versatile partner for those needing quick access to cash. Instead of getting bogged down in the complexities of a mortgage, this provider focuses on personal loans that can be used for various needs. It is an ideal choice for those needing to bridge a financial gap quickly.

You might use this to cover the security deposit on a new property or to fund urgent structural repairs on a home you have just acquired. (fastlendgo.com)

This lender caters to a massive spectrum of borrowers. You might find yourself looking for a small $500 loan for an emergency or a larger $5,000 sum for a specific project. They offer tailored solutions for high-income individuals as well as those with less-than-perfect credit histories.

This flexibility makes them a valuable tool in a borrower’s “financial toolkit,” even if they aren’t your primary long-term mortgage provider.

Pros:

  • Extremely fast access to cash for emergencies.
  • Flexible loan amounts ranging from $500 to $5,000.
  • Options available for various credit tiers.

Cons:

  • Personal loan structures may differ from traditional home mortgages.

2. Triad Financial Services

Triad Financial Services – triadfs.com

If you have been told “no” by traditional banks, Triad Financial Services might be the breath of fresh air you need. They specialize in what other lenders won’t touch, specifically manufactured and mobile homes. They have been in the game for over 65 years, providing stability in a volatile market.

Their longevity is a sign of their ability to handle the specific risks associated with manufactured housing. Many other lenders retreat when they see these specific property types, but Triad stays in the fight.

This lender is a specialist in the field of chattel loans. They understand the nuances of manufactured property better than a generalist bank. They know how to evaluate the depreciation of the structure and the specific ways that manufactured homes hold value differently than site-built homes.

If your goal is to secure a home despite a complicated financial past, their experience becomes an invaluable asset during the application process.

Pros:

  • Decades of experience in specialized home financing.
  • Focuses on manufactured homes where others hesitate.
  • Designed for those facing financial hardships.

Cons:

  • Specialized lending may come with different terms than standard mortgages.

3. Sound Community Bank

Sound Community Bank – soundcb.com

Sound Community Bank offers a more traditional banking experience for those purchasing manufactured homes. They provide structured loans with a clear set of requirements. This is a solid option for a buyer who has established their credit and wants the security of an FDIC-insured institution.

Working with a bank like this provides a sense of stability. Your funds are protected under the full faith and credit of the U.S. Government, which offers peace of mind during a major life transition.

The program includes specific parameters, such as a 10% minimum down payment and a minimum FICO score of 640. With loan amounts reaching up to $350,000, they provide a significant amount of breathing room for those looking to make a substantial investment in their property.

Because this is a “real property” style approach, it is highly recommended for those who intend to stay in their home for the long term and want to build equity through traditional means.

Pros:

  • FDIC-insured with the full faith of the U.S. Government.
  • Substantial loan amounts up to $350,000.
  • Clear, predictable lending criteria.

Cons:

  • Requires a minimum credit score of 640.

4. Fannie Mae

Fannie Mae – singlefamily.fanniemae.com

Fannie Mae acts as a massive engine behind the scenes of the American housing market. While they are not a direct lender you walk into on a street corner, their technology and standards drive how many loans are actually made. They provide the framework that many professional lenders use to approve you.

When you hear a lender say they “follow Fannie Mae guidelines,” it means they are using a standardized, highly regulated process. This approach minimizes risk for both the lender and the borrower, making the whole system more predictable.

Their Desktop Underwriter system is a cornerstone of modern mortgage processing. By using advanced data and insights, they help lenders make faster, more accurate underwriting recommendations. This is the gold standard for those looking for highly regulated and standardized single-family financing options.

It reduces the “human error” element of mortgage approval. The result is a more clinical and predictable outcome for the borrower, which can take some of the anxiety out of the process.

Pros:

  • Utilizes advanced Desktop Underwriter technology.
  • Provides massive scale and stability to the market.
  • Offers streamlined pricing through modern credit models.

Cons:

  • Not a direct lender; you must work through a partner.

Preparing Your Financial Portfolio for Approval

Securing a loan for a manufactured home requires more than just a decent credit score; it requires a meticulous level of documentation. Because manufactured homes are often categorized differently than stick-built homes, lenders will be particularly eagle-eyed regarding your ability to repay and the collateral value of the home.

Start by gathering your “Big Three” documents: proof of income, tax returns, and asset statements. For manufactured home buyers, lenders often want to see at least two years of consistent employment history. This consistency proves you can handle the monthly payments over the long haul.

If you are self-employed, prepare for a much deeper dive into your cash flow. You may need to provide several months of bank statements to prove that your income is stable and not just a seasonal spike. Additionally, ensure your debt-to-income (DTI) ratio is as low as possible. Most lenders want to see that your total monthly debt obligations do not exceed 43% of your gross monthly income.

Navigating Your Path to Homeownership

The most common mistake people make is applying for the wrong type of loan for their specific property. A manufactured home is often treated differently than a site-built house. If you apply for a traditional mortgage for a mobile home, you might run into a wall of confusion and delays.

Always ask your potential lender, “Will this be a real property mortgage or a chattel loan?” before you submit a formal application. Knowing this early saves you weeks of frustration and wasted paperwork.

Another pitfall is ignoring the fine print regarding credit scores. Some lenders, like Sound Community Bank, have a specific floor for credit scores. If you fall even a few points below that mark, you might be wasting your time with that particular institution.

It is worth noting that while a score of 640 might get you through the door at one bank, a score of 680 or higher might unlock much more favorable interest rates at another. Always verify your score and the specific models lenders use before you start the paperwork.

Finally, do not wait until the last minute to check your credit. A sudden dip in your score can turn a “yes” into a “no” overnight. This can happen due to a high credit card balance, a small unpaid medical bill, or even a recent inquiry for a new line of credit.

Take the time to clean up your profile, resolve any discrepancies in your credit report, and understand exactly what you bring to the table before you start knocking on doors. A clean, organized profile is your greatest leverage in a negotiation.

Six Best Lenders for a Personal Loan With Collateral in 2026

Personal loan with collateral

Six Best Lenders for a Personal Loan With Collateral in 2026

Last updated: 2026-10-17

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Walking into a secured loan discussion can feel like trying to find a flashlight in a thick fog. When you use an asset like a car or a savings account to back a loan, you are making a serious promise. It is a smart move for anyone looking to snag lower interest rates or get approved when traditional banks say no.

By putting up collateral, you tell the lender that their risk is much lower. This often leads to better terms and higher borrowing limits than an unsecured loan would ever allow. You are essentially trading a piece of your property for more favorable financial conditions.

Choosing a lender requires looking past the shiny marketing. You have to weigh how quickly you need the cash against the risk of losing your property. A sudden engine failure in a vehicle used as collateral or a dip in the stock market can change your loan math overnight.

This list highlights the top players in the 2026 market. We focused on companies that offer stability and speed for different financial needs.

  1. JetzLoan
  2. Best Egg
  3. OneMain Financial
  4. Freedom First Credit Union
  5. Balance Credit
  6. Synchrony

How These Lenders Were Evaluated

We wanted to find lenders that actually use collateral to help a borrower’s profile. Our team looked at how these institutions handle different credit scenarios. This included people with perfect histories and those currently struggling to stay afloat.

It is not just about the total amount of money on the table. The speed of the transaction matters just as much. A lender that makes you wait weeks for paperwork is rarely helpful when you are facing a time-sensitive bill.

Speed of funding, maximum limits, and application ease were our primary metrics. We also checked if a lender requires a hard credit pull during the first inquiry.

Being able to see your potential terms without dinging your credit score is a massive advantage. We specifically looked for lenders offering “soft pulls” for initial quotes. This allows you to shop around without seeing a trail of inquiries on your credit report.

Lender Name Max Loan Amount Funding Speed Credit Impact on Inquiry
JetzLoan $35,000 As little as 24 hours No hard credit pull
Best Egg $50,000 See site See site
OneMain Financial $30,000 As soon as 1 hour No credit score impact
Freedom First Credit Union See site See site See site
Balance Credit $4,000 Next business day No impact on credit score
Synchrony See site See site See site

Top Rated Lenders for Secured Funding

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan works like a high-speed bridge for people who need cash without the usual waiting games. They connect borrowers with top lenders in just a few minutes. This makes them a great choice for emergencies.

If you need money for an urgent medical bill or an unexpected home repair, their ability to deposit funds within 24 hours is hard to beat. (jetzloan.com)

This lender is great if you are wary of the “credit score dance.” They offer a way to check your rate without a hard credit pull. You can explore options without fearing a lower score.

This is vital if you plan to apply for a mortgage or an auto loan soon. You cannot afford any fluctuations in your credit profile right now. It is a transparent, digital-first approach.

Pros:

  • Funds deposited as quickly as 24 hours.
  • No hard credit pull during the initial check.
  • High maximum loan limit of $35,000.

Cons:

  • Acts as a connector rather than the sole lender.

2. Best Egg

Best Egg – bestegg.com

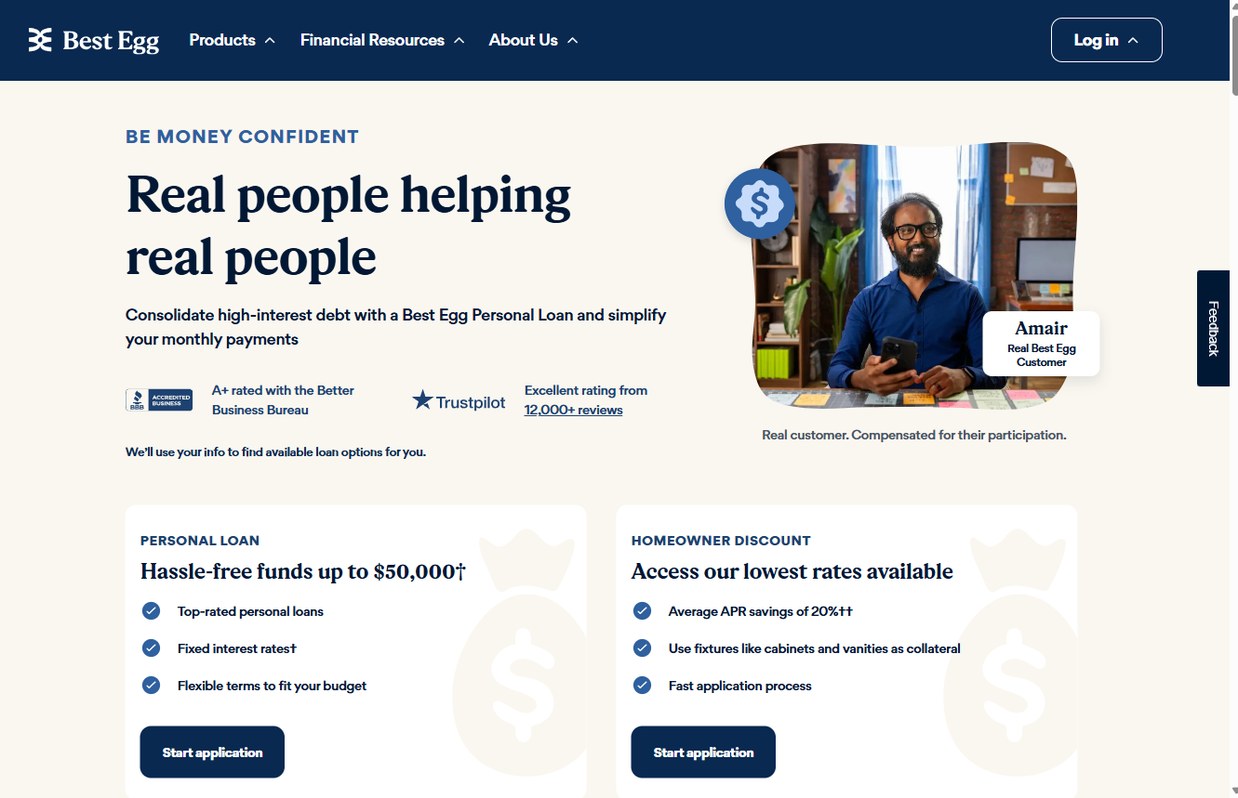
Best Egg is a heavyweight in the personal loan space. They are known for a straightforward approach. They offer products designed to help users consolidate high-interest debt.

If you are carrying multiple balances on high-interest credit cards, a single Best Egg loan can merge them into one manageable monthly payment. You often see a significantly lower APR this way.

One interesting feature is their ability to use household fixtures as collateral. You can use things like cabinets or vanities. This unconventional method can open doors for homeowners who might otherwise struggle.

It is a specialized form of secured lending. It treats home improvements as an asset, providing a pathway for equity-based borrowing without the complexity of a full home equity loan.

Pros:

  • High loan amounts up to $50,000.
  • Potential for 20% APR savings.
  • Homeowner discounts available.

Cons:

  • Terms and rates are subject to specific eligibility.

3. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a powerhouse for those who want a mix of digital ease and physical presence. With over 1,300 branches, they offer a human touch. Many online-only lenders simply cannot compete here.

If you get stuck in a digital loop or struggle to upload documents, you can walk into a branch. You can talk to a real person face-to-face. This physical presence provides a layer of security that purely digital fintechs often lack.

They are a standout choice for borrowers with less-than-perfect credit. You can see your options in five minutes without a credit score impact.

For urgent needs, like a car repair that prevents you from getting to work, they can provide funds as soon as one hour after signing. This speed is vital in “make or break” financial moments.

Pros:

  • Extremely fast funding (1 hour post-signing).
  • Extensive branch network for in-person support.
  • Flexible terms from 24 to 60 months.

Cons:

  • Maximum loan amount is capped at $30,000.

4. Freedom First Credit Union

Freedom First Credit Union – freedomfirst.com

Freedom First Credit Union operates with a community-centric mindset. This sets them apart from big-box banks. They offer secured personal loans where you can use share accounts or certificates as collateral.

This is a stable way to build credit while accessing capital. Because you are borrowing against your own savings, interest rates are typically much lower. The approval process is often simpler since the risk to the credit union is minimal.

They also provide perks like early access to paychecks through direct deposit. This flexibility helps with cash flow management. You can time your payments more effectively against your income cycle.

For those who value local involvement, their “Play for Purpose” programs show a commitment to local causes. It fosters a sense of mutual benefit between the institution and its members.

Pros:

  • Community-focused service model.
  • Options to use share accounts as collateral.
  • Perks like getting paid up to 2 days early.

Cons:

  • Likely requires membership through specific criteria.

5. Balance Credit

Balance Credit – balancecredit.com

Balance Credit is a specialized option for those needing quick, smaller amounts of cash. They offer loans up to $4,000. This makes them a niche player compared to the giants.

Their focus is on inclusivity. They review applications even for those with less-than-perfect credit. This makes them a vital resource for short-term liquidity needs where a massive loan isn’t necessary.

Their process is incredibly fast. Money can hit your account by the next business day. One of their most attractive features is the lack of penalties for paying off a loan early.

This can save you significant interest over time. If you get a tax refund or a bonus, you can wipe out the debt immediately. You won’t face “prepayment penalties” like you might at larger banks.

Pros:

  • No penalties for early loan payoffs.
  • Inclusive consideration for various credit levels.
  • Quick application process.

Cons:

  • Relatively low maximum loan amount of $4,000.

6. Synchrony

Synchrony – synchrony.com

Synchrony operates primarily through marketplace and financing models. They are often tied to specific retail brands. This makes them a specialized choice rather than a general-purpose lender.

They are the go-to for people looking to finance specific purchases through retail partnerships. For example, if you are buying high-end appliances, Synchrony might offer 0% interest promotional periods.

They offer various services, including credit cards and marketplace financing. While they might not be your first choice for a general cash infusion for utility bills, their specialized financing is excellent for large purchases.

Their integration into major retailer checkouts makes the transition from “browsing” to “financing” almost instantaneous. It is a very smooth experience for targeted credit options.

Pros:

  • Strong retail-specific financing options.
  • Diverse range of credit products.
  • Part of a large, established financial ecosystem.

Cons:

  • Less focused on general-purpose personal loans.

Understanding Collateral Types and Risks

Before committing to a secured loan, you must understand exactly what you are offering. Collateral generally falls into three categories: liquid assets, physical property, and financial instruments. Each has a unique risk profile.

Liquid assets, like savings accounts or CDs, are the safest for the lender. They are often the cheapest for you too. If you use $5,000 in a savings account as collateral, the interest rate is typically very low.

The downside is that the money is “locked.” You cannot use that $5,000 for other expenses while the loan is active. This effectively reduces your available cash reserves when you might need them most.

Physical property, specifically vehicles, is a very common form of collateral. While this allows for larger loan amounts, it introduces “depreciation risk.” The value of your car drops every year.

If you take out a $15,000 loan on a car worth only $12,000 due to high mileage, you are “underwater.” You owe more than the asset is worth. This creates a massive burden if you need to sell the car or default.

Financial instruments, including stocks or bonds, offer high borrowing potential. However, they come with extreme volatility. If the market takes a sharp downturn, your lender may issue a “margin call.”

They might require you to deposit more cash immediately. If you cannot, they can force the sale of your investments at a loss. This requires high financial literacy to manage safely.

The Step-by-Step Guide to Securing a Loan

Securing a loan requires a systematic approach. You want the best terms without accidentally damaging your financial health. Follow these steps to move through the process efficiently:

  • Step 1: Audit Your Assets. Before applying, list everything you could use as collateral. Note the current market value, not the original purchase price. For vehicles, check Kelly Blue Book. For home fixtures, consider replacement costs. Have your titles and statements ready.

  • Step 2: Check Your Credit Score (Soft Pull). Use the “no credit impact” features from lenders like JetzLoan or OneMain Financial. This gives you a baseline. Knowing your score helps you see if you qualify for “prime” rates or more expensive “subprime” options.

  • Step 3: Compare the APR, Not Just the Interest Rate. The interest rate is just the cost of the principal. The Annual Percentage Rate (APR) includes fees and points. A 5% interest rate with $500 in fees might be more expensive than a 6% rate with zero fees. Always use the APR for an apples-to-apples comparison.

  • Step 4: Evaluate the Repayment Timeline. A longer term, like 60 months, means lower monthly payments. This helps your monthly cash flow. However, you will pay significantly more in total interest. Calculate the “total cost of the loan” to see the real price tag.

  • Step 5: Review the Default Terms. Read the section on “remedies upon default.” You need to know how many missed payments trigger a default. Also, check how much notice the lender must give before they seize your collateral. This “grace period” is vital.

Avoiding Common Pitfalls in Secured Lending

The biggest mistake is underestimating the weight of collateral. When you put your car or savings on the line, you are telling the lender, “If I fail, you take this.” It is a high-stakes game.

You need a clear-eyed view of your budget. A common psychological trap is thinking, “I can always pay it back later.” The legal reality of a secured loan is rarely that flexible.

Always read the fine print regarding defaults. Some lenders are much more aggressive than others. Some might repossess a vehicle after a single missed payment. Others might offer a structured workout plan.

Keep a close eye on the total cost of borrowing. A lower interest rate might look enticing, but high fees can change everything. Watch out for “origination fees” taken from your loan amount upfront. You might receive $9,500 even though you signed for $10,000.

Finally, do not rush the process just because you are in a pinch. Speed is important, but taking an extra hour to compare terms can save you thousands. Use “no credit impact” checks to do your homework without consequence.