Top 5 Lenders for Bad Credit Loans in North Carolina: 2026 Rankings

Bad credit loans north carolina

Top 5 Lenders for Bad Credit Loans in North Carolina: 2026 Rankings

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Trying to balance your books in North Carolina can feel like trekking through a dense swamp when your credit score isn’t exactly stellar. Many residents find themselves facing unexpected car repairs, like a sudden transmission failure in Raleigh, or urgent medical bills from a trip to an urgent care center in Charlotte. These unexpected costs require immediate cash to keep life moving forward without a hitch.

These financial shocks can derail a monthly budget in a single afternoon. Suddenly, families find themselves scrambling to cover essential costs like rent or electricity. It is a stressful position to be in when the money you set aside for groceries is suddenly needed for a utility bill.

Finding the right lender involves more than just glancing at the interest rate. You have to weigh speed and accessibility against the total cost of borrowing. A loan with a lower interest rate might seem attractive on paper, but if it takes ten business days to fund, it won’t help you if the power company is threatening to shut off your electricity tomorrow.

On the flip side, a “quick cash” option might provide the speed you need, but it could carry an APR that makes the total repayment much higher than you expected. This list clarifies which options might suit your specific situation during uncertain times. It helps you weigh the trade-offs between immediate liquidity and long-term affordability.

  1. FastLendGo
  2. Addition Financial
  3. PaydayPact
  4. Credit Human
  5. LoanStart

Evaluating Financial Assistance Across the Tar Heel State

The selection process for this ranking focused on how easily a borrower can secure funds when their credit history is less than perfect. We looked at the ease of the application process and the speed of funding. We also considered the flexibility offered to those with subprime scores.

We specifically scrutinized the user experience for ease of use. We noted whether applications could be completed on a smartphone while waiting in line at a clinic, or if they required a desktop computer and a pile of scanned documents. Convenience often dictates whether a lender is actually helpful in a crisis.

In North Carolina, high interest rates are a common side effect of easy approval. Because the risk to the lender is higher when a borrower has a low credit score, the price of that risk is reflected in the APR. Therefore, the ranking prioritizes lenders that provide clear pathways for those who might have been turned away by traditional big-box banks earlier in the week.

We looked for transparency in every option. We wanted to know: does the lender show the total repayment amount upfront, or do you only find out after you have signed the digital agreement? Knowing the final number before you commit is essential for anyone trying to manage a tight budget.

Lender Name Loan Amounts Credit Requirements Funding Speed Terms
FastLendGo $500 – $5,000 Bad Credit / Fair Credit Same day or next business day see site
Addition Financial see site see site see site see site
PaydayPact see site Guaranteed approval online see site see site
Credit Human As little as $500 No credit review see site Up to 72 months
LoanStart Up to $40,000 see site see site see site

Ranking the Best Options for North Carolina Borrowers

1. FastLendGo
FastLendGo – fastlendgo.com

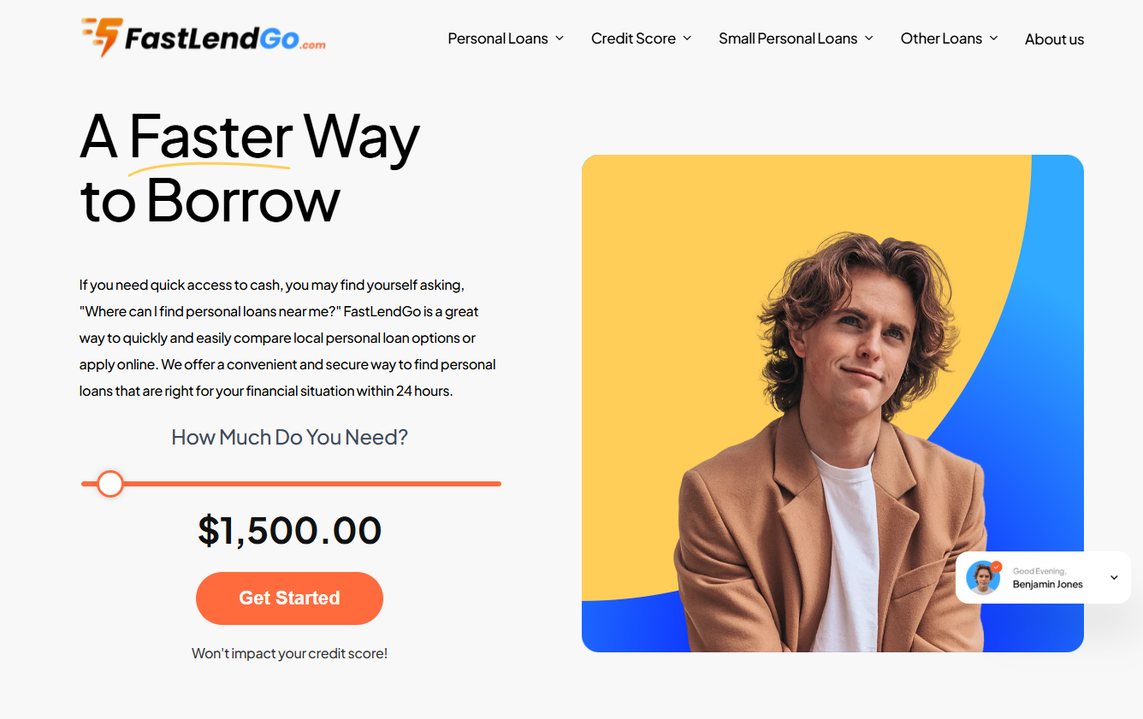
FastLendGo works well for those needing quick cash to cover immediate emergencies. Whether it is a sudden dental bill or a necessary auto repair, this service focuses on getting money into your hands without the usual mountain of paperwork. The streamlined digital interface is built for the modern consumer who needs to solve a problem in minutes rather than days. (fastlendgo.com)

This option is particularly suited for individuals who need specific amounts. You might need a $500 loan for a grocery bill gap or a $2,000 personal loan to fix a leaking roof. It caters to a wide spectrum of credit profiles, from those with bad credit due to a recent medical emergency to those with fair credit looking to build a better financial standing through consistent on-time repayments.

Pros:

  • Offers various loan sizes from $500 to $5,000.
  • Fast funding, potentially arriving the same day.
  • No minimum credit score required to qualify.

Cons:

  • Limited to specific smaller loan amounts.

2. Addition Financial
Addition Financial – additionfi.com

Addition Financial focuses on comprehensive banking needs beyond just quick cash injections. They offer a suite of products including checking accounts, credit cards, and mortgages. This makes them a more traditional choice for those looking to build a long-term relationship with a financial institution rather than just finding a one-off solution.

For members looking to grow their assets, they provide savings options and competitive rates. It is a solid choice if you want a stable institution rather than just a quick fix for an immediate financial crisis. If your goal is to move away from the high-interest cycle and toward traditional banking, this is a logical step.

Pros:

  • Diverse range of banking products.
  • Potential for earning through referrals.
  • Comprehensive financial services.

Cons:

  • May require more extensive documentation than quick-cash lenders.

3. PaydayPact
PaydayPact – paydaypact.com

PaydayPact acts as a highly accessible digital portal for those facing rejection elsewhere. Their online system is designed to be secure and user-friendly. You can apply from any device, whether you are on a phone while commuting on a bus in Durham or on a laptop at home. This accessibility is crucial for people who may not have a fixed desk or a printer for paperwork.

The primary draw here is the promise of guaranteed approval online. This is a lifeline for someone who needs certainty in a moment of financial chaos. When you are facing a late fee on a rent payment, knowing you will get a “yes” or “no” immediately can significantly reduce the psychological stress of the situation.

Pros:

  • High accessibility via mobile devices.
  • Secure online application process.
  • Focused on guaranteed approval.

Cons:

  • High interest rates are common with this type of model.

4. Credit Human
Credit Human – credithuman.com

Credit Human offers a more structured approach to borrowing with fixed rates. They provide a safety net for those who need to borrow as little as $500, but want the stability of a set repayment schedule. Because the rates are fixed, you won’t have to worry about your monthly payment changing unexpectedly due to market fluctuations.

One of their standout features is the ability to borrow without a traditional credit review. This makes them a very strong contender for anyone in North Carolina who is tired of being judged solely by a three-digit number on a screen. They may look at your broader financial stability, making them an excellent option for those who have had a temporary setback but are otherwise reliable.

Pros:

  • Flexible repayment options up to 72 months.
  • No credit review required for some products.
  • Fixed rates provide predictability.

Cons:

  • Terms can be long, leading to more total interest paid.

5. LoanStart
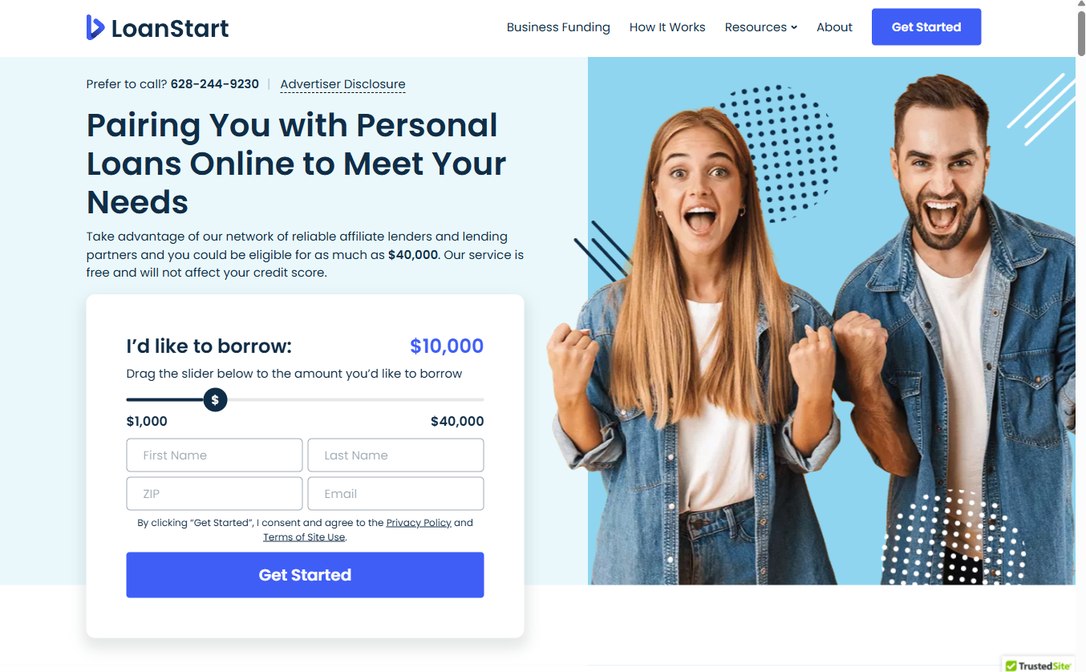
LoanStart – loanstart.com

LoanStart functions as a matching service that connects borrowers with a network of affiliate lenders. Instead of looking at one single bucket of money, you are looking at a wide net of potential partners that might fit your specific needs. This is helpful because “one size does not fit all” in the lending world; what works for a student might not work for a small business owner.

This is the heavy hitter for those who need larger sums, with the potential to access up to $40,000. It is a great option for those who have maxed out credit cards and need a larger, structured installment loan to consolidate debt. By rolling several high-interest credit card balances into one larger loan, you can simplify your monthly finances and potentially save hundreds of dollars in interest over time.

Pros:

  • Potential for high loan amounts up to $40,000.
  • Free service that does not affect your credit score.
  • Connects you to a wide network of partners.

Cons:

  • You are at the mercy of the affiliate lender’s specific terms.

Comparing Loan Types: Quick Cash vs. Installment Loans

Understanding the difference between loan types is vital for North Carolina residents trying to manage their debt. Most lenders fall into one of two categories: Short-term/High-interest or Long-term/Installment loans. Choosing the wrong one can lead to a cycle of borrowing that is difficult to break.

Feature Short-Term Loans Installment Loans
Typical Duration Days to a few months 12 to 72 months
Interest Rates Very High (Often 300%+) Moderate to High (10% – 36%)
Best Use Case Immediate emergencies (e.g., a $200 utility bill) Debt consolidation or large repairs (e.g., a $3,000 car engine)
Repayment Structure Lump sum or frequent small payments Fixed monthly installments

If you are facing a one-time expense that will be cleared by your next paycheck, a short-term loan might be the fastest path. However, if the amount you need is larger than your next two paychecks combined, an installment loan is a much safer way to avoid a “debt trap.”

Strategies for Managing Debt After Borrowing

Securing funds is only the first step; the second, and often more difficult, step is managing the repayment. Many North Carolina residents find themselves in a position where they have successfully resolved their immediate crisis but are now burdened by the new loan. To avoid this, consider these three proactive steps:

  1. Automate Your Payments: Set up automatic transfers from your checking account to the lender the day after you receive your paycheck. This ensures you never miss a payment, which is crucial for protecting your credit score.
  2. Prioritize High-Interest Debt: If you have multiple loans, use the “avalanche method.” This involves paying the minimum on all loans but putting every extra dollar toward the loan with the highest interest rate first. This mathematically minimizes the total amount of interest you pay over time.
  3. Negotiate with Creditors: If you are borrowing because you cannot pay a medical bill or a utility bill, call the provider *before* you take out a loan. Many companies have hardship programs or can offer a payment plan that is much cheaper than the interest rate on a quick-cash loan.

Avoiding Common Pitfalls When Borrowing

When you are in a pinch, it is easy to sign a contract without reading the fine print. Always look for the “total cost of credit,” which tells you exactly how much you will have paid back by the end of the loan term. For example, a $1,000 loan with a high interest rate might require you to pay back $1,500 over six months. That $500 difference is the “cost” of the convenience.

Avoid the trap of taking out a loan just to pay off another high-interest debt unless the new loan has a significantly lower rate. If you are using a high-interest payday loan to pay off a credit card, you are effectively moving the debt from one expensive bucket to an even more expensive one. If you find yourself constantly cycling through short-term loans, you might be stuck in a debt spiral that is hard to escape. This is often a sign that the underlying budget needs restructuring rather than more credit.

Lastly, verify the legitimacy of the lender before providing any sensitive information. While the digital age makes borrowing easy, it also makes it simple for bad actors to mimic real companies. Scammers often use aggressive language, like “You have been pre-approved! Act now or lose the offer!” to pressure you into giving up your Social Security number or bank login details. Always use official, secure websites to protect your identity and your wallet. Look for the “https://” in the URL and ensure the site has a padlock icon in the address bar before entering any personal data.
Top 6 Lenders for Loans for Postal Employees with Bad Credit in 2026

Loans for postal employees with bad credit

Top 6 Lenders for Loans for Postal Employees with Bad Credit in 2026

Last updated: 2026-10-17

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Managing money while working long, exhausting shifts at the post office can feel like trekking through deep snow. Life often throws a curveball that a standard paycheck cannot catch in time. For many postal workers, a sudden car repair or an unexpected medical bill requires cash that traditional banks often refuse to provide quickly.

When you are balancing the physical toll of a mail route with the mental strain of household expenses, a financial hurdle can feel impossible to clear. If your credit score takes a dip, the path to funding becomes a winding road. It is not just about finding any money; it is about finding a partner that understands the stability of government employment.

A traditional bank might see a temporary drop in your FICO score as a reason to deny you. Specialized lenders, however, recognize the long-term reliability of a federal paycheck. This ranking looks at how different lenders treat those who need a hand up, focusing on accessibility, speed, and how much they actually understand your situation.

  1. USPS Federal Credit Union
  2. Federal Employee Loans
  3. JetzLoan
  4. BMG Money
  5. Acorn Finance
  6. Credit Ninja

How These Lenders Were Evaluated

Finding a reliable source of capital requires looking past the shiny advertisements and “instant approval” banners online. This evaluation focused on how well each lender accommodates the specific reality of postal employees. We looked at whether they require a high FICO score or if they prioritize the stability of a federal paycheck through methods like payroll allotments.

For a postal worker, proving income through a steady, government-backed salary is often more important than a perfect credit history. We prioritized lenders that recognize this distinction. We also weighed speed against cost. A lender that provides funds in twenty-four hours is a lifesaver for an emergency, like a transmission failure on a delivery vehicle.

However, the interest rate determines if that lifesaver becomes a heavy weight later. We scrutinized loan amounts, repayment flexibility, and whether the application process would ding a credit score before a decision is even made. We specifically looked for “soft pull” options—processes that allow you to see your potential rate without the permanent damage of a “hard inquiry.”

Lender Name Loan Amounts Terms Funding Speed Credit Requirements
USPS Federal Credit Union Up to $15,000 See site See site See site
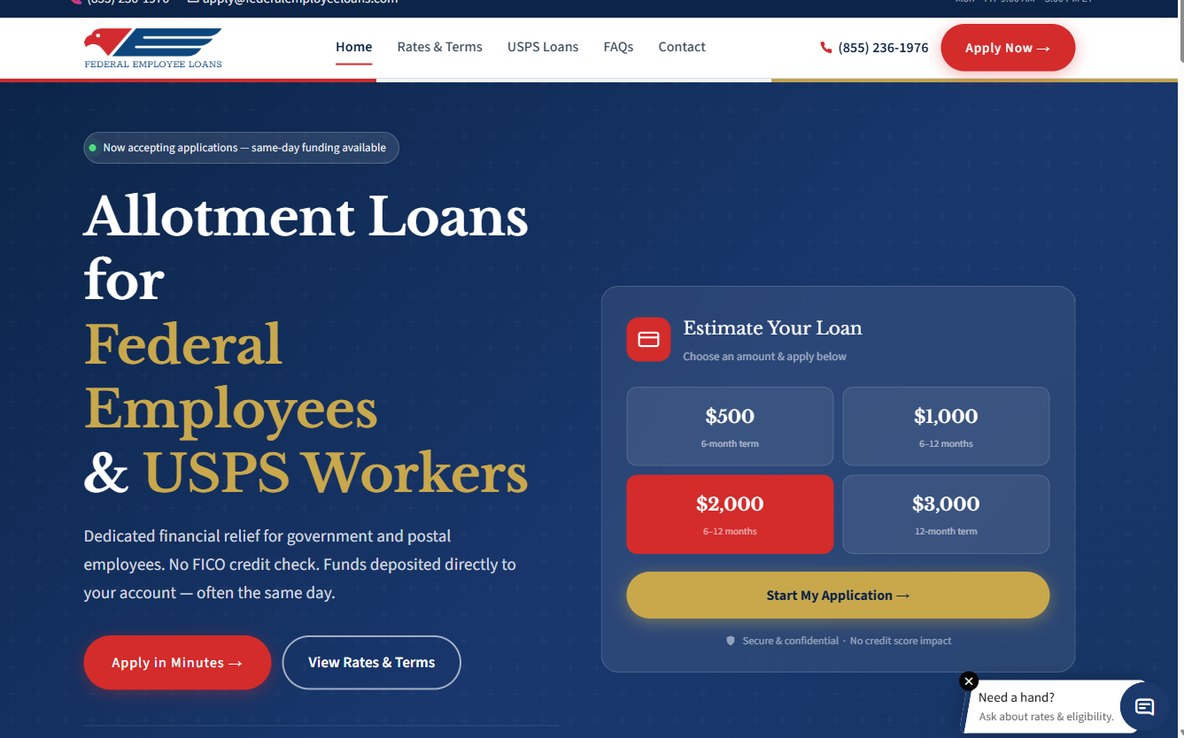
Federal Employee Loans $500 – $3,000 6 – 12 months Same-day No FICO check
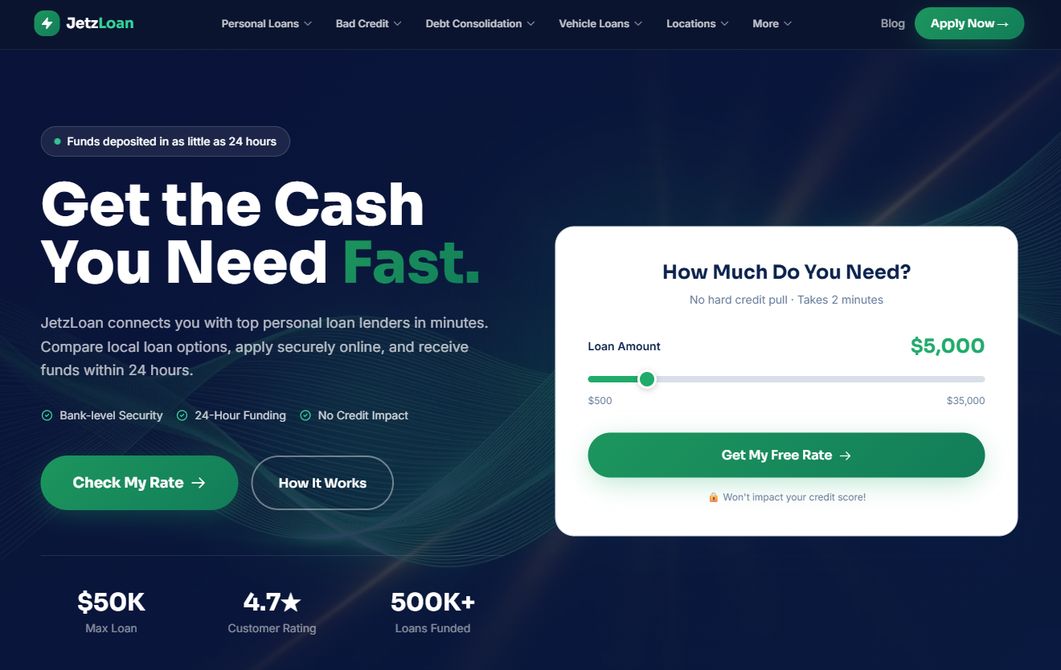
JetzLoan Up to $35,000 See site Within 24 hours No hard pull
BMG Money $500 – $12,000 6 – 48 months Instant availability Regardless of score
Acorn Finance See site See site See site No score impact
Credit Ninja See site See site Same day decision See site

Ranking of Best Lenders for Postal Workers

1. USPS Federal Credit Union

USPS Federal Credit Union – uspsfcu.org

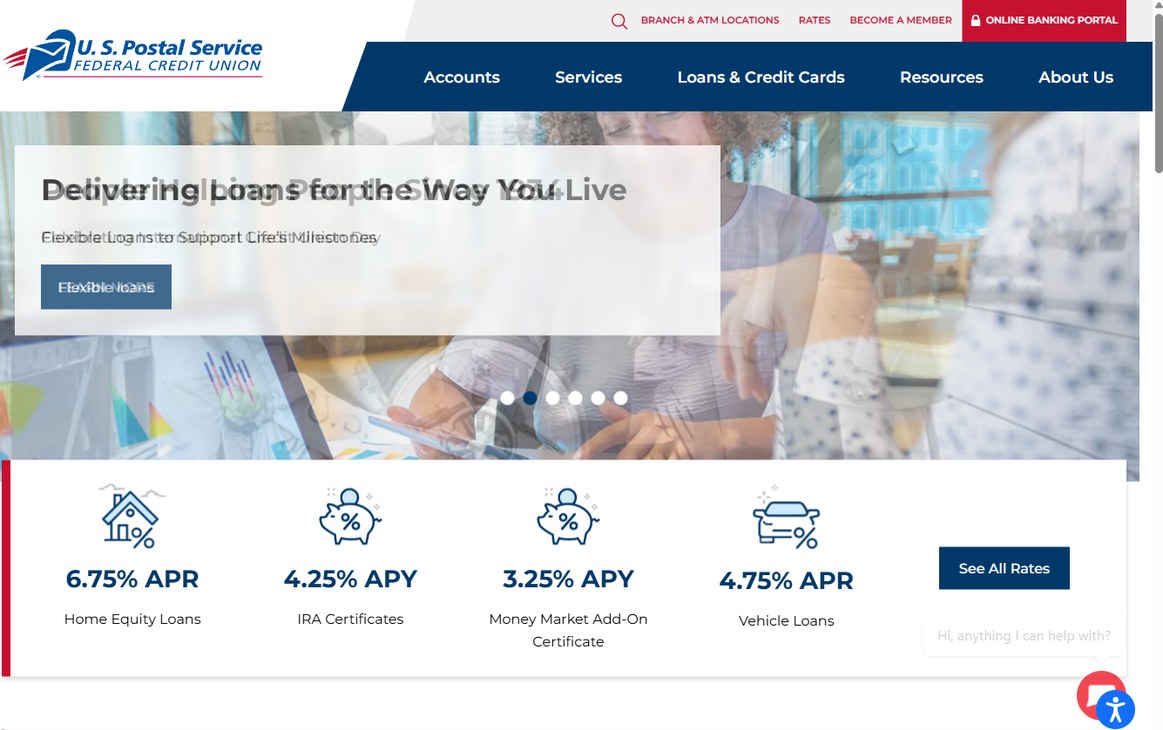
Serving the community since 1934, this institution is built on the idea of “people helping people.” For a postal employee, there is a certain comfort in working with a credit union that shares your professional roots. They offer a sense of belonging that a massive, faceless national bank simply cannot replicate.

Because credit unions are member-owned nonprofits, their primary goal is to serve their members rather than maximize profits for distant shareholders. They provide various options, including personal loans that can reach up to $15,000. These are designed to help with life’s milestones or unexpected hurdles, such as consolidating high-interest credit card debt or covering a sudden move.

Because they understand the nuances of federal employment—including how pay raises and seniority-based adjustments work—their products often feel tailored to the specific lifestyle of a dedicated postal worker. When you speak with them, you aren’t just an account number; you are part of the institution’s history.

Pros:

  • Tailored specifically for USPS employees
  • Personal loans up to $15,000
  • Flexible terms for various life needs

Cons:

  • May require membership or specific eligibility

2. Federal Employee Loans

Federal Employee Loans – federalemployeeloans.com

Sometimes, you don’t need a massive windfall; you just need a bridge to get you to the next payday. This lender specializes in allotment loans, which are designed specifically for the government and USPS workforce. An allotment is a way to have a portion of your paycheck automatically diverted to repay a loan.

This provides a level of security to the lender that allows them to offer much more lenient terms to the borrower. This is a straightforward approach for those who need a quick fix without the headache of traditional underwriting. The beauty of this service lies in its simplicity.

They do not care about your FICO score, focusing instead on your status as a federal worker and your ability to demonstrate a steady stream of income through your pay stubs. If you need a small amount to keep the lights on or keep the tank full, this is a direct and efficient route. It is the digital equivalent of a small, helpful nod from a colleague on the loading dock.

Pros:

  • No FICO credit check required
  • Same-day funding for quick relief
  • Small, manageable loan amounts

Cons:

  • Lower maximum loan amounts compared to others

3. JetzLoan

JetzLoan – jetzloan.com

In a world where everything moves at the speed of a fiber-optic connection, waiting weeks for a loan is a relic of the past. JetzLoan focuses heavily on velocity, aiming to get funds into your account within a single day. It is built for the person who needs cash yesterday—perhaps because an appliance broke or an urgent repair is required.

They act as a bridge, connecting you with various lenders so you can compare options without the fear of a credit score penalty. This marketplace model is highly advantageous. Instead of you applying to ten different banks and receiving ten different “hard pulls” on your credit report, JetzLoan allows you to see what you qualify for with a single inquiry.

It is a modern solution for those who want to see their options clearly without playing a dangerous game of “guess the interest rate.” You get to see the reality of your options without the stress of multiple applications.

Pros:

  • Funds can arrive in as little as 24 hours
  • No hard credit pull during the inquiry
  • High maximum loan limit of $35,000

Cons:

  • Acts as a marketplace rather than a direct lender

4. BMG Money

BMG Money – bmgmoney.com

Life is about more than just a number on a credit report. BMG Money operates on the philosophy that your potential isn’t defined by a score. They cater specifically to employees and retirees who are working toward a better financial future but need assistance right now. They recognize that a credit score is a snapshot of the past, whereas your current employment and future earnings are much better indicators of your reliability.

Their loans are versatile, ranging from $500 all the way up to $12,000. This range makes them useful for everything from minor repairs to more significant debt consolidation efforts. For example, instead of paying 25% interest on several different store credit cards, you could use a BMG Money loan to combine those debts into one single monthly payment.

They aim to be a partner in your financial wellness journey, offering a path toward stability. It is a practical way to clean up your finances with a more manageable interest rate and a single monthly deadline.

Pros:

  • Available regardless of credit score
  • Instant funding options available
  • Flexible terms up to 48 months

Cons:

  • Interest rates can be higher for some borrowers

5. Acorn Finance

Acorn Finance – acornfinance.com

If your financial need is tied specifically to improving your home, Acorn Finance is a specialist in that niche. They focus on contractor financing, making it easier to fund home improvement projects even if your credit isn’t pristine. This is particularly useful for postal workers who may have spent years investing in their community and are now looking to invest in their own property’s value.

They pride themselves on a transparent process where you can check rates without impacting your credit. It is an excellent way to see what is possible for a kitchen remodel, a new roof, or a new deck without the stress of a formal application. By streamlining the connection between the homeowner and the contractor-focused lender, they remove much of the friction typically found in home improvement financing.

Pros:

  • Zero dealer fees for contractors
  • No credit score impact when checking rates
  • Excellent customer reviews on Trustpilot

Cons:

  • Primarily focused on home improvement projects

6. Credit Ninja

Credit Ninja – creditninja.com

When traditional banks slam the door shut, Credit Ninja is often the one standing in the hallway with an open one. They specialize in helping those who might not qualify for standard personal loans, such as individuals with recent credit hiccups or those with a limited credit history. Their application process is designed to be quick, simple, and incredibly fast.

They remove the bureaucratic red tape that often stops small loans in their tracks. The goal here is to provide a solution for life’s unexpected expenses when you feel like you’ve run out of options. If you can’t find a “yes” elsewhere due to a specific credit issue, their installment loans might provide the breathing room you require.

It is a safety net for those navigating the more turbulent waters of the credit system. They offer a way forward when other doors seem permanently locked.

Pros:

  • Fast, same-day decisions
  • Simple and quick online application
  • Designed for those with non-traditional credit

Cons:

  • May not be suitable for all credit situations

Common Pitfalls to Avoid When Borrowing

Before you sign your name on a loan agreement, it is vital to understand the mechanics of what you are agreeing to. Many borrowers fall victim to “teaser rates” or misleading marketing that highlights a low monthly payment while burying the total cost of the loan in the fine print. To avoid these traps, always ask for a “Total Cost of Loan” breakdown.

This figure tells you exactly how much cash will leave your pocket from the first payment to the very last one. Consider these three specific areas of caution:

  • The Prepayment Penalty: Some lenders charge a fee if you try to pay the loan off early. If you receive a bonus or a tax refund and want to clear your debt, you shouldn’t be punished for being responsible. Always look for loans with “no prepayment penalties.”
  • The Origination Fee: This is a fee charged by the lender for processing the loan, often taken directly from the funds you receive. If you need exactly $2,000 for a repair, a lender with a 5% origination fee will only send you $1,900. Always verify the “net proceeds” you will receive.
  • Variable vs. Fixed Rates: A variable rate might start low, but if the economy shifts, your monthly payment could climb significantly. For a fixed monthly budget, a fixed-rate loan is almost always the safer, more predictable choice.

How to Prepare Your Application for Success

Even when working with lenders who are flexible on credit scores, being prepared can significantly increase your chances of approval and help you secure a better rate. Lenders want to see that you are organized and that your income is verifiable. Taking thirty minutes to gather your paperwork beforehand can prevent a delay that could leave you without funds when you need them most.

Follow these steps to streamline your application process:

  1. Gather Proof of Income: Have your most recent two or three pay stubs ready. For USPS employees, having your most recent W-2 handy is also helpful for confirming your annual earnings and employment duration.
  2. Verify Your Expenses: A lender will look at your “debt-to-income ratio.” This is the amount of your monthly income that goes toward paying off existing debts. Knowing your monthly totals for rent, car payments, and other loans will help you estimate what you can realistically afford.
  3. Check Your Details: Ensure your address, employer information, and contact details match your official documents exactly. Discrepancies between your application and your bank records can trigger automatic fraud flags, causing unnecessary delays.
  4. Review Your Credit Report: Even if you are applying for a “no credit check” loan, it is wise to know what is on your report. If there is an error—such as an incorrect late payment—correcting it now can help you qualify for better terms with other lenders in the future.

Choosing a lender is a bit like choosing a pair of work boots. You need something that fits your specific situation, provides the right amount of support, and won’t fall apart when things get heavy. The most important thing is to look at the total cost of borrowing, not just the monthly payment.

Avoid the trap of only looking at the “easy” part of the application. A lender that says “no credit check” is a lifesaver today, but the interest rates can be quite steep. Always calculate the total amount you will have paid back by the end of the term. It is better to know the truth upfront than to be surprised by a mountain of interest later.

Finally, remember that your employment status is a powerful tool. Many lenders view postal workers as reliable because of the stability of the job. Don’t be afraid to mention your professional background or look for lenders that specifically cater to federal employees, as this can often unlock better terms and more favorable views of your ability to repay.

The 6 Best Lenders for RV Financing Ranked for 2026

Rv financing

The 6 Best Lenders for RV Financing Ranked for 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Hitting the open road in a luxury motorhome or a cozy travel trailer is a dream for many. However, the sticker price of a modern recreational vehicle can often feel like a mountain too high to climb without the right financial partner. Unlike a standard passenger car, an RV is often a hybrid asset—part vehicle, part home, and part lifestyle investment. Because of this dual nature, the financing landscape is significantly more complex than traditional auto lending.

Finding a lender that understands the nuances of lifestyle vehicles is essential. Whether you are looking for a second home on wheels or a weekend camper, the right financing determines how much freedom you actually enjoy once the engine starts. A high-interest rate or an inflexible repayment schedule can quickly turn a dream vacation into a financial burden that keeps you parked in your driveway instead of exploring the national parks.

  1. FastLendGo
  2. My Financing USA
  3. Southeast Financial
  4. GreatRVLoan
  5. GadCapital
  6. Manhattan Bank

How We Evaluated the Top RV Financing Options

Selecting a lender isn’t just about chasing the lowest interest rate. It involves looking at the speed of the approval process, the flexibility of the terms, and whether the company handles various types of credit profiles. A lender that is great for a luxury coach might be terrible for a used camper van. For example, a lender specializing in high-end diesel pushers may require a massive down payment and proof of significant liquid assets, whereas a lender focused on used trailers might prioritize collateral value and secondary market stability.

Our evaluation framework looked at several critical dimensions:

  • Loan Structure: Does the lender offer fixed-rate loans (which provide stability) or variable rates (which might start lower but can increase)?
  • Asset Versatility: Can they finance a new Class A motorhome, a used pop-up camper, or even a specialized recreational asset like a boat or jet ski?
  • Speed of Funding: How quickly can the funds be disbursed once the deal is struck at the dealership?
  • Credit Inclusivity: Does the lender have pathways for those with a “thin” credit file or those recovering from past financial setbacks?

This ranking considers a wide spectrum of needs, from high-income individuals seeking personal loans to those battling credit challenges. We looked at specialized brokers, traditional credit unions, and digital-first lenders to ensure a diverse list that covers every traveler’s specific financial situation.

Lender Name Loan Types Credit Requirements Special Features
FastLendGo Personal Loans Good to Bad Credit Quick access to cash
My Financing USA RV and Boat Loans Good and Bad Credit Nationwide search
Southeast Financial Various Vehicle Loans See site Credit Union benefits
GreatRVLoan New, Used, Private Party Challenged Credit Terms up to 20 years
GadCapital Payday/Short-term No Credit Check Instant installments
Manhattan Bank Personal & Business See site FDIC-Insured

The Top-Rated RV Financing Lenders for 2026

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo functions as a versatile bridge for those who need immediate liquidity. While they offer specialized personal loans, their ability to cater to various credit tiers makes them a standout for quick financial needs. This is particularly useful for the “impulse buyer” who finds a perfect used camper at a private sale and needs to secure funds before the seller moves on to the next person. (fastlendgo.com)

This lender is particularly suited for individuals who need to bridge a gap in funds for smaller expenses. They offer a range of solutions from $500 up to larger personal loan amounts for high-income earners. Because these are often unsecured personal loans, they do not require you to use the RV itself as collateral, which can be a significant advantage if you want to keep your recreational vehicle separate from your primary debt obligations.

Pros:
  • Covers a wide range of credit scores from bad to great.
  • Offers quick access to cash for various needs.
  • Specialized options for high-income individuals.
Cons:
  • Focuses more on personal loans than dedicated RV-specific structured financing.

2. My Financing USA

My Financing USA – myfinancingusa.com

If your heart is set on a specific boat or a massive fifth wheel, My Financing USA acts as a dedicated navigator. They specialize in searching nationwide to find the best programs for your specific lifestyle vehicle. They don’t just look at one bank’s catalog; they scan the landscape to match your profile with the most appropriate lender.

They are a powerhouse for those looking at diverse recreational assets. From camper vans to yachts and even jet skis, their scope is impressively broad, making them a one-stop shop for water and land enthusiasts alike. This breadth is essential for the lifestyle traveler who may own a motorhome for the highways and a boat for the coast, wanting to consolidate their recreational financing efforts through a single, expert source.

Pros:
  • Extensive variety including boats, RVs, and even jet skis.
  • Nationwide search for the best possible programs.
  • Specific options for both good and bad credit.
Cons:
  • The breadth of products may lead to more complex application processes.

3. Southeast Financial

Southeast Financial – southeastfinancial.com

As a full-service credit union, Southeast Financial provides a stable, member-focused environment. They offer a comprehensive suite of services that extend far beyond just vehicle loans, including mortgages and wealth management. This makes them an excellent choice for someone who wants to centralize their entire financial life—from their primary mortgage to their weekend adventure vehicle—under one roof.

This is an ideal choice for the established traveler who wants their financing tied to a broader banking relationship. Their membership-based structure often provides a different level of personalized service and community-oriented benefits. Because credit unions are non-profit entities, they often return value to their members in the form of lower interest rates on loans or higher yields on savings accounts compared to traditional commercial banks.

Pros:
  • Comprehensive financial services from insurance to wealth management.
  • Credit union structure offers member-centric benefits.
  • Wide array of loan products including auto and home.
Cons:
  • Membership requirements may limit availability to certain groups.

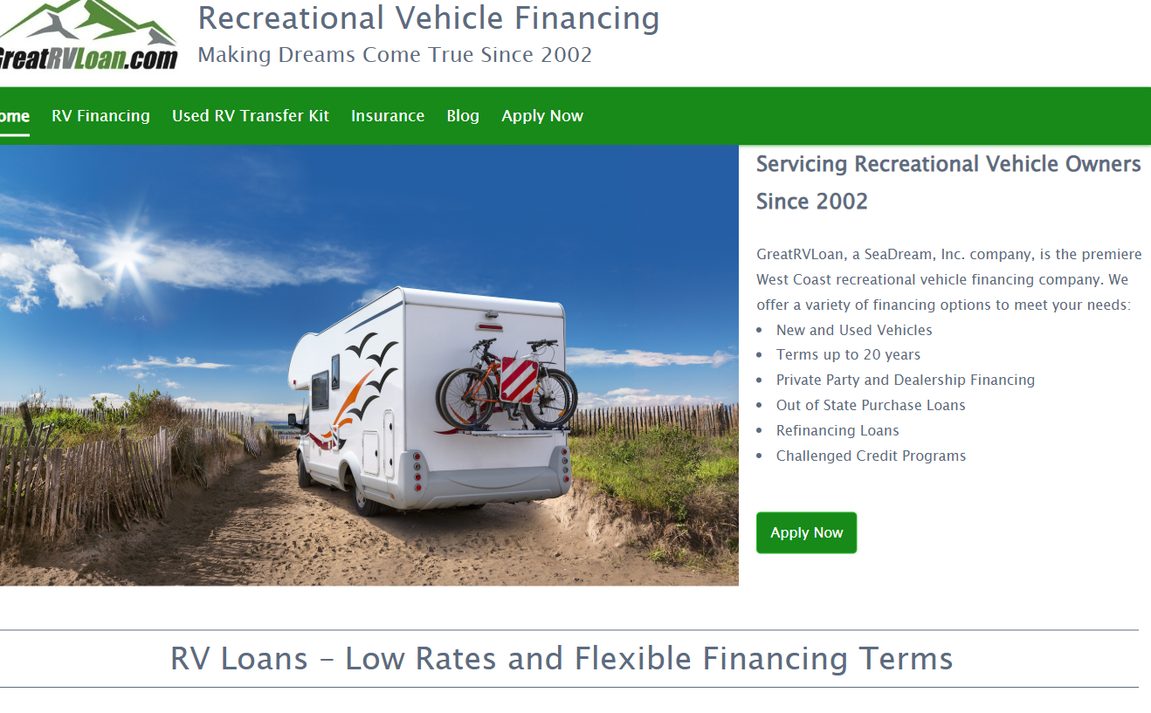
4. GreatRVLoan

GreatRVLoan – greatrvloan.com

GreatRVLoan is a specialized West Coast brokerage that has been navigating the RV financing landscape since 2002. They understand that a recreational vehicle is more than a machine; it is a way to achieve a dream. Their tenure in the market gives them an edge in understanding how depreciation rates on different RV models affect loan approval and interest rates.

They excel in complex scenarios, such as out-of-state purchases or private party transactions. Many traditional lenders shy away from “private party” sales—where you buy a camper from an individual rather than a dealership—because of the increased risk and lack of standardized paperwork. GreatRVLoan, however, has established workflows to handle these transactions, making them a vital resource for the savvy used-market buyer.

Pros:
  • Expertise in specialized scenarios like private party sales.
  • Extremely flexible terms reaching up to 20 years.
  • Handles challenged credit programs effectively.
Cons:
  • As a brokerage, they may act as an intermediary rather than the direct lender.

5. GadCapital

GadCapital – gadcapital.com

Sometimes, financial emergencies don’t wait for a scheduled payment. GadCapital focuses on the immediate, providing high-speed installment and payday loans for those facing urgent, short-term cash needs. This might include sudden repair costs for a rig that has broken down in the middle of a trip, or unexpected taxes that must be paid before a seasonal camping trip can begin.

This lender is designed for speed and accessibility, specifically targeting those who might struggle to find traditional bank support. They offer a direct route to cash through a simple, digital-first application process. While these are not long-term financing solutions for purchasing a multi-thousand-dollar motorhome, they serve as a vital liquidity tool for the unexpected costs of the RV lifestyle.

Pros:
  • Designed for immediate, urgent financial needs.
  • No credit check options available for quick access.
  • Simple online application for fast results.
Cons:
  • High-speed, short-term loans often come with higher costs.

6. Manhattan Bank

Manhattan Bank – manhattanbank.com

Manhattan Bank offers the security of a traditional, FDIC-insured institution. They provide a structured environment for those seeking personal or business loans through established, regulated banking channels. This is a primary choice for entrepreneurs who want to finance a luxury RV through their business entity as a tax-deductible business expense.

This is the best fit for the conservative borrower who prioritizes the safety and stability of a regulated bank. They focus on providing loans for “every occasion” within a professional, secure framework. While they may not have the “flashy” digital interfaces of a fintech startup, their institutional stability offers peace of mind that their long-term financial standing is backed by a massive, regulated entity.

Pros:
  • FDIC-insured, offering high levels of security and trust.
  • Established, professional banking environment.
  • Versatile personal and business loan options.
Cons:
  • Traditional banking processes can be slower than fintech competitors.

Key Factors to Consider Before Signing Your RV Loan

Securing a loan is only the first half of the equation; managing it is the second. Because RVs are depreciating assets—meaning they lose value over time—it is crucial to understand how your loan’s structure interacts with the vehicle’s value.

Understanding Depreciation and “Upside-Down” Loans

One of the greatest risks in RV financing is becoming “upside-down” or “underwater” on your loan. This happens when the amount you owe on the loan is greater than the actual market value of the RV. This is particularly common with new, high-end motorhomes that experience a sharp drop in value the moment they are driven off the lot. To mitigate this, aim for a significant down payment (20% is often recommended) to ensure you have equity in your vehicle from day one.

The Total Cost of Ownership (TCO) Equation

When calculating your budget, do not just look at the monthly loan payment. A realistic budget must include the following “hidden” costs of RV ownership:

Expense Category Typical Monthly Impact Notes
Insurance $100 – $300+ Specialized RV insurance is different from auto insurance.
Storage Fees $50 – $200 Necessary if you don’t have driveway space.
Maintenance $100 – $500 Includes oil changes, tire rotations, and roof inspections.
Campground Fees Variable Can range from $30 (primitive) to $150+ (resort).

The road to ownership is often paved with many different financial choices. Before signing any paperwork, it is vital to look beyond the monthly payment and examine the total cost of the loan over its entire lifespan. A $500 monthly payment might look manageable, but if that payment is spread over 20 years at a high interest rate, you could end up paying for the RV twice in total interest costs.

Avoid the trap of only looking at the immediate approval. A quick approval might come at a steep interest rate cost that bites you later. Always ask about prepayment penalties, as these can prevent you from paying off your RV early to save money. If you come into a windfall or receive a tax refund, you want the freedom to reduce your principal without being penalized by the lender.

Lastly, ensure your documentation is ready to go. Whether you are dealing with a specialized broker or a massive bank, having your income verification (W-2s, recent pay stubs, or tax returns for self-employed individuals) and credit history ready can turn a weeks-long process into a matter of days. Preparation is the difference between securing the perfect rig and seeing it sold to someone else while you’re still waiting on a credit check.

Top 5 Lenders for Bad Credit Loans in Virginia: 2026 Rankings

Bad credit loans virginia

Top 5 Lenders for Bad Credit Loans in Virginia: 2026 Rankings

Last updated: 2026-10-17

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Trying to manage money in the Commonwealth can feel like driving through a thick fog when your credit score isn’t where it needs to be. Many Virginians find themselves staring at a sudden car repair bill or a medical invoice, searching for a lifeline that won’t sink their financial future. Whether you are dealing with a transmission failure on I-95 or a dental bill in Alexandria, the pressure to find quick cash can cloud your judgment.

Finding a lender requires looking past the flashy ads to see what actually matters. You need speed, transparency, and accessibility. It is not just about the amount of money you get today, but how much that money will ultimately cost you over the next six months. This list highlights options for people who need cash quickly but want to understand the fine print before signing anything.

  1. OppLoans
  2. MaxCash
  3. JetzLoan
  4. Vacu
  5. 1st Advantage

Evaluating Lenders Across the Old Dominion

We selected these lenders based on how accessible they are to residents in cities like Richmond, Norfolk, and Virginia Beach. The application process shouldn’t feel like a mountain of paperwork. Speed of funding is a massive factor for anyone in a crisis. An eviction notice or a utility shut-off notice doesn’t wait five or seven business days like a traditional bank might require for a manual review.

Getting your money quickly is vital. Some lenders provide funds within the same business day, while others take longer to process the paperwork. We also considered the impact of the inquiry on a FICO score. Many people cannot afford a dip in their rating during a tight spot. A “hard pull” can linger on your credit report for years, potentially affecting an auto loan or a mortgage later.

A “soft pull” is a much safer way to shop around without penalty. It lets you check your options without the fear of a sudden drop in your rating. If you are testing the waters, look for lenders that offer this flexibility so you can compare rates without any risk to your credit history.

Quick Comparison of Virginia Lending Options

Lender Loan Amounts Funding Speed Credit Check Impact Key Feature
OppLoans $500 – $5,000 Same-day available No impact on FICO No hidden fees
MaxCash $250 – $10,000+ Minutes to approve Free inquiry Multiple loan types
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull High customer rating
Vacu As low as $100 See site See site Refinance options
1st Advantage Up to $750 See site No credit check option Short-term focus

Ranking the Best Options for Bad Credit in Virginia

1. OppLoans

OppLoans – opploans.com

OppLoans works well for those who need to move fast without worrying about their credit score. Their platform is built for people who might have been turned down by traditional banks due to a less-than-perfect history. They prioritize accessibility for people who are often overlooked by the big banks. Instead of looking only at a FICO score, they often consider your ability to repay through consistent income and banking history.

The application process is designed to be quick, often yielding decisions within minutes. If you are approved, same-day funding can be a huge relief when an emergency strikes. It is a practical tool for those needing a bridge to the next paycheck, acting as a buffer between a sudden expense and your next direct deposit.

Pros:

  • Applying does not affect your FICO credit score.
  • Same-day funding is available for approved applicants.
  • No hidden fees in the fine print.

Cons:

  • Loan amounts are limited compared to larger banks.

2. MaxCash

MaxCash – maxcash.com

MaxCash functions as a versatile shop for various financial needs, ranging from simple cash advances to significant installment loans. They offer a wide spectrum of loan amounts, making them a flexible choice for different levels of urgency. If you need $300 to cover a utility bill, they can help. If you need $5,000 to repair a vehicle used for work, they can accommodate that too.

The platform is highly accessible, allowing for a personalized inquiry without any obligation. Whether you need a small amount for groceries or a larger sum for a car, their diverse product list covers many bases for Virginia residents. The ability to check your eligibility without a hard inquiry is a standout feature for anyone testing different lending products.

Pros:

  • Wide range of loan amounts from $250 to $10,000+.
  • Free inquiry with no obligation to move forward.
  • Offers various products including title and installment loans.

Cons:

  • The variety of products can be overwhelming for some users.

3. JetzLoan

JetzLoan – jetzloan.com

JetzLoan focuses heavily on transaction speed, aiming to get funds into your account in as little as 24 hours. This is ideal for someone who needs a quick fix for a sudden problem and doesn’t want to wait a week for processing. Their digital-first approach minimizes the red tape that often plagues traditional lending. (jetzloan.com)

They offer significant loan amounts, reaching up to $35,000, which is quite substantial for a lender that emphasizes speed. This makes them a viable option for larger, unexpected expenses like a major medical procedure or an urgent home repair. Their process is transparent, and the “no hard credit pull” feature ensures your score remains untouched during the initial phase.

Pros:

  • High customer rating of 4.7 stars.
  • Fast funding within 24 hours of approval.
  • No hard credit pull during the rate check.

Cons:

  • The quick application may feel rushed to some users.

4. Vacu

Vacu – vacu.org

Vacu operates more like a traditional credit union, which often means a different level of service. Unlike many online-only lenders, credit unions are member-owned. This can sometimes translate to more favorable terms for those who qualify. They offer personal loan options that can be as low as $100, providing a safety net for small needs like a quick trip to the pharmacy.

One interesting feature is their ability to help you refinance other loans, sometimes offering rates as low as 4.49% APR for specific refinancing scenarios. This can be a powerful tool for anyone looking to consolidate debt and lower monthly payments. By rolling several high-interest debts into a single, lower-interest loan, you can streamline your budget and free up monthly cash flow.

Pros:

  • Very low entry point for loan amounts.
  • Potential for refinancing existing loans at lower rates.
  • Offers a wide array of banking services beyond loans.

Cons:

  • Credit union membership requirements may apply.

5. 1st Advantage

1st Advantage – 1stadvantage.org

1st Advantage is a specialized option for those facing very immediate, short-term needs. Their short-term loans can go up to $750 and are specifically geared toward people who need to bridge a gap quickly without a standard credit check. This is a high-speed, low-complexity product designed for micro-emergencies.

This is a niche product meant for small, urgent expenses. It is not the place to go if you are looking to buy a car or renovate a kitchen, but for a quick emergency fix—like an unexpected $200 car maintenance fee—it is a very direct route. The simplicity of the application means you spend less time on a keyboard and more time solving the actual problem.

Pros:

  • No credit check required for certain short-term loans.
  • Specifically designed for urgent, unexpected expenses.
  • Simple application for quick cash needs.

Cons:

  • Loan amounts are relatively low compared to other lenders.

Understanding the Cost of Borrowing: APR vs. Monthly Payment

When you are in a rush, the most tempting number is the monthly payment. If a lender tells you that you only have to pay $50 a month, it sounds much more manageable than a lump sum. However, this is often where the hidden math of lending lives. You must look closely at the Annual Percentage Rate (APR). The APR includes interest and any origination fees or processing costs.

Consider this comparison:

Scenario Monthly Payment Total Interest/Fees Paid Total Cost of Loan
Option A (Lower APR) $100 $200 $1,200
Option B (Higher APR) $75 $500 $1,300

In the example above, Option B seems cheaper on a month-to-month basis, but it actually costs you more in the long run. Always calculate the total amount you will have paid by the end of the loan term. This “Total Cost of Credit” is the only number that truly reflects the impact on your long-term financial health.

How to Prepare for a Successful Application

To maximize your chances of approval and secure the best possible rates, you should gather your documentation before you even hit the “Apply” button. Most lenders will require a digital copy or a photo of the following:

  • Proof of Identity: A valid driver’s license or state-issued ID.
  • Proof of Income: Recent pay stubs, W-2 forms, or bank statements showing regular deposits.
  • Proof of Residency: A utility bill or lease agreement that matches your application address.
  • Active Bank Account: Most lenders will deposit funds via ACH, so ensure your routing and account numbers are handy.

Being organized doesn’t just speed up the process; it prevents errors. A single typo in your social security number or a mismatched address can trigger a manual review. This could delay your funding by several days, which is a critical delay if you are facing a time-sensitive emergency.

Navigating Your Borrowing Decisions

Choosing a lender is a bit like picking a pair of shoes; it has to fit your specific situation perfectly. If you need a large sum for a long-term project, a credit union might be your best bet. However, if your car broke down this morning, speed becomes your most important metric. There is no one-size-fits-all in the lending world; there is only the option that best serves your current crisis and your future budget.

Avoid the trap of only looking at the monthly payment amount. It is easy to get distracted by a small number, but the total cost of borrowing—including interest and any fees—is what actually impacts your wallet in the long run. Always read the terms to ensure there are no surprises, such as prepayment penalties that charge you a fee if you try to pay the loan off early.

Another common mistake is applying for multiple loans at once from different lenders. Even if the lender uses a soft pull that doesn’t hurt your score, a sudden spike in applications can sometimes raise red flags with traditional creditors later on. They may view multiple recent inquiries as a sign of credit seeking, which can suggest you are in deeper financial trouble than you actually are. Take a moment to breathe and compare your options carefully.

The 6 Best Lenders for Bad Credit Loans in Louisiana for 2026

Bad credit loans louisiana

The 6 Best Lenders for Bad Credit Loans in Louisiana for 2026

Last updated: 2026-10-16

Looking for a quick cash boost without the headache of a hard credit pull? A personal loan from JetzLoan Financial Services could be your smooth ride to financial relief—whether it’s a ,000 emergency or a ,000 debt‑consolidation plan. Their flexible rates and no‑credit‑check options mean you’re not stuck in a waiting room of paperwork. Want to compare offers by score? Check out 500‑point and higher plans, or dive into same‑day loans if time is tight. Ready for a hassle‑free solution? JetzLoan Financial Services is just a click away!

Trying to sort out your finances in Louisiana can feel like driving through a thick bayou fog without your headlights on. Many people here deal with credit scores that simply don’t show who they really are or their actual ability to pay back a loan. When a sudden car repair or an unexpected medical bill lands on your kitchen table, you need clear answers, not more confusion.

Whether you live in the busy streets of New Orleans or a quiet parish further inland, the pressure of money is a shared struggle for many hard-working Louisianans. Finding a lender that understands the reality of a low credit score is the first move toward getting back on your feet. This list looks at everything from local credit unions to digital lenders.

Each option offers a different route. You might need a quick cash infusion to get through the month or a long-term plan to consolidate nagging debts. Getting the right choice requires looking past the initial interest rate. You have to dig into the fine print of the terms, the conditions, and those repayment schedules.

  1. FastLendGo
  2. Coastline Credit Union
  3. LightStream
  4. United Finance
  5. Addition Fi
  6. GadCapital

How Louisiana Borrowers Are Evaluated

Picking a lender isn’t just a race to see who says yes the fastest. In the Pelican State, lenders look at several things, such as how steady your income is and your debt-to-income ratio. Credit scores are a big part of the puzzle, but they aren’t the only tool in the kit. Some lenders care more about your ability to pay them back through steady work.

For instance, a lender might ask for your last three months of bank statements to verify a consistent pattern of deposits. This can often carry more weight than a single dip in your FICO score caused by a one-time medical bill. Speed also matters when you are facing an emergency. If your car transmission dies on a Friday and you need to get to work by Monday, a two-week approval process might as well be a decade away.

We looked at these providers based on how accessible they are for people with less-than-perfect credit, how much they lend, and how fast they move from application to cash in hand. When you compare them, keep an eye on the “Total Cost of Borrowing.” This includes the interest rate along with any origination fees or administrative costs that might pop up during the closing process.

Lender Name Loan Amounts Interest Rates Funding Speed Credit Requirements
FastLendGo $500 – $5,000+ see site see site Bad/Fair Credit
Coastline Credit Union see site see site see site see site
LightStream see site 9.99% – 24.94% APR Next day Excellent Credit
United Finance Up to $20,000 see site see site see site
Addition Fi see site see site see site see site
GadCapital $100 – $5,000+ see site Instant No Credit Check

Top-Rated Options for Louisiana Residents

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo provides a way forward for people who might feel ignored by the big national banks. They specialize in various personal financing solutions, specifically for those who have a less-than-stellar credit history. Their digital-first approach aims to make the comparison process simple for local borrowers. You don’t have to drive from parish to parish to hunt for a specialist. You can evaluate your options right from your living room. (fastlendgo.com)

If you are facing a dental emergency or need to fix a leak in your roof, they offer several specialized loan types. Their platform handles everything from small $500 loans to larger $5,000 requests. It is built for people who need to move quickly without drowning in a mountain of paperwork. This makes them a useful tool for filling the gap between a sudden crisis and your next paycheck.

Pros:
  • Specializes in bad credit and fair credit loans.
  • Offers specific loans for auto repairs and dental work.
  • User-friendly online comparison tool.
Cons:
  • Lacks the personalized community feel of a local credit union.

2. Coastline Credit Union

Coastline Credit Union – coastlinecu.com

Credit unions are often the hidden gems of the financial world. Coastline Credit Union offers a more traditional, community-focused banking experience. For Louisianans who prefer a lender that feels like a neighbor rather than a faceless corporation, this is a strong contender. Because credit unions are member-owned cooperatives, their main goal is service rather than maximizing profit for shareholders. This often leads to more flexible terms for members.

They provide a variety of solutions, including standard loans and online banking features. While they might have stricter requirements than a payday lender, the relationship you build with a credit union can be incredibly helpful for your long-term financial health. If you maintain a steady relationship with them, you might find it easier to secure a mortgage or an auto loan later on, since they have a history of your reliability.

Pros:
  • Member-focused service model.
  • Offers online and mobile banking convenience.
  • Potential for better long-term rates through membership.
Cons:
  • May require membership eligibility.

3. LightStream

LightStream – lightstream.com

LightStream is a high-tier option for those who have worked hard to build a stellar credit profile. They aren’t the solution for someone currently in a deep credit hole. However, for those with excellent credit, they are hard to beat. They offer a streamlined application process that respects your time. This is an ideal choice for major life milestones where saving on interest can mean thousands of dollars over the life of the loan.

The platform is versatile, allowing you to fund everything from home remodels to wedding expenses. Their speed is impressive; many users report having funds in their accounts as quickly as the next day. This makes them a favorite for significant, planned life transitions. If you want to consolidate high-interest credit card debt into a single, lower-interest payment, LightStream’s structure is built for that exact purpose.

Pros:
  • Extremely fast funding, sometimes by the next day.
  • Low fixed rates with AutoPay discounts.
  • Highly versatile loan purposes.
Cons:
  • Requires excellent credit to access the best rates.
  • Not suitable for those with poor credit.

4. United Finance

United Finance – unitedfinance.com

United Finance is a seasoned veteran in the lending space, having been around since 1922. They bring a level of stability that is hard to find in the modern era of fintech. They offer both personal and auto loans designed to fit into a realistic budget. Their longevity in the market shows they can handle changing economic climates, from the Great Depression to the digital revolution.

Their approach focuses on making personal loans simple and accessible. They provide a dedicated team of friendly lenders to help guide you through the process. This human element is vital if you find digital applications confusing or overwhelming. It is especially helpful for borrowers with complex financial situations, such as self-employment income, that an automated algorithm might automatically reject.

Pros:
  • Decades of experience and stability.
  • Personal loans available up to $20,000.
  • Offers auto loans and refinancing options.
Cons:
  • More traditional structure may be slower than digital-only lenders.

5. Addition Fi

Addition Fi – additionfi.com

Addition Financial operates with a focus on helping members grow their wealth and manage daily banking. They are more than just a lender; they act as a full-service financial partner. From checking accounts to investment options, they aim to be a one-stop shop. This allows members to see their entire financial life in one place, making it easier to track spending and savings habits.

They offer competitive rates and encourage a community-based approach to banking. For those looking to move away from large national banks toward a more personalized experience, Addition Fi provides the tools to save, borrow, and invest in one place. Their ecosystem supports borrowers through various stages of life, from that first car loan to eventual retirement planning.

Pros:
  • Comprehensive suite of banking and investment services.
  • Referral programs to help grow the community.
  • Competitive rates for various products.
Cons:
  • Requires becoming a member to access all benefits.

6. GadCapital

GadCapital – gadcapital.com

When the situation is dire and the clock is ticking, GadCapital is the “break glass in case of emergency” option. They specialize in online payday and installment loans for people with bad credit. They are designed for immediate action when conventional banks say no. This is a niche service for high-urgency situations where a standard three-day approval window is simply too long.

The platform allows for very small, quick loans, starting from as little as $100. If you are facing an urgent emergency—like a utility shut-off notice or an immediate medical co-pay—GadCapital is built to handle that pressure without a lengthy credit check. However, you must be extremely disciplined with repayment to avoid the compounding effects of high interest.

Pros:
  • No credit checks for certain loan types.
  • Instant access to funds for urgent needs.
  • Flexible amount ranges from $100 to $5,000+.
Cons:
  • Payday-style loans often come with very high costs.
  • Risk of a debt cycle if not managed carefully.

Understanding the Total Cost of Borrowing

Many borrowers make the mistake of only looking at the monthly payment. For example, a $500 loan with a $50 monthly payment sounds affordable. But if that loan lasts for twelve months, you have paid $600 for a $500 loan. That is a 20% increase in cost. Always ask for the “Total Repayment Amount” before you sign anything. This figure tells you exactly how much cash will have left your pocket by the time the debt is settled.

You should also be aware of the difference between APR (Annual Percentage Rate) and the nominal interest rate. The APR includes not just the interest you pay, but also the fees associated with getting the loan, like origination or processing fees. If you are comparing two lenders, the one with the lower APR is almost always the better deal, even if the other has a lower stated interest rate but higher upfront fees.

Steps to Prepare for a Loan Application

To increase your chances of approval and secure the best terms, follow these three preparation steps:

  1. Audit Your Documents: Gather your most recent pay stubs, W-2 forms, and utility bills. Lenders want to see proof of residency and a consistent stream of income. Having these ready to upload can speed up your approval from days to minutes.
  2. Check for Errors: Free services like AnnualCreditReport.com allow you to see what is in your file. If there is a mistake—such as a debt that has already been paid being listed as active—dispute it immediately. A single error can be the difference between a 620 score and a 650 score.
  3. Calculate Your Debt-to-Income (DTI) Ratio: Add up all your monthly debt obligations, like rent, car payments, and credit card minimums, and divide that by your gross monthly income. Most lenders prefer a DTI below 36-43%. Knowing this number helps you understand how much more debt you can realistically afford.

Navigating the Loan Process

Before you sign your name, take a deep breath and look at the fine print. It is easy to get caught up in the excitement of an instant approval, but the total cost of the loan is what matters most in the end. Always check the APR, not just the monthly payment, to see the true cost of borrowing.

One common mistake is ignoring the impact of late payments. Even if a lender is willing to work with your bad credit, a single missed payment can act like a stone in your shoe, causing pain for years to come. Always ensure the monthly installment fits comfortably within your existing budget, leaving room for groceries and rent. A “buffer” in your budget is your best defense against future emergencies.

Another pitfall is the “quick fix” trap. While payday loans like those from GadCapital can save you from a crisis today, they can lead to a mountain of debt tomorrow if you aren’t careful. Use them sparingly and only for true emergencies. If you can, try to build towards more stable, long-term options like credit unions or personal loans from established firms. Building a history of on-time payments is the most effective way to climb out of a credit hole and achieve long-term financial freedom.